
You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register
i everyone,i have a strategy that isn't bad in trading,and i want to know how can i add this svm nn to my expert to filtrate the bad signals,any help are really apreciated,thank you
Any help..................
that's my expert test from 300$ to 7000$ in one month,if i can add a NN to filter signals that's gonna to be more good than that...
Any help..................
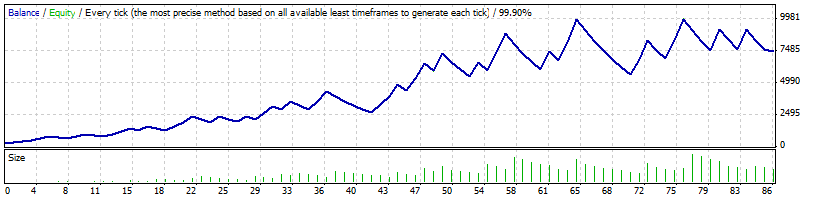
that's my expert test from 300$ to 7000$ in one month,if i can add a NN to filter signals that's gonna to be more good than that...Why do you expect that NN will improve your EA?
If you did not base the EA on the NN from the start it will be difficult to incorporate NN - and just t start, you will have to decide to use one of the 100s of theoretical models that you will have to translate to MQL then. Already the choice of NN approach will be difficult enough if you do not use some already
but can we use NN like a filter for signals?
but can we use NN like a filter for signals?
ziko87
NN is usually used for "prediction". As such ("prediction") I doubt that it can be used as a filter
Different pack of bpnn bpnn.zip
I looked in vain for a contact email address - could you post it? As a paid-up owner, it can only help if as many of us as possible complain...
go here
Neural Network
Neural Network: discussion/development threads
Neural Network: Indicators and systems development
Neural Network: EAs
Neural Network: The Books
The article
CodeBase
I am not fully understand about what they are talking about ... something related to this page:
https://cs.stanford.edu/people/karpathy/convnetjs/demo/rldemo.html
..and something about the following ("machine translation" from Russian):
Forum on trading, automated trading systems and testing trading strategies
Machine learning in trading: theory, models, practice and algorithmic trading
mytarmailS , 2022.09.07 07:24
It makes no sense to look at the old model, it does not capture market changes.Here is an example on a randomly generated sample of 5 features and 1 binary target
for forest and feature selector
In R, of course, it is not customary to write in cycles if it is not necessary, but this style confuses beginners, and middle peasants, like me, also confuses ..
but you can write short and so, the code is 3 times less, the result is the same
Also , different feature selectors for every taste, probably 5% of what is in R-ke
ONNX and MQL5 Copilot
The forum
CodeBase
Documentation