
Delta Aggression Volume
- Indicators
-
JETINVEST
 Roberto Junqueira, is Trader for over 20 years and has been developing indicators and trading experts for more than 10 years for the Forex, Cryptocurrencies and Stock Exchanges markets.
- Version: 3.20
- Updated: 3 November 2026
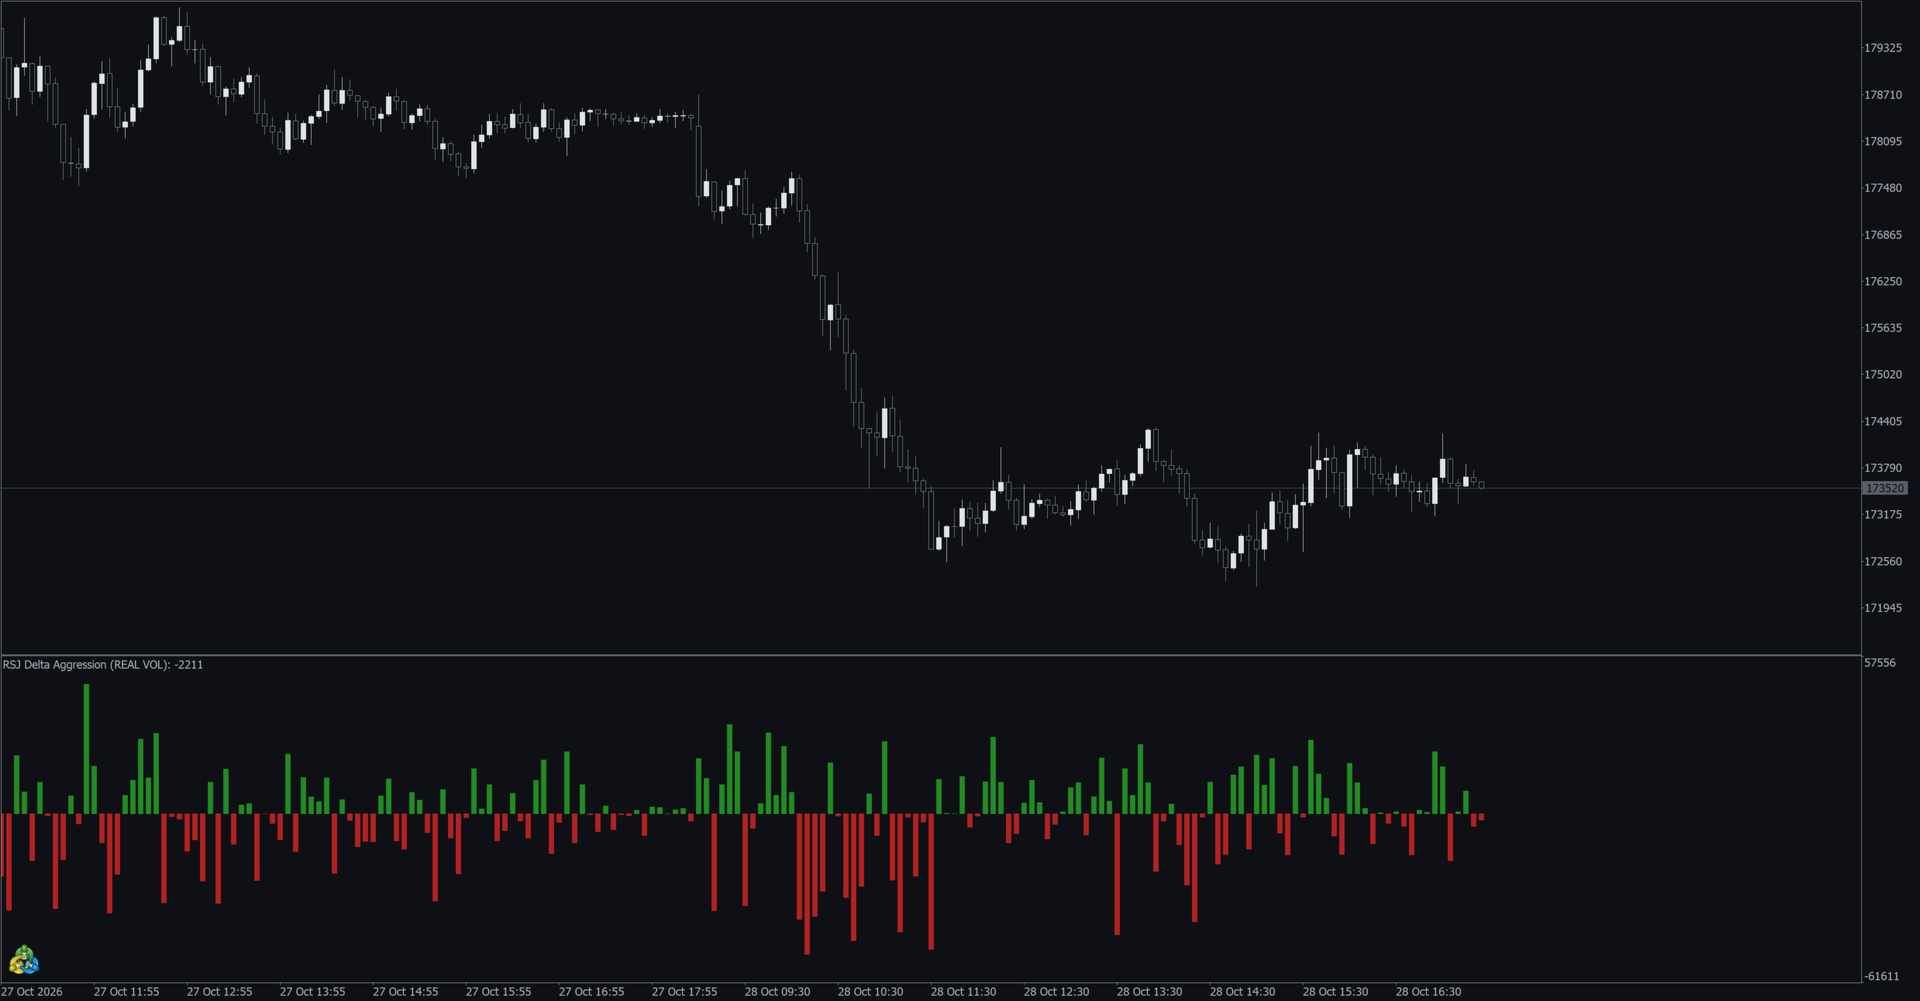
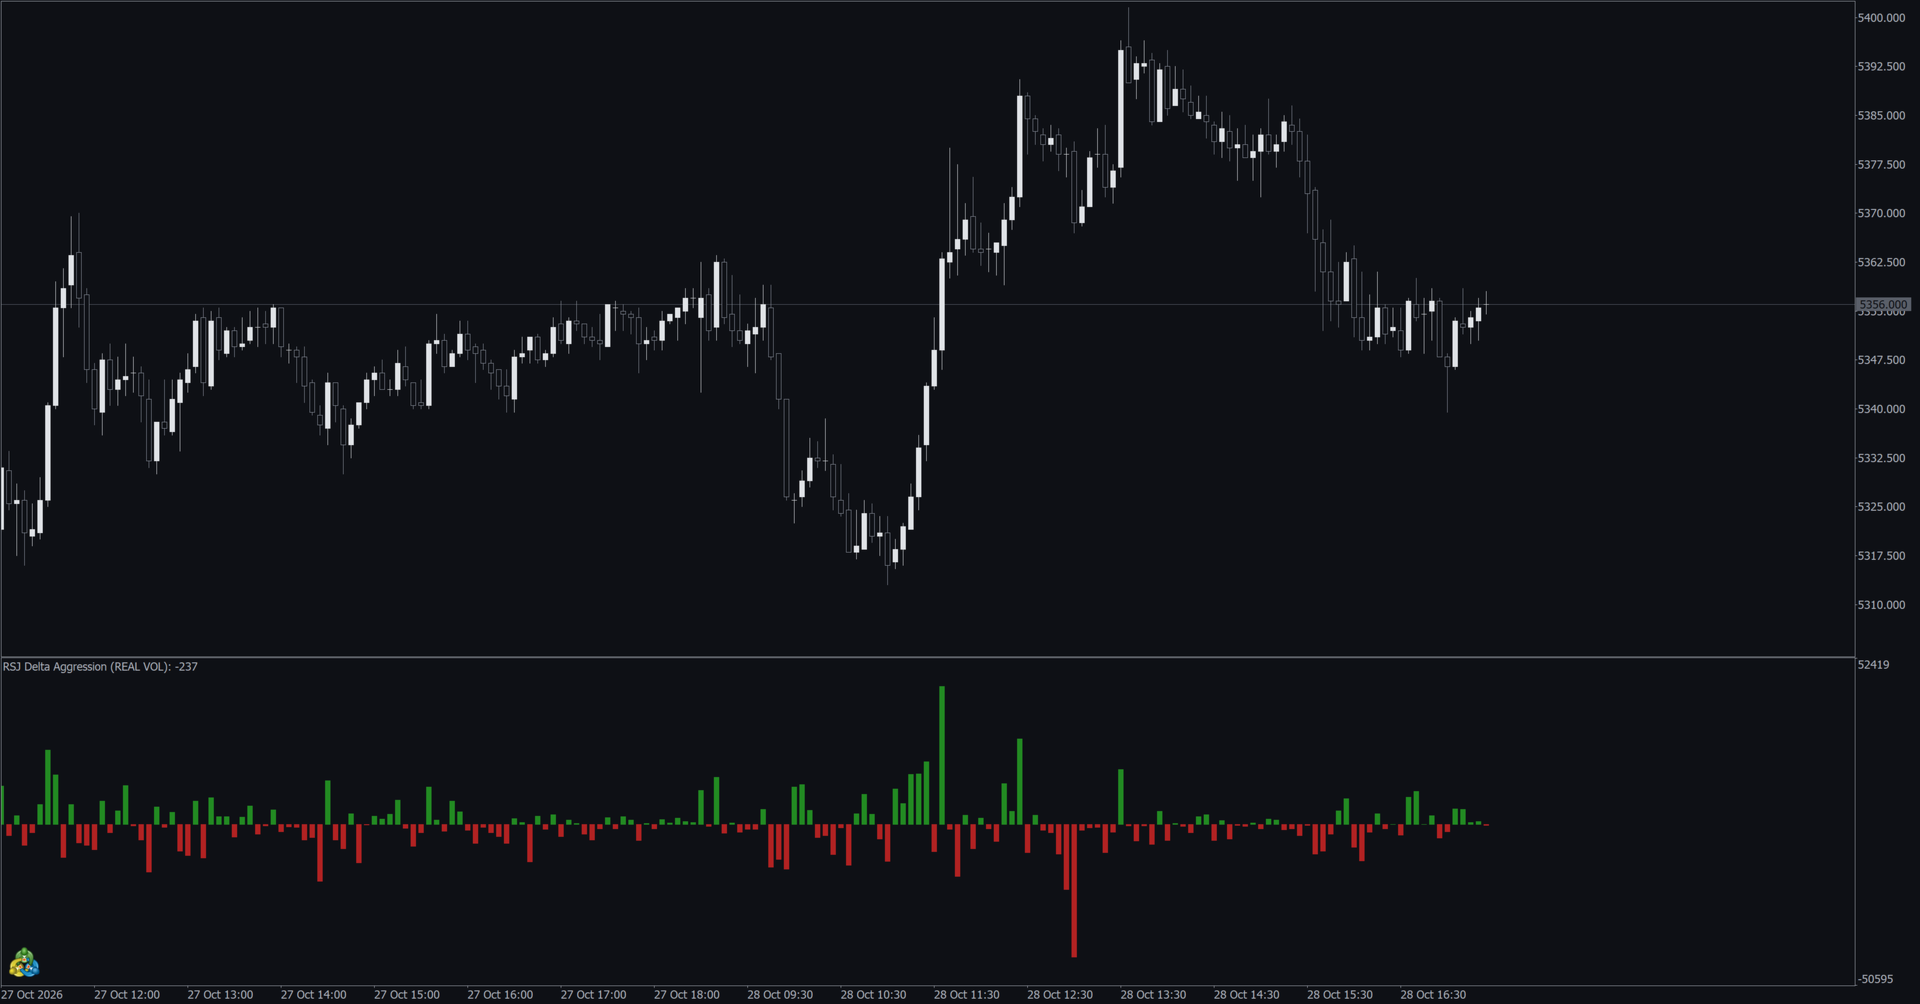
Delta Aggression Volume shows, candle by candle, whether aggressive buyers or aggressive sellers traded more, on symbols with real trades such as B3 and CME futures.
WHAT IT DOES
- Computes the aggression delta of each candle: volume of aggressive buys minus volume of aggressive sells.
- Plots the balance of every candle in a separate window, colored by the side that won.
REQUIREMENTS
- Exchange symbols with real trades: B3 futures and stocks (WIN, WDO, PETR4 …) and CME futures (ES, NQ, CL, GC and their micro contracts).
- The broker feed must report the aggressor side (buy or sell) of each trade. Forex, crypto and CFD feeds do not provide this data, so the indicator stays empty there.
INPUTS
- Volume type: real volume or number of trades (tick volume).
- Calculation start: from the last day up to all available days.
DELTA AGGRESSION VOLUME PRO
The Delta Aggression Volume PRO uses the same calculation and adds reverse bars, a range channel with two calculation modes, a moving average of the total volume, 6 configurable alerts and 20 buffers for Expert Advisors. The 6 alert buffers (13-18) can be read with iCustom: +1 buy, −1 sell, 0 no signal. It pairs with Aggression Wave PRO, which accumulates the delta into waves.
FAQ
Why is the indicator empty? The symbol has no aggressor-side data. Use it on B3 or CME symbols with a broker that delivers each trade with its aggressor side (buy or sell).
Why does the first load take a while? The indicator processes every trade since the calculation start. Lower timeframes and an earlier start take longer.
Is this a trading signal? No. It shows who is aggressing in the market. Use it with your own entry and risk rules.
STRATEGY TESTER
- Works in the Strategy Tester on B3 symbols, with "Every tick based on real ticks" or "Every tick".
- The calculation starts at the test start date, because the tester provides no ticks before it.
- With real ticks, the aggressor side comes from each trade. Ticks generated by the tester have no buy/sell flag, so the side is estimated by the tick rule (price up = buy, price down = sell).
Full user manual (with images): www.mql5.com/en/blogs/post/779253


















































Very good