

Automatización de estrategias de trading en MQL5 (Parte 26): Desarrollo de un sistema de promediado basado en Pin Bar para la gestión de múltiples posiciones
 55
 0

Introducción
En nuestro artículo anterior (Parte 25), desarrollamos un sistema de trading con líneas de tendencia en MetaQuotes Language 5 (MQL5) que utilizaba el ajuste de mínimos cuadrados para detectar líneas de tendencia de soporte y resistencia, generando operaciones automáticas basadas en los toques del precio con retroalimentación visual. En la Parte 26, creamos un programa de «promedio de Pin Bar» que identifica patrones de velas «pin bar» para iniciar operaciones y gestiona múltiples posiciones mediante una estrategia de promedio, incorporando stops dinámicos, ajustes a break-even y un panel de control para el seguimiento en tiempo real. Trataremos los siguientes temas:
Al final, tendrás una potente estrategia en MQL5 para operar con patrones de velas pin bar, lista para personalizar. ¡Empecemos!
Estructura del sistema de promediación con pin bars
Estamos desarrollando un sistema de negociación automatizado que aprovecha los patrones de velas «pin bar», que son formaciones de una sola vela caracterizadas por una mecha larga y un cuerpo pequeño, y que a menudo indican fuertes reversiones de precios en niveles clave del mercado. Las estrategias basadas en las barras pin son muy populares en el mundo del trading porque permiten identificar los momentos en los que se produce un rechazo del precio, lo que ofrece puntos de entrada con alta probabilidad para las operaciones, especialmente cuando se combinan con los niveles de soporte y resistencia. Aquí se muestra una visualización de algunas formaciones comunes.
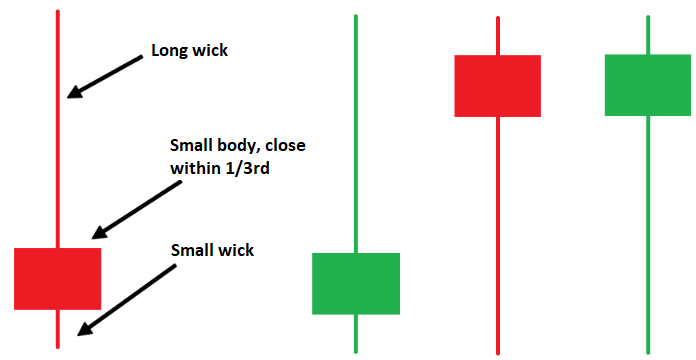
Nuestro enfoque se centrará en detectar estas barras pin en el marco temporal actual y en utilizar una estrategia de promediado para abrir posiciones adicionales si el mercado se mueve en contra de la operación inicial. El objetivo es mejorar el resultado global de las operaciones, al tiempo que se gestiona el riesgo mediante el uso de órdenes stop dinámicas y ajustes a break-even. Para lograrlo, en primer lugar identificaremos las barras pin en relación con un nivel de soporte o resistencia derivado del cierre de la vela anterior en el timeframe H4, asegurándonos de que las operaciones se ajusten a las zonas significativas del mercado.
A continuación, implementaremos un mecanismo de promediado para ir añadiendo posiciones a intervalos de precio predefinidos, lo que aumentará la flexibilidad en condiciones de volatilidad. Por último, incorporaremos un panel de control para mostrar las métricas de las operaciones en tiempo real y utilizaremos indicadores visuales, como líneas, para marcar los niveles clave, para supervisar la estrategia y ajustarla con eficacia. Veamos qué buscamos lograr y luego pasaremos a la implementación.
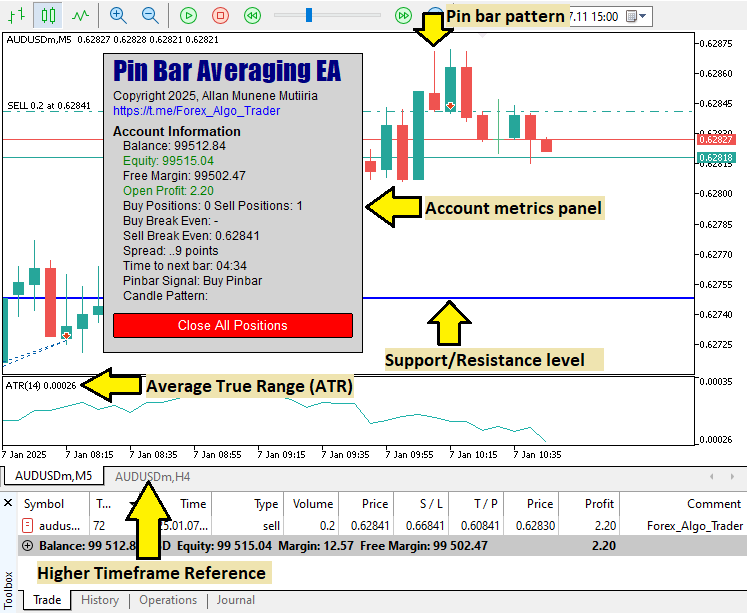
Implementación en MQL5
Para crear el programa en MQL5, abre el MetaEditor, ve al Navegador, busca la carpeta «Indicators», haz clic en la pestaña «Nuevo» y sigue las instrucciones para crear el archivo. Una vez creado, en el entorno de programación, empezaremos por declarar algunas entradas y variables globales que harán que el programa sea más dinámico.
//+------------------------------------------------------------------+
//|                                      a. Pin Bar Averaging EA.mq5 |
//|                           Copyright 2025, Allan Munene Mutiiria. |
//|                                   https://t.me/Forex_Algo_Trader |
//+------------------------------------------------------------------+
#property copyright   "Copyright 2025, Allan Munene Mutiiria."
#property link        "https://t.me/Forex_Algo_Trader"
#property version     "1.00"
#property strict

#include <Trade\Trade.mqh>                         //--- Include Trade library for trading operations
CTrade obj_Trade;                                  //--- Instantiate trade object

//+------------------------------------------------------------------+
//| Trading signal enumeration                                       |
//+------------------------------------------------------------------+
enum EnableTradingBySignal {                       //--- Define trading signal enum
   ENABLED  = 1,                                   // Enable trading signals
   DISABLED = 0                                    // Disable trading signals
};

//+------------------------------------------------------------------+
//| Input parameters                                                 |
//+------------------------------------------------------------------+
input bool   useSignalMode = DISABLED;             // Set signal mode (ENABLED/DISABLED)
input int    orderDistancePips = 50;               // Set order distance (pips)
input double lotMultiplier = 1;                    // Set lot size multiplier
input bool   useRSIFilter = false;                 // Enable RSI filter
input int    magicNumber = 123456789;              // Set magic number
input double initialLotSize = 0.01;                // Set initial lot size
input int    compoundPercent = 2;                  // Set compounding percent (0 for fixed lots)
input int    maxOrders = 5;                        // Set maximum orders
input double stopLossPips = 400;                   // Set stop loss (pips)
input double takeProfitPips = 200;                 // Set take profit (pips)
input bool   useAutoTakeProfit = true;             // Enable auto take profit
input bool   useTrailingStop = true;               // Enable trailing stop
input double trailingStartPips = 15;               // Set trailing start (pips)
input double breakevenPips = 10;                   // Set breakeven (pips)
input string orderComment = "Forex_Algo_Trader";   // Set order comment
input color  lineColor = clrBlue;                  // Set line color
input int    lineWidth = 2;                        // Set line width

//+------------------------------------------------------------------+
//| Global variables                                                 |
//+------------------------------------------------------------------+
bool   isTradingAllowed();                         //--- Declare trading allowed check
double slBreakevenMinus = 0;                       //--- Initialize breakeven minus
double normalizedPoint;                            //--- Declare normalized point
ulong  currentTicket = 0;                          //--- Initialize current ticket
double buyCount, currentBuyLot, totalBuyLots;      //--- Declare buy metrics
double sellCount, currentSellLot, totalSellLots;   //--- Declare sell metrics
double totalSum, totalSwap;                        //--- Declare total sum and swap
double buyProfit, sellProfit, totalOperations;     //--- Declare profit and operations
double buyWeightedSum, sellWeightedSum;            //--- Declare weighted sums
double buyBreakEvenPrice, sellBreakEvenPrice;      //--- Declare breakeven prices
double minBuyLot, minSellLot;                      //--- Declare minimum lot sizes
double maxSellPrice, minBuyPrice;                  //--- Declare price extremes
Para sentar las bases del sistema Pin Bar Averaging en MQL5, con el fin de automatizar las operaciones basándonos en patrones de pin bar y con un sistema robusto de gestión de posiciones, primero incluimos la biblioteca «<Trade\Trade.mqh>» y creamos una instancia de «obj_Trade» como objeto CTrade para gestionar operaciones como la apertura y el cierre de posiciones. A continuación, procedemos a definir la enumeración «EnableTradingBySignal» con «ENABLED» (1) y «DISABLED» (0) para controlar si se utilizan señales de trading para la gestión de posiciones. A continuación, configuramos los parámetros de entrada para personalizar el EA: un valor booleano para activar o desactivar el modo de señal, la distancia de la orden en pips, el multiplicador del tamaño del lote, el filtro RSI (activado o desactivado), el número mágico para la identificación de la operación, el tamaño inicial del lote, el porcentaje de capitalización (0 para lotes fijos), el número máximo de órdenes, el stop loss y el take profit en pips, las opciones de take profit automático y trailing stop, el inicio del trailing y el punto de equilibrio en pips, el comentario de la orden, y el color y el grosor de las líneas de los indicadores visuales.
Por último, declaramos variables globales: una función «isTradingAllowed» para comprobar las condiciones de negociación, «slBreakevenMinus» inicializada en 0 para los ajustes de stop loss, «normalizedPoint» para el escalado de precios, «currentTicket» para el seguimiento de las operaciones, contadores y sumas como «buyCount», «currentBuyLot», «totalBuyLots», «sellCount», «currentSellLot», «totalSellLots», «totalSum», «totalSwap», «buyProfit», «sellProfit», «totalOperations», «buyWeightedSum», «sellWeightedSum», «buyBreakEvenPrice», «sellBreakEvenPrice», «minBuyLot», «minSellLot», «maxSellPrice» y «minBuyPrice» para las métricas de posición, estableciendo así el marco básico del EA para la detección de barras pin y el cálculo de medias. Ahora podemos pasar a inicializar el programa, ya que la mayor parte de la lógica se ejecutará tick a tick.
//+------------------------------------------------------------------+
//| Expert initialization function                                   |
//+------------------------------------------------------------------+
int OnInit() {
   normalizedPoint = _Point;                       //--- Initialize point value
   if (_Digits == 5 || _Digits == 3) {             //--- Check for 5 or 3 digit symbols
      normalizedPoint *= 10;                       //--- Adjust point value
   }
   ChartSetInteger(0, CHART_SHOW_GRID, false);     //--- Disable chart grid
   obj_Trade.SetExpertMagicNumber(magicNumber);    //--- Set magic number for trade object
   obj_Trade.SetTypeFilling(ORDER_FILLING_IOC);    //--- Set order filling type
   return(INIT_SUCCEEDED);                         //--- Return success
}

//+------------------------------------------------------------------+
//| Expert deinitialization function                                 |
//+------------------------------------------------------------------+
void OnDeinit(const int reason) {
   ObjectsDeleteAll(0);                            //--- Delete all chart objects
   ChartRedraw(0);                                 //--- Redraw chart
}
En primer lugar, en el controlador de eventos OnInit, inicializamos «normalizedPoint» como _Point y lo ajustamos multiplicándolo por 10 para los símbolos de 5 o 3 dígitos utilizando _Digits, con el fin de garantizar la precisión en los cálculos de precios; desactivamos la cuadrícula del gráfico con ChartSetInteger, estableciendo CHART_SHOW_GRID en false para obtener una visualización más limpia, configuramos «obj_Trade» con «SetExpertMagicNumber» utilizando «magicNumber» para la identificación de la operación, establecemos el tipo de ejecución de la orden en «ORDER_FILLING_IOC» con «SetTypeFilling», y devolvemos «INIT_SUCCEEDED» para confirmar que la configuración se ha realizado correctamente. A continuación, pasamos al controlador de eventos OnDeinit, donde eliminamos todos los objetos del gráfico con ObjectsDeleteAll para borrar elementos visuales como el panel de control y las líneas que definiremos más adelante; solo lo hemos hecho para asegurarnos de que el gráfico ya está limpio, y llamamos a ChartRedraw para actualizar el gráfico, garantizando así una salida limpia. Antes de profundizar en la compleja lógica de negociación, definamos algunas funciones auxiliares que necesitaremos para que el programa sea dinámico y fácil de mantener.
//+------------------------------------------------------------------+
//| Count total trades                                               |
//+------------------------------------------------------------------+
int CountTrades() {
   int positionCount = 0;                         //--- Initialize position count
   for (int trade = PositionsTotal() - 1; trade >= 0; trade--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(trade);    //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) != Symbol() || PositionGetInteger(POSITION_MAGIC) != magicNumber) continue; //--- Skip non-matching positions
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL || PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check trade type
         positionCount++;                         //--- Increment position count
      }
   }
   return(positionCount);                         //--- Return total count
}

//+------------------------------------------------------------------+
//| Count buy trades                                                 |
//+------------------------------------------------------------------+
int CountTradesBuy() {
   int buyPositionCount = 0;                      //--- Initialize buy position count
   for (int trade = PositionsTotal() - 1; trade >= 0; trade--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(trade);    //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) != Symbol() || PositionGetInteger(POSITION_MAGIC) != magicNumber) continue; //--- Skip non-matching positions
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
         buyPositionCount++;                      //--- Increment buy count
      }
   }
   return(buyPositionCount);                      //--- Return buy count
}

//+------------------------------------------------------------------+
//| Count sell trades                                                |
//+------------------------------------------------------------------+
int CountTradesSell() {
   int sellPositionCount = 0;                     //--- Initialize sell position count
   for (int trade = PositionsTotal() - 1; trade >= 0; trade--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(trade);    //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) != Symbol() || PositionGetInteger(POSITION_MAGIC) != magicNumber) continue; //--- Skip non-matching positions
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
         sellPositionCount++;                     //--- Increment sell count
      }
   }
   return(sellPositionCount);                     //--- Return sell count
}

//+------------------------------------------------------------------+
//| Normalize price                                                  |
//+------------------------------------------------------------------+
double NormalizePrice(double price) {
   return(NormalizeDouble(price, _Digits));       //--- Normalize price to symbol digits
}

//+------------------------------------------------------------------+
//| Get lot digit for normalization                                  |
//+------------------------------------------------------------------+
int fnGetLotDigit() {
   double lotStepValue = SymbolInfoDouble(Symbol(), SYMBOL_VOLUME_STEP); //--- Get lot step value
   if (lotStepValue == 1) return(0);              //--- Return 0 for step 1
   if (lotStepValue == 0.1) return(1);            //--- Return 1 for step 0.1
   if (lotStepValue == 0.01) return(2);           //--- Return 2 for step 0.01
   if (lotStepValue == 0.001) return(3);          //--- Return 3 for step 0.001
   if (lotStepValue == 0.0001) return(4);         //--- Return 4 for step 0.0001
   return(1);                                     //--- Default to 1
}

//+------------------------------------------------------------------+
//| Check buy orders for specific magic number                       |
//+------------------------------------------------------------------+
int CheckBuyOrders(int magic) {
   int buyOrderCount = 0;                         //--- Initialize buy order count
   for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);         //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_MAGIC) != magic) continue; //--- Skip non-matching magic
      if (PositionGetString(POSITION_SYMBOL) == Symbol()) { //--- Check symbol
         if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
            buyOrderCount++;                      //--- Increment buy count
            break;                                //--- Exit loop
         }
      }
   }
   return(buyOrderCount);                         //--- Return buy order count
}

//+------------------------------------------------------------------+
//| Check sell orders for specific magic number                      |
//+------------------------------------------------------------------+
int CheckSellOrders(int magic) {
   int sellOrderCount = 0;                         //--- Initialize sell order count
   for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);         //--- Get position ticket
      if (ticket == 0) continue;                   //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_MAGIC) != magic) continue; //--- Skip non-matching magic
      if (PositionGetString(POSITION_SYMBOL) == Symbol()) { //--- Check symbol
         if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
            sellOrderCount++;                      //--- Increment sell count
            break;                                 //--- Exit loop
         }
      }
   }
   return(sellOrderCount);                         //--- Return sell order count
}

//+------------------------------------------------------------------+
//| Check total buy orders                                           |
//+------------------------------------------------------------------+
int CheckTotalBuyOrders(int magic) {
   int totalBuyOrderCount = 0;                      //--- Initialize total buy order count
   for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);          //--- Get position ticket
      if (ticket == 0) continue;                    //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_MAGIC) != magic) continue; //--- Skip non-matching magic
      if (PositionGetString(POSITION_SYMBOL) == Symbol()) { //--- Check symbol
         if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
            totalBuyOrderCount++;                   //--- Increment buy count
         }
      }
   }
   return(totalBuyOrderCount);                      //--- Return total buy count
}

//+------------------------------------------------------------------+
//| Check total sell orders                                          |
//+------------------------------------------------------------------+
int CheckTotalSellOrders(int magic) {
   int totalSellOrderCount = 0;                      //--- Initialize total sell order count
   for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);           //--- Get position ticket
      if (ticket == 0) continue;                     //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_MAGIC) != magic) continue; //--- Skip non-matching magic
      if (PositionGetString(POSITION_SYMBOL) == Symbol()) { //--- Check symbol
         if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
            totalSellOrderCount++;                   //--- Increment sell count
         }
      }
   }
   return(totalSellOrderCount);                      //--- Return total sell count
}

//+------------------------------------------------------------------+
//| Check market buy orders                                          |
//+------------------------------------------------------------------+
int CheckMarketBuyOrders() {
   int marketBuyCount = 0;                        //--- Initialize market buy count
   for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);         //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_MAGIC) != magicNumber) continue; //--- Skip non-matching magic
      if (PositionGetString(POSITION_SYMBOL) == Symbol()) { //--- Check symbol
         if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
            marketBuyCount++;                     //--- Increment buy count
         }
      }
   }
   return(marketBuyCount);                        //--- Return market buy count
}

//+------------------------------------------------------------------+
//| Check market sell orders                                         |
//+------------------------------------------------------------------+
int CheckMarketSellOrders() {
   int marketSellCount = 0;                       //--- Initialize market sell count
   for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);         //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_MAGIC) != magicNumber) continue; //--- Skip non-matching magic
      if (PositionGetString(POSITION_SYMBOL) == Symbol()) { //--- Check symbol
         if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
            marketSellCount++;                    //--- Increment sell count
         }
      }
   }
   return(marketSellCount);                       //--- Return market sell count
}

//+------------------------------------------------------------------+
//| Close all buy positions                                          |
//+------------------------------------------------------------------+
void CloseBuy() {
   while (CheckMarketBuyOrders() > 0) {           //--- Check buy orders exist
      for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
         ulong ticket = PositionGetTicket(i);      //--- Get position ticket
         if (ticket == 0) continue;               //--- Skip invalid tickets
         if (PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check symbol and magic
            if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
               obj_Trade.PositionClose(ticket);   //--- Close position
            }
         }
      }
   }
}

//+------------------------------------------------------------------+
//| Close all sell positions                                         |
//+------------------------------------------------------------------+
void CloseSell() {
   while (CheckMarketSellOrders() > 0) {          //--- Check sell orders exist
      for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
         ulong ticket = PositionGetTicket(i);      //--- Get position ticket
         if (ticket == 0) continue;               //--- Skip invalid tickets
         if (PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check symbol and magic
            if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
               obj_Trade.PositionClose(ticket);   //--- Close position
            }
         }
      }
   }
}

//+------------------------------------------------------------------+
//| Calculate lot size                                               |
//+------------------------------------------------------------------+
double GetLots() {
   double calculatedLot;                          //--- Initialize calculated lot
   double minLot = SymbolInfoDouble(Symbol(), SYMBOL_VOLUME_MIN); //--- Get minimum lot
   double maxLot = SymbolInfoDouble(Symbol(), SYMBOL_VOLUME_MAX); //--- Get maximum lot
   if (compoundPercent != 0) {                    //--- Check compounding
      calculatedLot = NormalizeDouble(AccountInfoDouble(ACCOUNT_BALANCE) * compoundPercent / 100 / 10000, fnGetLotDigit()); //--- Calculate compounded lot
      if (calculatedLot < minLot) calculatedLot = minLot; //--- Enforce minimum lot
      if (calculatedLot > maxLot) calculatedLot = maxLot; //--- Enforce maximum lot
   } else {
      calculatedLot = initialLotSize;             //--- Use fixed lot size
   }
   return(calculatedLot);                         //--- Return calculated lot
}

//+------------------------------------------------------------------+
//| Check account free margin                                        |
//+------------------------------------------------------------------+
double AccountFreeMarginCheck(string symbol, int orderType, double volume) {
   double marginRequired = 0.0;                   //--- Initialize margin required
   double price = orderType == ORDER_TYPE_BUY ? SymbolInfoDouble(symbol, SYMBOL_ASK) : SymbolInfoDouble(symbol, SYMBOL_BID); //--- Get price
   double calculatedMargin;                       //--- Declare calculated margin
   bool success = OrderCalcMargin(orderType == ORDER_TYPE_BUY ? ORDER_TYPE_BUY : ORDER_TYPE_SELL, symbol, volume, price, calculatedMargin); //--- Calculate margin
   if (success) marginRequired = calculatedMargin; //--- Set margin if successful
   return AccountInfoDouble(ACCOUNT_MARGIN_FREE) - marginRequired; //--- Return free margin
}

//+------------------------------------------------------------------+
//| Check if trading is allowed                                      |
//+------------------------------------------------------------------+
bool isTradingAllowed() {
   bool isAllowed = false;                        //--- Initialize allowed flag
   return(true);                                  //--- Return true
}
En este apartado, implementamos funciones de utilidad para que el programa gestione el recuento de operaciones, el cierre de posiciones, el cálculo del tamaño de los lotes, la comprobación de márgenes y los permisos de negociación, garantizando así una gestión sólida de las operaciones. En primer lugar, creamos funciones para contar las operaciones: «CountTrades» contabiliza el total de posiciones iterando a través de PositionsTotal, comprobando si hay tickets válidos con PositionGetTicket, cotejando «Symbol» y «magicNumber», e incrementando «positionCount» para las posiciones de compra o venta; «CountTradesBuy» y «CountTradesSell» cuentan las posiciones de compra y venta, respectivamente, filtrando por POSITION_TYPE_BUY o «POSITION_TYPE_SELL»; «CheckBuyOrders» y «CheckSellOrders» detectan al menos una posición de compra o venta con un número mágico específico, deteniéndose tras la primera coincidencia; «CheckTotalBuyOrders» y «CheckTotalSellOrders» cuentan todas las posiciones de compra o venta con un número mágico; y «CheckMarketBuyOrders» y «CheckMarketSellOrders» cuentan las posiciones de compra o venta con el número mágico.
A continuación, procedemos a implementar «NormalizePrice» para normalizar los precios a _Digits utilizando NormalizeDouble, y «fnGetLotDigit» para devolver la precisión decimal adecuada para los tamaños de lote en función de SYMBOL_VOLUME_STEP (por ejemplo, 0 para 1 y 1 para 0,1). A continuación, desarrollamos «CloseBuy» y «CloseSell» para cerrar todas las posiciones de compra o venta, recorriendo las posiciones, comprobando «Symbol» y «magicNumber», y utilizando «obj_Trade.PositionClose» hasta que «CheckMarketBuyOrders» o «CheckMarketSellOrders» devuelva 0. Por último, implementamos «GetLots» para calcular el tamaño del lote en función de «compoundPercent» (normalizando «AccountInfoDouble (ACCOUNT_BALANCE) * compoundPercent / 100 / 10000» con «fnGetLotDigit», limitado por SYMBOL_VOLUME_MIN y «SYMBOL_VOLUME_MAX») o «initialLotSize», y «AccountFreeMarginCheck» para calcular el margen disponible calculando el margen requerido con OrderCalcMargin para el tipo y volumen de orden dados, y «isTradingAllowed» como marcador de posición que devuelve «true». Para la visualización, necesitaremos funciones que permitan trazar líneas y añadir etiquetas en el gráfico.
//+------------------------------------------------------------------+
//| Draw support/resistance line                                     |
//+------------------------------------------------------------------+
void MakeLine(double price) {
   string name = "level";                         //--- Set line name
   if (ObjectFind(0, name) != -1) {               //--- Check if line exists
      ObjectMove(0, name, 0, iTime(Symbol(), PERIOD_CURRENT, 0), price); //--- Move line
      return;                                     //--- Exit function
   }
   ObjectCreate(0, name, OBJ_HLINE, 0, 0, price); //--- Create horizontal line
   ObjectSetInteger(0, name, OBJPROP_COLOR, lineColor); //--- Set color
   ObjectSetInteger(0, name, OBJPROP_STYLE, STYLE_SOLID); //--- Set style
   ObjectSetInteger(0, name, OBJPROP_WIDTH, lineWidth); //--- Set width
   ObjectSetInteger(0, name, OBJPROP_BACK, true); //--- Set to background
}

//+------------------------------------------------------------------+
//| Create dashboard label                                           |
//+------------------------------------------------------------------+
void LABEL(string labelName, string fontName, int fontSize, int xPosition, int yPosition, color textColor, int corner, string labelText) {
   if (ObjectFind(0, labelName) < 0) {            //--- Check if label exists
      ObjectCreate(0, labelName, OBJ_LABEL, 0, 0, 0); //--- Create label
   }
   ObjectSetString(0, labelName, OBJPROP_TEXT, labelText); //--- Set label text
   ObjectSetString(0, labelName, OBJPROP_FONT, fontName); //--- Set font
   ObjectSetInteger(0, labelName, OBJPROP_FONTSIZE, fontSize); //--- Set font size
   ObjectSetInteger(0, labelName, OBJPROP_COLOR, textColor); //--- Set text color
   ObjectSetInteger(0, labelName, OBJPROP_CORNER, corner); //--- Set corner
   ObjectSetInteger(0, labelName, OBJPROP_XDISTANCE, xPosition); //--- Set x position
   ObjectSetInteger(0, labelName, OBJPROP_YDISTANCE, yPosition); //--- Set y position
}
Para crear elementos visuales para el programa, desarrollamos la función «MakeLine», que dibujará una línea horizontal a un «precio» especificado para marcar un nivel de soporte o resistencia, asignándole el nombre «level», comprobando si existe con ObjectFind, moviéndola con ObjectMove al tiempo de la barra actual desde iTime si se encuentra, o creándola con ObjectCreate como OBJ_HLINE, y estableciendo «OBJPROP_COLOR» en «lineColor», OBJPROP_STYLE a «STYLE_SOLID», «OBJPROP_WIDTH» a «lineWidth» y «OBJPROP_BACK» a «true» utilizando ObjectSetInteger para su colocación en segundo plano.
A continuación, procedemos a implementar la función «LABEL», que creará o actualizará las etiquetas del panel de control comprobando si «labelName» existe; si no es así, creará un OBJ_LABEL con «ObjectCreate» y establecerá las propiedades con «ObjectSetString» para «OBJPROP_TEXT» en «labelText» y «OBJPROP_FONT» en «fontName», y mediante «ObjectSetInteger» para «OBJPROP_FONTSIZE» a «fontSize», «OBJPROP_COLOR» a «textColor», OBJPROP_CORNER a «corner», «OBJPROP_XDISTANCE» a «xPosition» y «OBJPROP_YDISTANCE» a la posición y. A continuación, podemos definir las funciones de utilidad de los indicadores que vamos a utilizar.
//+------------------------------------------------------------------+
//| Calculate ATR indicator                                          |
//+------------------------------------------------------------------+
double MyiATR(string symbol, ENUM_TIMEFRAMES timeframe, int period, int shift) {
   int handle = iATR(symbol, timeframe, period);  //--- Create ATR handle
   if (handle == INVALID_HANDLE) return 0;        //--- Check invalid handle
   double buffer[1];                              //--- Declare buffer
   if (CopyBuffer(handle, 0, shift, 1, buffer) != 1) buffer[0] = 0; //--- Copy ATR value
   IndicatorRelease(handle);                      //--- Release handle
   return buffer[0];                              //--- Return ATR value
}

//+------------------------------------------------------------------+
//| Check bullish engulfing pattern                                  |
//+------------------------------------------------------------------+
bool BullishEngulfingExists() {
   if (iOpen(Symbol(), PERIOD_CURRENT, 1) <= iClose(Symbol(), PERIOD_CURRENT, 2) && iClose(Symbol(), PERIOD_CURRENT, 1) >= iOpen(Symbol(), PERIOD_CURRENT, 2) && iOpen(Symbol(), PERIOD_CURRENT, 2) - iClose(Symbol(), PERIOD_CURRENT, 2) >= 10 * _Point && iClose(Symbol(), PERIOD_CURRENT, 1) - iOpen(Symbol(), PERIOD_CURRENT, 1) >= 10 * _Point) { //--- Check bullish engulfing conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check bullish harami pattern                                     |
//+------------------------------------------------------------------+
bool BullishHaramiExists() {
   if (iClose(Symbol(), PERIOD_CURRENT, 2) < iOpen(Symbol(), PERIOD_CURRENT, 2) && iOpen(Symbol(), PERIOD_CURRENT, 1) < iClose(Symbol(), PERIOD_CURRENT, 1) && iOpen(Symbol(), PERIOD_CURRENT, 2) - iClose(Symbol(), PERIOD_CURRENT, 2) > MyiATR(Symbol(), PERIOD_CURRENT, 14, 2) && iOpen(Symbol(), PERIOD_CURRENT, 2) - iClose(Symbol(), PERIOD_CURRENT, 2) > 4 * (iClose(Symbol(), PERIOD_CURRENT, 1) - iOpen(Symbol(), PERIOD_CURRENT, 1))) { //--- Check bullish harami conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check doji at bottom pattern                                     |
//+------------------------------------------------------------------+
bool DojiAtBottomExists() {
   if (iOpen(Symbol(), PERIOD_CURRENT, 3) - iClose(Symbol(), PERIOD_CURRENT, 3) >= 8 * _Point && MathAbs(iClose(Symbol(), PERIOD_CURRENT, 2) - iOpen(Symbol(), PERIOD_CURRENT, 2)) <= 1 * _Point && iClose(Symbol(), PERIOD_CURRENT, 1) - iOpen(Symbol(), PERIOD_CURRENT, 1) >= 8 * _Point) { //--- Check doji at bottom conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check doji at top pattern                                        |
//+------------------------------------------------------------------+
bool DojiAtTopExists() {
   if (iClose(Symbol(), PERIOD_CURRENT, 3) - iOpen(Symbol(), PERIOD_CURRENT, 3) >= 8 * _Point && MathAbs(iClose(Symbol(), PERIOD_CURRENT, 2) - iOpen(Symbol(), PERIOD_CURRENT, 2)) <= 1 * _Point && iOpen(Symbol(), PERIOD_CURRENT, 1) - iClose(Symbol(), PERIOD_CURRENT, 1) >= 8 * _Point) { //--- Check doji at top conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check bearish harami pattern                                     |
//+------------------------------------------------------------------+
bool BearishHaramiExists() {
   if (iClose(Symbol(), PERIOD_CURRENT, 2) > iClose(Symbol(), PERIOD_CURRENT, 1) && iOpen(Symbol(), PERIOD_CURRENT, 2) < iOpen(Symbol(), PERIOD_CURRENT, 1) && iClose(Symbol(), PERIOD_CURRENT, 2) > iOpen(Symbol(), PERIOD_CURRENT, 2) && iOpen(Symbol(), PERIOD_CURRENT, 1) > iClose(Symbol(), PERIOD_CURRENT, 1) && iClose(Symbol(), PERIOD_CURRENT, 2) - iOpen(Symbol(), PERIOD_CURRENT, 2) > MyiATR(Symbol(), PERIOD_CURRENT, 14, 2) && iClose(Symbol(), PERIOD_CURRENT, 2) - iOpen(Symbol(), PERIOD_CURRENT, 2) > 4 * (iOpen(Symbol(), PERIOD_CURRENT, 1) - iClose(Symbol(), PERIOD_CURRENT, 1))) { //--- Check bearish harami conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check long up candle pattern                                     |
//+------------------------------------------------------------------+
bool LongUpCandleExists() {
   if (iOpen(Symbol(), PERIOD_CURRENT, 2) < iClose(Symbol(), PERIOD_CURRENT, 2) && iHigh(Symbol(), PERIOD_CURRENT, 2) - iLow(Symbol(), PERIOD_CURRENT, 2) >= 40 * _Point && iHigh(Symbol(), PERIOD_CURRENT, 2) - iLow(Symbol(), PERIOD_CURRENT, 2) > 2.5 * MyiATR(Symbol(), PERIOD_CURRENT, 14, 2) && iClose(Symbol(), PERIOD_CURRENT, 1) < iOpen(Symbol(), PERIOD_CURRENT, 1) && iOpen(Symbol(), PERIOD_CURRENT, 1) - iClose(Symbol(), PERIOD_CURRENT, 1) > 10 * _Point) { //--- Check long up candle conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check long down candle pattern                                   |
//+------------------------------------------------------------------+
bool LongDownCandleExists() {
   if (iOpen(Symbol(), PERIOD_CURRENT, 1) > iClose(Symbol(), PERIOD_CURRENT, 1) && iHigh(Symbol(), PERIOD_CURRENT, 1) - iLow(Symbol(), PERIOD_CURRENT, 1) >= 40 * _Point && iHigh(Symbol(), PERIOD_CURRENT, 1) - iLow(Symbol(), PERIOD_CURRENT, 1) > 2.5 * MyiATR(Symbol(), PERIOD_CURRENT, 14, 1)) { //--- Check long down candle conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check bearish engulfing pattern                                  |
//+------------------------------------------------------------------+
bool BearishEngulfingExists() {
   if (iOpen(Symbol(), PERIOD_CURRENT, 1) >= iClose(Symbol(), PERIOD_CURRENT, 2) && iClose(Symbol(), PERIOD_CURRENT, 1) <= iOpen(Symbol(), PERIOD_CURRENT, 2) && iOpen(Symbol(), PERIOD_CURRENT, 2) - iClose(Symbol(), PERIOD_CURRENT, 2) >= 10 * _Point && iClose(Symbol(), PERIOD_CURRENT, 1) - iOpen(Symbol(), PERIOD_CURRENT, 1) >= 10 * _Point) { //--- Check bearish engulfing conditions
      return(true);                               //--- Return true
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Calculate average range over 4 days                              |
//+------------------------------------------------------------------+
double AveRange4() {
   double rangeSum = 0;                           //--- Initialize range sum
   int count = 0;                                 //--- Initialize count
   int index = 1;                                 //--- Initialize index
   while (count < 4) {                            //--- Loop until 4 days
      MqlDateTime dateTime;                       //--- Declare datetime structure
      TimeToStruct(iTime(Symbol(), PERIOD_CURRENT, index), dateTime); //--- Convert time
      if (dateTime.day_of_week != 0) {            //--- Check non-Sunday
         rangeSum += iHigh(Symbol(), PERIOD_CURRENT, index) - iLow(Symbol(), PERIOD_CURRENT, index); //--- Add range
         count++;                                 //--- Increment count
      }
      index++;                                    //--- Increment index
   }
   return(rangeSum / 4.0);                        //--- Return average range
}

//+------------------------------------------------------------------+
//| Check buy pinbar                                                 |
//+------------------------------------------------------------------+
bool IsBuyPinbar() {
   double currentOpen, currentClose, currentHigh, currentLow; //--- Declare current candle variables
   double previousHigh, previousLow, previousClose, previousOpen; //--- Declare previous candle variables
   double currentRange, previousRange, currentHigherPart, currentHigherPart1; //--- Declare range variables
   currentOpen = iOpen(Symbol(), PERIOD_CURRENT, 1); //--- Get current open
   currentClose = iClose(Symbol(), PERIOD_CURRENT, 1); //--- Get current close
   currentHigh = iHigh(Symbol(), PERIOD_CURRENT, 0); //--- Get current high
   currentLow = iLow(Symbol(), PERIOD_CURRENT, 1); //--- Get current low
   previousOpen = iOpen(Symbol(), PERIOD_CURRENT, 2); //--- Get previous open
   previousClose = iClose(Symbol(), PERIOD_CURRENT, 2); //--- Get previous close
   previousHigh = iHigh(Symbol(), PERIOD_CURRENT, 2); //--- Get previous high
   previousLow = iLow(Symbol(), PERIOD_CURRENT, 2); //--- Get previous low
   currentRange = currentHigh - currentLow;       //--- Calculate current range
   previousRange = previousHigh - previousLow;    //--- Calculate previous range
   currentHigherPart = currentHigh - currentRange * 0.4; //--- Calculate higher part
   currentHigherPart1 = currentHigh - currentRange * 0.4; //--- Calculate higher part
   double averageDailyRange = AveRange4();        //--- Get average daily range
   if ((currentClose > currentHigherPart1 && currentOpen > currentHigherPart) && //--- Check close/open in higher third
       (currentRange > averageDailyRange * 0.5) && //--- Check pinbar size
       (currentLow + currentRange * 0.25 < previousLow)) { //--- Check nose length
      double lowArray[3];                         //--- Declare low array
      CopyLow(Symbol(), PERIOD_CURRENT, 3, 3, lowArray); //--- Copy low prices
      int minIndex = ArrayMinimum(lowArray);      //--- Find minimum low index
      if (lowArray[minIndex] > currentLow) return(true); //--- Confirm buy pinbar
   }
   return(false);                                 //--- Return false
}

//+------------------------------------------------------------------+
//| Check sell pinbar                                                |
//+------------------------------------------------------------------+
bool IsSellPinbar() {
   double currentOpen, currentClose, currentHigh, currentLow; //--- Declare current candle variables
   double previousHigh, previousLow, previousClose, previousOpen; //--- Declare previous candle variables
   double currentRange, previousRange, currentLowerPart, currentLowerPart1; //--- Declare range variables
   currentOpen = iOpen(Symbol(), PERIOD_CURRENT, 1); //--- Get current open
   currentClose = iClose(Symbol(), PERIOD_CURRENT, 1); //--- Get current close
   currentHigh = iHigh(Symbol(), PERIOD_CURRENT, 1); //--- Get current high
   currentLow = iLow(Symbol(), PERIOD_CURRENT, 1); //--- Get current low
   previousOpen = iOpen(Symbol(), PERIOD_CURRENT, 2); //--- Get previous open
   previousClose = iClose(Symbol(), PERIOD_CURRENT, 2); //--- Get previous close
   previousHigh = iHigh(Symbol(), PERIOD_CURRENT, 2); //--- Get previous high
   previousLow = iLow(Symbol(), PERIOD_CURRENT, 2); //--- Get previous low
   currentRange = currentHigh - currentLow;       //--- Calculate current range
   previousRange = previousHigh - previousLow;    //--- Calculate previous range
   currentLowerPart = currentLow + currentRange * 0.4; //--- Calculate lower part
   currentLowerPart1 = currentLow + currentRange * 0.4; //--- Calculate lower part
   double averageDailyRange = AveRange4();        //--- Get average daily range
   if ((currentClose < currentLowerPart1 && currentOpen < currentLowerPart) && //--- Check close/open in lower third
       (currentRange > averageDailyRange * 0.5) && //--- Check pinbar size
       (currentHigh - currentRange * 0.25 > previousHigh)) { //--- Check nose length
      double highArray[3];                        //--- Declare high array
      CopyHigh(Symbol(), PERIOD_CURRENT, 3, 3, highArray); //--- Copy high prices
      int maxIndex = ArrayMaximum(highArray);     //--- Find maximum high index
      if (highArray[maxIndex] < currentHigh) return(true); //--- Confirm sell pinbar
   }
   return(false);                                 //--- Return false
}
Aquí implementamos funciones para detectar patrones de velas japonesas y calcular el rango verdadero medio (ATR) para nuestro sistema. En primer lugar, creamos la función «MyiATR», que calcula el ATR creando un identificador con la función iATR para el símbolo, el marco temporal y el período indicados; devuelve 0 si el identificador no es válido; copia el valor del ATR en un búfer con CopyBuffer; libera el identificador con IndicatorRelease; y devuelve el valor del ATR.
A continuación, procedemos a implementar las funciones de detección de patrones de velas: «BullishEngulfingExists» comprueba si la vela actual envuelve a la vela bajista anterior con cuerpos de tamaño significativo; «BullishHaramiExists» identifica una pequeña vela alcista dentro de una vela bajista más grande utilizando «MyiATR» para comparar el tamaño; «DojiAtBottomExists» detecta un doji entre una vela bajista y una alcista para un patrón de estrella matutina; «DojiAtTopExists» identifica un doji entre una vela alcista y una bajista para un patrón de estrella vespertina; «BearishHaramiExists» comprueba si hay una pequeña vela bajista dentro de una vela alcista más grande; «LongUpCandleExists» confirma una vela alcista fuerte seguida de una bajista utilizando el ATR; «LongDownCandleExists» detecta una vela bajista fuerte; y «BearishEngulfingExists» verifica que una vela bajista envuelve a una alcista.
Por último, implementamos «IsBuyPinbar» e «IsSellPinbar», que identifican las barras pin comprobando si el cierre y la apertura de la vela actual se encuentran en el tercio superior o inferior de su rango, si el rango supera la mitad del rango medio diario de «AveRange4» (que calcula la media del rango entre el máximo y el mínimo de cuatro días, excluyendo los domingos), y la «nariz» de la barra pin se extiende más allá del mínimo o máximo de la vela anterior, lo cual se confirma comparando los mínimos o máximos recientes con CopyLow o CopyHigh y las funciones «ArrayMinimum» o ArrayMaximum. A continuación, podemos definir algunas funciones para obtener el tipo de señal con fines de visualización y el precio ponderado para la gestión de posiciones.
//+------------------------------------------------------------------+
//| Analyze candlestick patterns                                     |
//+------------------------------------------------------------------+
string CandleStick_Analyzer() {
   string candlePattern, comment1 = "", comment2 = "", comment3 = ""; //--- Initialize pattern strings
   string comment4 = "", comment5 = "", comment6 = "", comment7 = ""; //--- Initialize pattern strings
   string comment8 = "", comment9 = "";                               //--- Initialize pattern strings
   if (BullishEngulfingExists()) comment1 = " Bullish Engulfing ";    //--- Check bullish engulfing
   if (BullishHaramiExists()) comment2 = " Bullish Harami ";          //--- Check bullish harami
   if (LongUpCandleExists()) comment3 = " Bullish LongUp ";           //--- Check long up candle
   if (DojiAtBottomExists()) comment4 = " MorningStar Doji ";         //--- Check morning star doji
   if (DojiAtTopExists()) comment5 = " EveningStar Doji ";            //--- Check evening star doji
   if (BearishHaramiExists()) comment6 = " Bearish Harami ";          //--- Check bearish harami
   if (BearishEngulfingExists()) comment7 = " Bearish Engulfing ";    //--- Check bearish engulfing
   if (LongDownCandleExists()) comment8 = " Bearish LongDown ";       //--- Check long down candle
   candlePattern = comment1 + comment2 + comment3 + comment4 + comment5 + comment6 + comment7 + comment8 + comment9; //--- Combine patterns
   return(candlePattern);                                             //--- Return combined pattern
}

//+------------------------------------------------------------------+
//| Calculate average price for order type                           |
//+------------------------------------------------------------------+
double rata_price(int orderType) {
   double totalVolume = 0;                        //--- Initialize total volume
   double weightedOpenSum = 0;                    //--- Initialize weighted open sum
   double averagePrice = 0;                       //--- Initialize average price
   for (int positionIndex = 0; positionIndex < PositionsTotal(); positionIndex++) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(positionIndex); //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber && (PositionGetInteger(POSITION_TYPE) == orderType)) { //--- Check position match
         totalVolume += PositionGetDouble(POSITION_VOLUME); //--- Add volume
         weightedOpenSum += (PositionGetDouble(POSITION_VOLUME) * PositionGetDouble(POSITION_PRICE_OPEN)); //--- Add weighted open
      }
   }
   if (totalVolume != 0) {                        //--- Check non-zero volume
      averagePrice = weightedOpenSum / totalVolume; //--- Calculate average price
   }
   return(averagePrice);                          //--- Return average price
}
Para mejorar la gestión de posiciones, creamos la función «CandleStick_Analyzer», que inicializa variables de cadena como «comment1» a «comment9» como vacías, comprueba si existen patrones de velas japonesas utilizando funciones como «BullishEngulfingExists» —que ya hemos definido—, asigna cadenas descriptivas (por ejemplo, «Bullish Engulfing») a las variables correspondientes si se detectan patrones, y las concatena en «candlePattern» para devolver una cadena combinada de los patrones detectados que se mostrará en el panel de control.
A continuación, procedemos a implementar la función «rata_price», que calcula el precio medio ponderado para un «orderType» específico (compra o venta) inicializando «totalVolume» y «weightedOpenSum» a 0, iterando a través de «PositionsTotal» para sumar POSITION_VOLUME y el producto de «POSITION_VOLUME» y POSITION_PRICE_OPEN para las posiciones que coincidan con «Symbol», «magicNumber» y «orderType» utilizando «PositionGetTicket», PositionGetString y «PositionGetInteger», y calculando «averagePrice» como «weightedOpenSum / totalVolume» si «totalVolume» es distinto de cero, devolviendo el resultado, lo que proporciona un análisis de patrones críticos para señales de negociación y cálculos precisos del precio medio para ajustes de promedios y de toma de beneficios. En cuanto a las posiciones, primero tendremos que recabar sus datos. Definamos una lógica para ello.
//+------------------------------------------------------------------+
//| Calculate position metrics                                       |
//+------------------------------------------------------------------+
void calculatePositionMetrics() {
   buyCount = 0;                                  //--- Reset buy count
   currentBuyLot = 0;                             //--- Reset current buy lot
   totalBuyLots = 0;                              //--- Reset total buy lots
   sellCount = 0;                                 //--- Reset sell count
   currentSellLot = 0;                            //--- Reset current sell lot
   totalSellLots = 0;                             //--- Reset total sell lots
   totalSum = 0;                                  //--- Reset total sum
   totalSwap = 0;                                 //--- Reset total swap
   buyProfit = 0;                                 //--- Reset buy profit
   sellProfit = 0;                                //--- Reset sell profit
   buyWeightedSum = 0;                            //--- Reset buy weighted sum
   sellWeightedSum = 0;                           //--- Reset sell weighted sum
   buyBreakEvenPrice = 0;                         //--- Reset buy breakeven price
   sellBreakEvenPrice = 0;                        //--- Reset sell breakeven price
   minBuyLot = 9999;                              //--- Initialize min buy lot
   minSellLot = 9999;                             //--- Initialize min sell lot
   maxSellPrice = 0;                              //--- Initialize max sell price
   minBuyPrice = 999999999;                       //--- Initialize min buy price
   for (int i = 0; i < PositionsTotal(); i++) {   //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);        //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) != Symbol()) continue; //--- Skip non-matching symbols
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
         buyCount++;                              //--- Increment buy count
         totalOperations++;                       //--- Increment total operations
         currentBuyLot = PositionGetDouble(POSITION_VOLUME); //--- Set current buy lot
         buyProfit += PositionGetDouble(POSITION_PROFIT); //--- Add buy profit
         totalBuyLots += PositionGetDouble(POSITION_VOLUME); //--- Add to total buy lots
         minBuyLot = MathMin(minBuyLot, PositionGetDouble(POSITION_VOLUME)); //--- Update min buy lot
         buyWeightedSum += PositionGetDouble(POSITION_VOLUME) * PositionGetDouble(POSITION_PRICE_OPEN); //--- Add weighted open price
         minBuyPrice = MathMin(minBuyPrice, PositionGetDouble(POSITION_PRICE_OPEN)); //--- Update min buy price
      }
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
         sellCount++;                             //--- Increment sell count
         totalOperations++;                       //--- Increment total operations
         currentSellLot = PositionGetDouble(POSITION_VOLUME); //--- Set current sell lot
         sellProfit += PositionGetDouble(POSITION_PROFIT); //--- Add sell profit
         totalSellLots += PositionGetDouble(POSITION_VOLUME); //--- Add to total sell lots
         minSellLot = MathMin(minSellLot, PositionGetDouble(POSITION_VOLUME)); //--- Update min sell lot
         sellWeightedSum += PositionGetDouble(POSITION_VOLUME) * PositionGetDouble(POSITION_PRICE_OPEN); //--- Add weighted open price
         maxSellPrice = MathMax(maxSellPrice, PositionGetDouble(POSITION_PRICE_OPEN)); //--- Update max sell price
      }
   }
   if (totalBuyLots > 0) {                        //--- Check buy lots
      buyBreakEvenPrice = buyWeightedSum / totalBuyLots; //--- Calculate buy breakeven
   }
   if (totalSellLots > 0) {                       //--- Check sell lots
      sellBreakEvenPrice = sellWeightedSum / totalSellLots; //--- Calculate sell breakeven
   }
}
Para calcular las métricas esenciales para gestionar eficazmente múltiples posiciones, implementamos la función "calculatePositionMetrics". En primer lugar, restablecemos las variables clave a cero o a su valor inicial respectivo para un seguimiento preciso. A continuación, procedemos a recorrer todas las posiciones utilizando PositionsTotal, recuperando el ticket de cada posición con PositionGetTicket, omitiendo los tickets no válidos o los símbolos que no coinciden con PositionGetString, y, en el caso de las posiciones de compra (POSITION_TYPE_BUY), incrementando «buyCount» y «totalOperations», estableciendo «currentBuyLot», sumando «POSITION_PROFIT» a «buyProfit» y «POSITION_VOLUME» a «totalBuyLots», actualizando «minBuyLot» con MathMin, sumando el precio de apertura ponderado a «buyWeightedSum» y actualizando «minBuyPrice»; para las posiciones de venta (POSITION_TYPE_SELL), realizamos actualizaciones similares para las métricas de venta. Por último, calculamos el «buyBreakEvenPrice» como «buyWeightedSum / totalBuyLots» si «totalBuyLots» es positivo, y el «sellBreakEvenPrice» como «sellWeightedSum / totalSellLots» si «totalSellLots» es positivo, lo que proporciona precios medios ponderados para ajustes al punto de equilibrio y garantiza un seguimiento preciso de los parámetros de la posición a efectos de promediado y control de riesgos. Con estas funciones, ya estamos listos para comenzar con la lógica de apertura de posiciones. Lo haremos en el controlador de eventos OnTick.
//+------------------------------------------------------------------+
//| Expert tick function                                             |
//+------------------------------------------------------------------+
void OnTick() {
   static datetime previousBarTime = 0;           //--- Store previous bar time
   if (previousBarTime != iTime(Symbol(), PERIOD_CURRENT, 0)) { //--- Check new bar
      previousBarTime = iTime(Symbol(), PERIOD_CURRENT, 0); //--- Update previous bar time
      ChartRedraw(0);                             //--- Redraw chart
   } else {
      return;                                     //--- Exit if not new bar
   }
   if (iVolume(Symbol(), PERIOD_H4, 0) > iVolume(Symbol(), PERIOD_H4, 1)) return; //--- Exit if volume increased
   double supportResistanceLevel = NormalizeDouble(iClose(Symbol(), PERIOD_H4, 1), _Digits); //--- Get support/resistance level
   ObjectDelete(0, "level");                      //--- Delete existing level line
   MakeLine(supportResistanceLevel);              //--- Draw support/resistance line
   if (SymbolInfoInteger(Symbol(), SYMBOL_SPREAD) > 150) return; //--- Exit if spread too high
   int totalBuyPositions = 0;                     //--- Initialize buy positions count
   int totalSellPositions = 0;                    //--- Initialize sell positions count
   for (int i = 0; i < PositionsTotal(); i++) {   //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);        //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) != Symbol() || PositionGetInteger(POSITION_MAGIC) != magicNumber) continue; //--- Skip non-matching positions
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
         totalBuyPositions++;                     //--- Increment buy count
      }
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
         totalSellPositions++;                    //--- Increment sell count
      }
   }
}
En el controlador de eventos OnTick, implementamos la lógica inicial del sistema de promedios de barras pin para gestionar las decisiones de negociación y las actualizaciones visuales en cada nueva barra. En primer lugar, comprobamos si hay una nueva barra comparando «previousBarTime» (estática, inicializada en 0) con la hora de la barra actual obtenida de iTime para el símbolo y el período actuales en el turno 0; si se detecta una nueva barra, actualizamos «previousBarTime» y llamamos a ChartRedraw, y si no, salimos.
A continuación, procedemos a salimos de la función si el volumen de la barra H4 actual, según iVolume, supera el de la barra anterior, evitando así los periodos de alta volatilidad. A continuación, calculamos el nivel de soporte/resistencia como el precio de cierre normalizado de la barra H4 anterior utilizando iClose y NormalizeDouble, eliminamos cualquier línea de «nivel» existente con ObjectDelete y trazamos una nueva línea horizontal con «MakeLine» en este nivel. Por último, comprobamos si el spread de SymbolInfoInteger supera los 150 puntos; si es demasiado alto, salimos y contamos las posiciones abiertas iterando a través de PositionsTotal, utilizando «PositionGetTicket» para obtener los tickets, omitiendo las posiciones con símbolos o «magicNumber» no válidos o que no coincidan, e incrementando «totalBuyPositions» o «totalSellPositions» para las posiciones de compra o venta identificadas con la función PositionGetInteger. Esta configuración inicial garantiza que el EA procese operaciones únicamente en nuevas barras con condiciones favorables y mantenga una referencia visual actualizada. Tras la compilación, obtenemos el siguiente resultado.
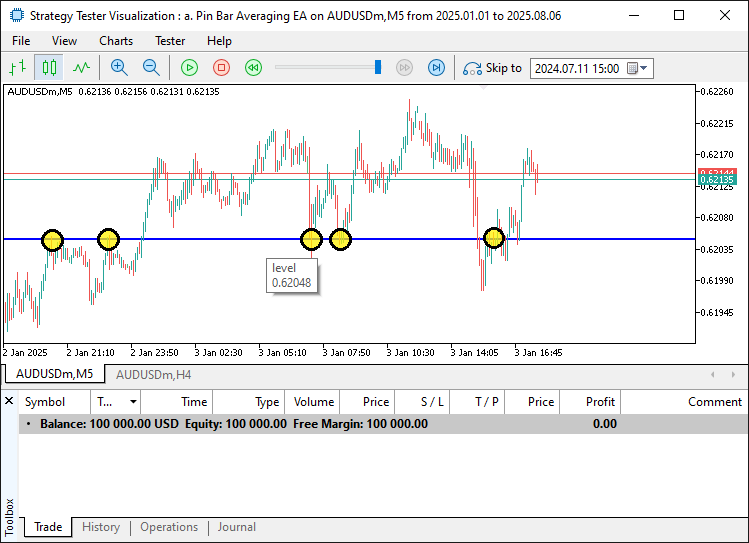
En la imagen podemos observar que marcamos los niveles de soporte y resistencia en el gráfico de forma dinámica. Ahora debemos pasar a agregar las posiciones de forma dinámica.
if (CheckMarketBuyOrders() < 70 && CheckMarketSellOrders() < 70) { //--- Check order limits
   if (supportResistanceLevel > iOpen(Symbol(), PERIOD_CURRENT, 0) && useSignalMode == DISABLED) { //--- Check buy condition
      if (IsBuyPinbar() && totalBuyPositions < maxOrders && (isTradingAllowed() || totalBuyPositions > 0)) { //--- Check buy pinbar and limits
         double buyStopLoss = NormalizeDouble(SymbolInfoDouble(_Symbol, SYMBOL_ASK) - stopLossPips * normalizedPoint, _Digits); //--- Calculate buy stop loss
         double buyTakeProfit = NormalizeDouble(SymbolInfoDouble(_Symbol, SYMBOL_ASK) + takeProfitPips * normalizedPoint, _Digits); //--- Calculate buy take profit
         if (AccountFreeMarginCheck(Symbol(), ORDER_TYPE_BUY, GetLots()) > 0) { //--- Check margin
            obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_BUY, GetLots(), SymbolInfoDouble(_Symbol, SYMBOL_ASK), buyStopLoss, buyTakeProfit, orderComment); //--- Open buy position
            if (useAutoTakeProfit) {             //--- Check auto take profit
               ModifyTP(ORDER_TYPE_BUY, rata_price(ORDER_TYPE_BUY) + takeProfitPips * normalizedPoint); //--- Modify take profit
            }
            CloseSell();                         //--- Close sell positions
         }
      }
   }
   if (supportResistanceLevel < iOpen(Symbol(), PERIOD_CURRENT, 0) && useSignalMode == DISABLED) { //--- Check sell condition
      if (IsSellPinbar() && totalSellPositions < maxOrders && (isTradingAllowed() || totalSellPositions > 0)) { //--- Check sell pinbar and limits
         double sellStopLoss = NormalizeDouble(SymbolInfoDouble(_Symbol, SYMBOL_BID) + stopLossPips * normalizedPoint, _Digits); //--- Calculate sell stop loss
         double sellTakeProfit = NormalizeDouble(SymbolInfoDouble(_Symbol, SYMBOL_BID) - takeProfitPips * normalizedPoint, _Digits); //--- Calculate sell take profit
         if (AccountFreeMarginCheck(Symbol(), ORDER_TYPE_SELL, GetLots()) > 0) { //--- Check margin
            obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_SELL, GetLots(), SymbolInfoDouble(_Symbol, SYMBOL_BID), sellStopLoss, sellTakeProfit, orderComment); //--- Open sell position
            if (useAutoTakeProfit) {             //--- Check auto take profit
               ModifyTP(ORDER_TYPE_SELL, rata_price(ORDER_TYPE_SELL) - takeProfitPips * normalizedPoint); //--- Modify take profit
            }
            CloseBuy();                          //--- Close buy positions
         }
      }
   }
}
if (CountTrades() == 0) {                       //--- Check no trades
   if (supportResistanceLevel > iOpen(Symbol(), PERIOD_CURRENT, 0) && useSignalMode == ENABLED) { //--- Check buy signal mode
      if (IsBuyPinbar() && CountTrades() < maxOrders) { //--- Check buy pinbar and limit
         obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_BUY, GetLots(), SymbolInfoDouble(_Symbol, SYMBOL_ASK), SymbolInfoDouble(_Symbol, SYMBOL_ASK) - stopLossPips * normalizedPoint, SymbolInfoDouble(_Symbol, SYMBOL_ASK) + (takeProfitPips * normalizedPoint), orderComment); //--- Open buy position
      }
   }
}
if (CountTrades() == 0) {                       //--- Check no trades
   if (supportResistanceLevel < iOpen(Symbol(), PERIOD_CURRENT, 0) && useSignalMode == ENABLED) { //--- Check sell signal mode
      if (IsSellPinbar() && CountTrades() < maxOrders) { //--- Check sell pinbar and limit
         obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_SELL, GetLots(), SymbolInfoDouble(_Symbol, SYMBOL_BID), SymbolInfoDouble(_Symbol, SYMBOL_BID) + stopLossPips * normalizedPoint, SymbolInfoDouble(_Symbol, SYMBOL_BID) - (takeProfitPips * normalizedPoint), orderComment); //--- Open sell position
      }
   }
}
Continuamos con la implementación de la función de ticks, añadiendo lógica para abrir nuevas posiciones en función de las señales de las velas pin bar y las condiciones del mercado. En primer lugar, comprobamos si las órdenes de compra y venta abiertas son inferiores a 70 mediante "CheckMarketBuyOrders" y "CheckMarketSellOrders", garantizando así que el EA no supere los límites prácticos. A continuación, si «useSignalMode» está en «DISABLED», evaluamos las condiciones de compra: cuando «supportResistanceLevel» supera el precio de apertura actual de iOpen, se detecta una barra pin de compra con «IsBuyPinbar», «totalBuyPositions» es inferior a «maxOrders», y se permite operar mediante «isTradingAllowed» o existen órdenes de compra preexistentes, calculamos «buyStopLoss» y «buyTakeProfit» utilizando SymbolInfoDouble con «stopLossPips» y «takeProfitPips» ajustados por «normalizedPoint», verificamos el margen con «AccountFreeMarginCheck» y abrimos una posición de compra con «obj_Trade.
«PositionOpen» utilizando «GetLots»; modifica el take profit con «ModifyTP» si «useAutoTakeProfit» es verdadero, y cierra las posiciones de venta con «CloseSell»; se aplica una lógica similar para las condiciones de venta cuando «supportResistanceLevel» está por debajo del precio de apertura, utilizando «IsSellPinbar». A continuación, si no hay operaciones abiertas («CountTrades» es 0) y «useSignalMode» está en «ENABLED», abrimos una posición de compra en una barra pin de compra con «IsBuyPinbar» y «CountTrades» por debajo de «maxOrders», utilizando «obj_Trade. PositionOpen» con el stop loss y el take profit calculados, y de forma similar para las posiciones de venta con «IsSellPinbar», asegurándonos de que el EA abra posiciones basadas en señales de pin bar en niveles clave con una gestión de riesgos adecuada. Tras la compilación, obtenemos el siguiente resultado.
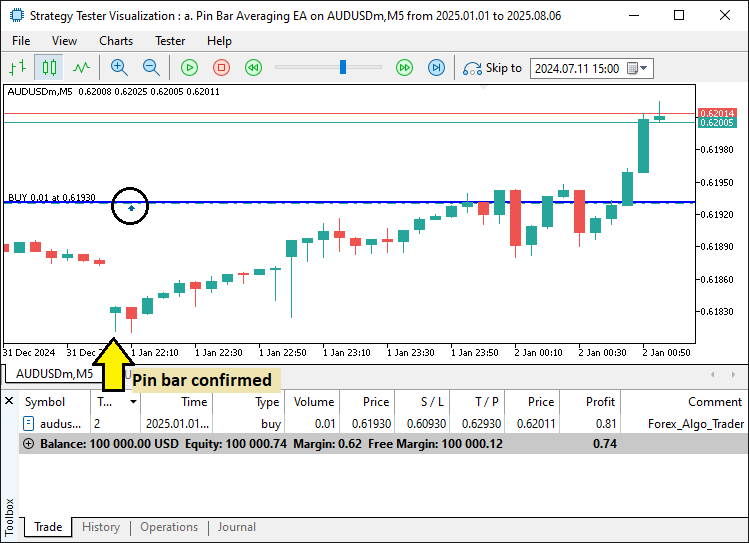
Dado que ahora confirmamos las señales y abrimos posiciones, tenemos que gestionar las señales. Lo que vamos a hacer es definir algunas funciones para ello.
//+------------------------------------------------------------------+
//| Update stop loss and take profit                                 |
//+------------------------------------------------------------------+
void updateStopLossTakeProfit() {
   for (int i = PositionsTotal() - 1; i >= 0; i--) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);           //--- Get position ticket
      if (ticket == 0) continue;                     //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) != Symbol()) continue; //--- Skip non-matching symbols
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
         double buyTakeProfitLevel = (buyBreakEvenPrice + takeProfitPips * _Point) * (takeProfitPips > 0); //--- Calculate buy take profit
         double buyStopLossLevel = PositionGetDouble(POSITION_SL); //--- Get current stop loss
         if (slBreakevenMinus > 0) {                 //--- Check breakeven adjustment
            buyStopLossLevel = (buyBreakEvenPrice - slBreakevenMinus * _Point); //--- Set breakeven stop loss
         }
         if (buyCount == 1) {                        //--- Check single buy position
            buyTakeProfitLevel = NormalizePrice(PositionGetDouble(POSITION_PRICE_OPEN) + takeProfitPips * _Point) * (takeProfitPips > 0); //--- Set take profit
            if (laterUseSL > 0) {                    //--- Check unused stop loss
               buyStopLossLevel = (PositionGetDouble(POSITION_PRICE_OPEN) - laterUseSL * _Point); //--- Set stop loss
            }
         }
         buyTakeProfitLevel = NormalizePrice(buyTakeProfitLevel); //--- Normalize take profit
         buyStopLossLevel = NormalizePrice(buyStopLossLevel); //--- Normalize stop loss
         if (SymbolInfoDouble(_Symbol, SYMBOL_BID) >= buyTakeProfitLevel && buyTakeProfitLevel > 0) { //--- Check take profit hit
            obj_Trade.PositionClose(ticket);         //--- Close position
         }
         if (SymbolInfoDouble(_Symbol, SYMBOL_BID) <= buyStopLossLevel) { //--- Check stop loss hit
            obj_Trade.PositionClose(ticket);         //--- Close position
         }
         if (NormalizePrice(PositionGetDouble(POSITION_TP)) != buyTakeProfitLevel || NormalizePrice(PositionGetDouble(POSITION_SL)) != buyStopLossLevel) { //--- Check modification needed
            obj_Trade.PositionModify(ticket, buyStopLossLevel, buyTakeProfitLevel); //--- Modify position
         }
      }
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
         double sellTakeProfitLevel = (sellBreakEvenPrice - takeProfitPips * _Point) * (takeProfitPips > 0); //--- Calculate sell take profit
         double sellStopLossLevel = PositionGetDouble(POSITION_SL); //--- Get current stop loss
         if (slBreakevenMinus > 0) {                //--- Check breakeven adjustment
            sellStopLossLevel = (sellBreakEvenPrice + slBreakevenMinus * _Point); //--- Set breakeven stop loss
         }
         if (sellCount == 1) {                      //--- Check single sell position
            sellTakeProfitLevel = (PositionGetDouble(POSITION_PRICE_OPEN) - takeProfitPips * _Point) * (takeProfitPips > 0); //--- Set take profit
            if (laterUseSL > 0) {                   //--- Check unused stop loss
               sellStopLossLevel = (PositionGetDouble(POSITION_PRICE_OPEN) + laterUseSL * _Point); //--- Set stop loss
            }
         }
         sellTakeProfitLevel = NormalizePrice(sellTakeProfitLevel); //--- Normalize take profit
         sellStopLossLevel = NormalizePrice(sellStopLossLevel); //--- Normalize stop loss
         if (SymbolInfoDouble(_Symbol, SYMBOL_ASK) <= sellTakeProfitLevel) { //--- Check take profit hit
            obj_Trade.PositionClose(ticket);        //--- Close position
         }
         if (SymbolInfoDouble(_Symbol, SYMBOL_ASK) >= sellStopLossLevel && sellStopLossLevel > 0) { //--- Check stop loss hit
            obj_Trade.PositionClose(ticket);        //--- Close position
         }
         if (NormalizePrice(PositionGetDouble(POSITION_TP)) != sellTakeProfitLevel || NormalizePrice(PositionGetDouble(POSITION_SL)) != sellStopLossLevel) { //--- Check modification needed
            obj_Trade.PositionModify(ticket, sellStopLossLevel, sellTakeProfitLevel); //--- Modify position
         }
      }
   }
}

//+------------------------------------------------------------------+
//| Add averaging order                                              |
//+------------------------------------------------------------------+
void addAveragingOrder() {
   int positionIndex = 0;                         //--- Initialize position index
   double lastOpenPrice = 0;                      //--- Initialize last open price
   double lastLotSize = 0;                        //--- Initialize last lot size
   bool isLastBuy = false;                        //--- Initialize buy flag
   int totalBuyPositions = 0;                     //--- Initialize buy positions count
   int totalSellPositions = 0;                    //--- Initialize sell positions count
   long currentSpread = SymbolInfoInteger(Symbol(), SYMBOL_SPREAD); //--- Get current spread
   double supportResistanceLevel = iClose(Symbol(), PERIOD_H4, 1); //--- Get support/resistance level
   for (positionIndex = 0; positionIndex < PositionsTotal(); positionIndex++) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(positionIndex); //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY && PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check buy position
         if (lastOpenPrice == 0) {                //--- Check initial price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Set initial price
         }
         if (lastOpenPrice > PositionGetDouble(POSITION_PRICE_OPEN)) { //--- Check lower price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Update last price
         }
         if (lastLotSize < PositionGetDouble(POSITION_VOLUME)) { //--- Check larger lot
            lastLotSize = PositionGetDouble(POSITION_VOLUME); //--- Update lot size
         }
         isLastBuy = true;                        //--- Set buy flag
         totalBuyPositions++;                     //--- Increment buy count
      }
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL && PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check sell position
         if (lastOpenPrice == 0) {                //--- Check initial price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Set initial price
         }
         if (lastOpenPrice < PositionGetDouble(POSITION_PRICE_OPEN)) { //--- Check higher price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Update last price
         }
         if (lastLotSize < PositionGetDouble(POSITION_VOLUME)) { //--- Check larger lot
            lastLotSize = PositionGetDouble(POSITION_VOLUME); //--- Update lot size
         }
         isLastBuy = false;                       //--- Clear buy flag
         totalSellPositions++;                    //--- Increment sell count
      }
   }
   if (isLastBuy) {                               //--- Check buy position
      if (supportResistanceLevel > iOpen(Symbol(), PERIOD_CURRENT, 0)) { //--- Check buy condition
         if (IsBuyPinbar() && SymbolInfoDouble(_Symbol, SYMBOL_BID) <= lastOpenPrice - (orderDistancePips * _Point)) { //--- Check buy pinbar and distance
            obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_BUY, NormalizeDouble((lastLotSize * lotMultiplier), fnGetLotDigit()), SymbolInfoDouble(_Symbol, SYMBOL_ASK), SymbolInfoDouble(_Symbol, SYMBOL_ASK) - stopLossPips * normalizedPoint, SymbolInfoDouble(_Symbol, SYMBOL_ASK) + (takeProfitPips * normalizedPoint), orderComment); //--- Open buy position
            isLastBuy = false;                    //--- Clear buy flag
            return;                               //--- Exit function
         }
      }
   } else if (!isLastBuy) {                       //--- Check sell position
      if (supportResistanceLevel < iOpen(Symbol(), PERIOD_CURRENT, 0)) { //--- Check sell condition
         if (IsSellPinbar() && SymbolInfoDouble(_Symbol, SYMBOL_ASK) >= lastOpenPrice + (orderDistancePips * _Point)) { //--- Check sell pinbar and distance
            obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_SELL, NormalizeDouble((lastLotSize * lotMultiplier), fnGetLotDigit()), SymbolInfoDouble(_Symbol, SYMBOL_BID), SymbolInfoDouble(_Symbol, SYMBOL_BID) + stopLossPips * normalizedPoint, SymbolInfoDouble(_Symbol, SYMBOL_BID) - (takeProfitPips * normalizedPoint), orderComment); //--- Open sell position
            return;                               //--- Exit function
         }
      }
   }
}

//+------------------------------------------------------------------+
//| Add averaging order with auto take profit                        |
//+------------------------------------------------------------------+
void addAveragingOrderWithAutoTP() {
   int positionIndex = 0;                         //--- Initialize position index
   double lastOpenPrice = 0;                      //--- Initialize last open price
   double lastLotSize = 0;                        //--- Initialize last lot size
   bool isLastBuy = false;                        //--- Initialize buy flag
   int totalBuyPositions = 0;                     //--- Initialize buy positions count
   int totalSellPositions = 0;                    //--- Initialize sell positions count
   long currentSpread = SymbolInfoInteger(Symbol(), SYMBOL_SPREAD); //--- Get current spread
   double supportResistanceLevel = iClose(Symbol(), PERIOD_H4, 1); //--- Get support/resistance level
   for (positionIndex = 0; positionIndex < PositionsTotal(); positionIndex++) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(positionIndex); //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY && PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check buy position
         if (lastOpenPrice == 0) {                //--- Check initial price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Set initial price
         }
         if (lastOpenPrice > PositionGetDouble(POSITION_PRICE_OPEN)) { //--- Check lower price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Update last price
         }
         if (lastLotSize < PositionGetDouble(POSITION_VOLUME)) { //--- Check larger lot
            lastLotSize = PositionGetDouble(POSITION_VOLUME); //--- Update lot size
         }
         isLastBuy = true;                        //--- Set buy flag
         totalBuyPositions++;                     //--- Increment buy count
      }
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL && PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check sell position
         if (lastOpenPrice == 0) {                //--- Check initial price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Set initial price
         }
         if (lastOpenPrice < PositionGetDouble(POSITION_PRICE_OPEN)) { //--- Check higher price
            lastOpenPrice = PositionGetDouble(POSITION_PRICE_OPEN); //--- Update last price
         }
         if (lastLotSize < PositionGetDouble(POSITION_VOLUME)) { //--- Check larger lot
            lastLotSize = PositionGetDouble(POSITION_VOLUME); //--- Update lot size
         }
         isLastBuy = false;                       //--- Clear buy flag
         totalSellPositions++;                    //--- Increment sell count
      }
   }
   if (isLastBuy) {                               //--- Check buy position
      if (supportResistanceLevel > iOpen(Symbol(), PERIOD_CURRENT, 0)) { //--- Check buy condition
         if (IsBuyPinbar() && SymbolInfoDouble(_Symbol, SYMBOL_BID) <= lastOpenPrice - (orderDistancePips * _Point)) { //--- Check buy pinbar and distance
            obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_BUY, NormalizeDouble((lastLotSize * lotMultiplier), fnGetLotDigit()), SymbolInfoDouble(_Symbol, SYMBOL_ASK), 0, 0, orderComment); //--- Open buy position
            calculatePositionMetrics();           //--- Calculate position metrics
            updateStopLossTakeProfit();           //--- Update stop loss and take profit
            isLastBuy = false;                    //--- Clear buy flag
            return;                               //--- Exit function
         }
      }
   } else if (!isLastBuy) {                       //--- Check sell position
      if (supportResistanceLevel < iOpen(Symbol(), PERIOD_CURRENT, 0)) { //--- Check sell condition
         if (IsSellPinbar() && SymbolInfoDouble(_Symbol, SYMBOL_ASK) >= lastOpenPrice + (orderDistancePips * _Point)) { //--- Check sell pinbar and distance
            obj_Trade.PositionOpen(Symbol(), ORDER_TYPE_SELL, NormalizeDouble((lastLotSize * lotMultiplier), fnGetLotDigit()), SymbolInfoDouble(_Symbol, SYMBOL_BID), 0, 0, orderComment); //--- Open sell position
            calculatePositionMetrics();           //--- Calculate position metrics
            updateStopLossTakeProfit();           //--- Update stop loss and take profit
            return;                               //--- Exit function
         }
      }
   }
}
Aquí implementamos las funciones «updateStopLossTakeProfit» y «addAveragingOrder», junto con «addAveragingOrderWithAutoTP», para gestionar el stop loss, el take profit y las operaciones de promediado, garantizando así ajustes dinámicos de las posiciones. En primer lugar, desarrollamos la función «updateStopLossTakeProfit», que recorre todas las posiciones. Para las posiciones de compra (POSITION_TYPE_BUY), calculamos «buyTakeProfitLevel» basándonos en «buyBreakEvenPrice» más «takeProfitPips * _Point» si «takeProfitPips» es positivo; obtenemos el stop loss actual con PositionGetDouble y lo ajustamos a «buyBreakEvenPrice - slBreakevenMinus * _Point» si «slBreakevenMinus» es positivo; o, para posiciones únicas («buyCount == 1»), se establecen el take profit y el stop loss basándose en POSITION_PRICE_OPEN, ajustados según el take profit y el stop loss; se normalizan ambos niveles con «NormalizePrice»; se cierran las posiciones con «obj_Trade. PositionClose» si el precio bid supera el take profit o el stop loss, y modifica las posiciones con «obj_Trade.PositionModify» si los niveles difieren; se aplica una lógica similar para las posiciones de venta utilizando «sellBreakEvenPrice» si el precio ask cae por debajo.
A continuación, procedemos a implementar la función "addAveragingOrder", que identifica la posición más reciente recorriendo PositionsTotal, actualizando "lastOpenPrice" con el peor precio de apertura —el Ask más bajo para las posiciones Buy o el Bid más alto para las posiciones Sell— y "lastLotSize" con el mayor volumen, estableciendo "isLastBuy" según corresponda. En el caso de las compras, si «supportResistanceLevel» supera el precio de apertura actual y se detecta una barra pin de compra con «IsBuyPinbar», y el precio de compra está por debajo de «lastOpenPrice» en «orderDistancePips * _Point», abrimos una posición de compra con «obj_Trade. PositionOpen» utilizando un tamaño de lote de «lastLotSize * lotMultiplier» normalizado por «fnGetLotDigit», con stop loss y take profit calculados, y desactivamos «isLastBuy»; para las ventas, comprobamos si el precio de venta está por encima de «lastOpenPrice» en «orderDistancePips * _Point» y abrimos una posición de venta de forma similar.
Por último, implementamos «addAveragingOrderWithAutoTP», que sigue la misma lógica que «addAveragingOrder», pero abre posiciones sin stop loss ni take profit iniciales (establecidos en 0), llama a «calculatePositionMetrics» para actualizar métricas como «buyBreakEvenPrice» e invoca «updateStopLossTakeProfit» para establecer niveles basados en el punto de equilibrio, lo que garantiza ajustes dinámicos para las operaciones de promediado. Ahora podemos llamar a estas funciones en la lógica de tick para que la lógica surta efecto.
if (useSignalMode == ENABLED && CountTradesBuy() >= 1 && CountTradesBuy() < maxOrders && useAutoTakeProfit == false) { //--- Check buy averaging
   addAveragingOrder();                        //--- Add buy averaging order
}
if (useSignalMode == ENABLED && CountTradesSell() >= 1 && CountTradesSell() < maxOrders && useAutoTakeProfit == false) { //--- Check sell averaging
   addAveragingOrder();                        //--- Add sell averaging order
}
if (useSignalMode == ENABLED && CountTradesBuy() >= 1 && CountTradesBuy() < maxOrders && useAutoTakeProfit == true) { //--- Check buy averaging with auto TP
   addAveragingOrderWithAutoTP();              //--- Add buy averaging order with auto TP
}
if (useSignalMode == ENABLED && CountTradesSell() >= 1 && CountTradesSell() < maxOrders && useAutoTakeProfit == true) { //--- Check sell averaging with auto TP
   addAveragingOrderWithAutoTP();              //--- Add sell averaging order with auto TP
}
Completamos la implementación de la lógica de «tick» añadiendo una lógica que gestione el promedio de las operaciones en condiciones específicas, lo que mejora la capacidad del EA para escalar entradas de forma dinámica. En primer lugar, cuando «useSignalMode» está en «ENABLED», comprobamos si hay al menos una posición de compra con «CountTradesBuy» y si el número de posiciones de compra es inferior a «maxOrders»; si «useAutoTakeProfit» es falso, llamamos a «addAveragingOrder» para abrir una posición de compra adicional basándonos en la detección de barras pin y en criterios de distancia del precio, utilizando un tamaño de lote multiplicado.
A continuación, aplicamos la misma lógica a las posiciones de venta, comprobando «CountTradesSell» y llamando a la función «addAveragingOrder» si «useAutoTakeProfit» es falso, para añadir una posición de venta en condiciones similares. A continuación, para las posiciones de compra cuando «useAutoTakeProfit» es «true», llamamos a «addAveragingOrderWithAutoTP» para abrir una posición de compra sin un stop loss ni un take profit iniciales, tras lo cual actualizamos las métricas y ajustamos los niveles basados en el punto de equilibrio. Por último, repetimos este proceso para las posiciones de venta cuando «useAutoTakeProfit» es verdadero, llamando a «addAveragingOrderWithAutoTP» para añadir una posición de venta con ajustes dinámicos de stop loss y take profit. Esta lógica garantizará que el EA gestione de forma eficaz las operaciones de promediado en el modo de señal, adaptándose a los movimientos del mercado. Tras la compilación, obtenemos el siguiente resultado.
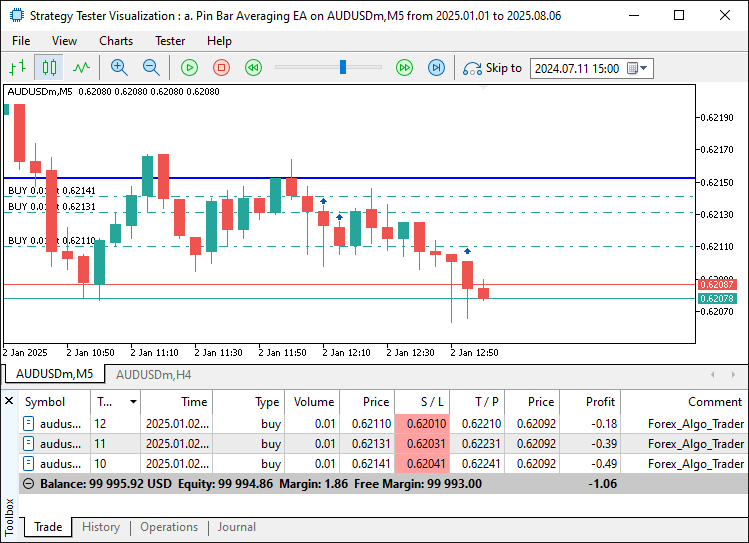
Ahora que hemos añadido la opción de promediar, solo queda añadir una lógica de «trailing stop» para la gestión del riesgo. Para garantizar un control preciso del riesgo, la lógica deberá ejecutarse en cada tick, por lo que la añadiremos fuera de la lógica de restricción de barras.
double setPointValue = normalizedPoint;         //--- Set point value for calculations
if (useTrailingStop && trailingStartPips > 0 && breakevenPips < trailingStartPips) { //--- Check trailing stop conditions
   double averageBuyPrice = rata_price(ORDER_TYPE_BUY); //--- Calculate average buy price
   double trailingReference = 0;                //--- Initialize trailing reference
   for (int iTrade = 0; iTrade < PositionsTotal(); iTrade++) { //--- Iterate through positions
      ulong ticket = PositionGetTicket(iTrade); //--- Get position ticket
      if (ticket == 0) continue;                //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY && PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check buy position
         if (useAutoTakeProfit) {               //--- Check auto take profit
            trailingReference = averageBuyPrice; //--- Use average buy price
         } else {                               //--- Use open price
            trailingReference = PositionGetDouble(POSITION_PRICE_OPEN); //--- Set open price
         }
         if (SymbolInfoDouble(_Symbol, SYMBOL_BID) - trailingReference > trailingStartPips * setPointValue) { //--- Check trailing condition
            if (SymbolInfoDouble(_Symbol, SYMBOL_BID) - ((trailingStartPips - breakevenPips) * setPointValue) > PositionGetDouble(POSITION_SL)) { //--- Check stop loss adjustment
               obj_Trade.PositionModify(ticket, SymbolInfoDouble(_Symbol, SYMBOL_BID) - ((trailingStartPips - breakevenPips) * setPointValue), PositionGetDouble(POSITION_TP)); //--- Modify position
            }
         }
      }
   }
   double averageSellPrice = rata_price(ORDER_TYPE_SELL); //--- Calculate average sell price
   for (int iTrade2 = 0; iTrade2 < PositionsTotal(); iTrade2++) { //--- Iterate through positions
      ulong ticket2 = PositionGetTicket(iTrade2); //--- Get position ticket
      if (ticket2 == 0) continue;               //--- Skip invalid tickets
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL && PositionGetString(POSITION_SYMBOL) == Symbol() && PositionGetInteger(POSITION_MAGIC) == magicNumber) { //--- Check sell position
         if (useAutoTakeProfit) {               //--- Check auto take profit
            trailingReference = averageSellPrice; //--- Use average sell price
         } else {                               //--- Use open price
            trailingReference = PositionGetDouble(POSITION_PRICE_OPEN); //--- Set open price
         }
         if (trailingReference - SymbolInfoDouble(_Symbol, SYMBOL_ASK) > trailingStartPips * setPointValue) { //--- Check trailing condition
            if (SymbolInfoDouble(_Symbol, SYMBOL_ASK) + ((trailingStartPips - breakevenPips) * setPointValue) < PositionGetDouble(POSITION_SL) || PositionGetDouble(POSITION_SL) == 0) { //--- Check stop loss adjustment
               obj_Trade.PositionModify(ticket2, SymbolInfoDouble(_Symbol, SYMBOL_ASK) + ((trailingStartPips - breakevenPips) * setPointValue), PositionGetDouble(POSITION_TP)); //--- Modify position
            }
         }
      }
   }
}
Implementamos la lógica del trailing stop estableciendo primero «setPointValue» en «normalizedPoint» para garantizar la coherencia en los cálculos de precios, y comprobando si «useTrailingStop» es verdadero, si «trailingStartPips» es un valor positivo y si «breakevenPips» es menor que «trailingStartPips», con el fin de garantizar que las condiciones del trailing stop sean válidas. A continuación, procedemos a gestionar las posiciones de compra calculando el «averageBuyPrice» utilizando «rata_price» para ORDER_TYPE_BUY, recorriendo todas las posiciones para obtener los tickets de posiciones de compra válidos que coincidan con «Symbol» y «magicNumber», estableciendo «trailingReference» en «averageBuyPrice» si «useAutoTakeProfit» es verdadero o en «POSITION_PRICE_OPEN» en caso contrario, y modificando el stop loss con «obj_Trade. PositionModify» a SYMBOL_BID - (trailingStartPips - breakevenPips) * setPointValue» si el precio de compra supera «trailingReference» en «trailingStartPips * setPointValue» y el nuevo stop loss es superior al actual.
A continuación, aplicamos una lógica similar para las posiciones de venta, calculando «averageSellPrice» con «rata_price» para «ORDER_TYPE_SELL», recorriendo las posiciones, estableciendo «trailingReference» en «averageSellPrice» o POSITION_PRICE_OPEN, y modificando el stop loss a «SYMBOL_ASK + (trailingStartPips - breakevenPips) * setPointValue» si el precio de venta está por debajo de «trailingReference» en «trailingStartPips * setPointValue» y el nuevo stop loss es inferior o no está establecido. Por último, nos aseguramos de que las modificaciones mantengan el take profit existente mediante «PositionGetDouble(POSITION_TP)» y llamamos a ChartRedraw en la función principal para actualizar el gráfico. Tras la compilación, obtenemos el siguiente resultado.
Antes del trailing stop:
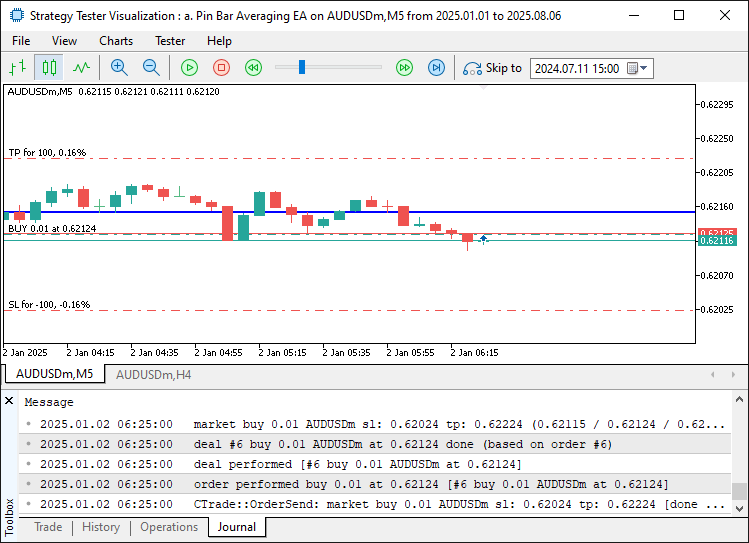
Después del trailing stop:
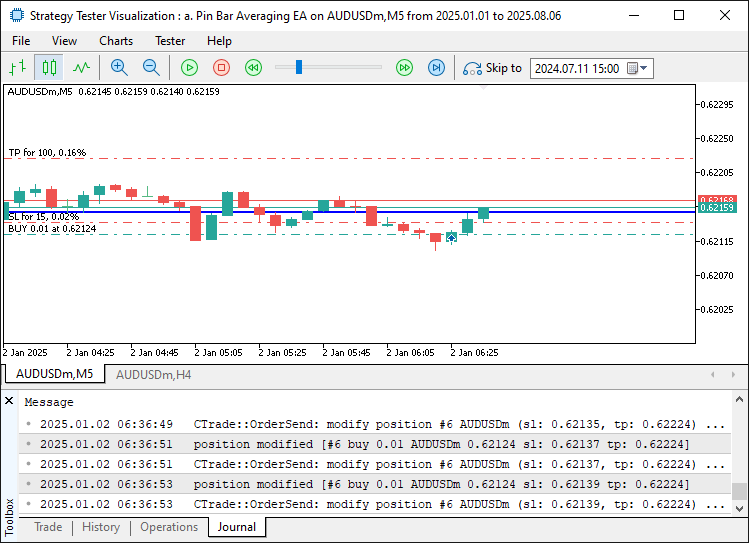
Ahora que hemos completado la lógica de gestión de posiciones, podemos crear un panel de control para visualizar las métricas de la cuenta. Para eso también utilizamos una función, ya que facilita la gestión.
//+------------------------------------------------------------------+
//| Display dashboard information                                    |
//+------------------------------------------------------------------+
void Display_Info() {
   buyCount = 0;                                  //--- Reset buy count
   currentBuyLot = 0;                             //--- Reset current buy lot
   totalBuyLots = 0;                              //--- Reset total buy lots
   sellCount = 0;                                 //--- Reset sell count
   currentSellLot = 0;                            //--- Reset current sell lot
   totalSellLots = 0;                             //--- Reset total sell lots
   totalSum = 0;                                  //--- Reset total sum
   totalSwap = 0;                                 //--- Reset total swap
   buyProfit = 0;                                 //--- Reset buy profit
   sellProfit = 0;                                //--- Reset sell profit
   buyWeightedSum = 0;                            //--- Reset buy weighted sum
   sellWeightedSum = 0;                           //--- Reset sell weighted sum
   buyBreakEvenPrice = 0;                         //--- Reset buy breakeven price
   sellBreakEvenPrice = 0;                        //--- Reset sell breakeven price
   minBuyLot = 9999;                              //--- Initialize min buy lot
   minSellLot = 9999;                             //--- Initialize min sell lot
   maxSellPrice = 0;                              //--- Initialize max sell price
   minBuyPrice = 999999999;                       //--- Initialize min buy price
   for (int i = 0; i < PositionsTotal(); i++) {   //--- Iterate through positions
      ulong ticket = PositionGetTicket(i);        //--- Get position ticket
      if (ticket == 0) continue;                  //--- Skip invalid tickets
      if (PositionGetString(POSITION_SYMBOL) != Symbol()) continue; //--- Skip non-matching symbols
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_BUY) { //--- Check buy position
         buyCount++;                              //--- Increment buy count
         totalOperations++;                       //--- Increment total operations
         currentBuyLot = PositionGetDouble(POSITION_VOLUME); //--- Set current buy lot
         buyProfit += PositionGetDouble(POSITION_PROFIT); //--- Add buy profit
         totalBuyLots += PositionGetDouble(POSITION_VOLUME); //--- Add to total buy lots
         minBuyLot = MathMin(minBuyLot, PositionGetDouble(POSITION_VOLUME)); //--- Update min buy lot
         buyWeightedSum += PositionGetDouble(POSITION_VOLUME) * PositionGetDouble(POSITION_PRICE_OPEN); //--- Add weighted open price
         minBuyPrice = MathMin(minBuyPrice, PositionGetDouble(POSITION_PRICE_OPEN)); //--- Update min buy price
      }
      if (PositionGetInteger(POSITION_TYPE) == POSITION_TYPE_SELL) { //--- Check sell position
         sellCount++;                             //--- Increment sell count
         totalOperations++;                       //--- Increment total operations
         currentSellLot = PositionGetDouble(POSITION_VOLUME); //--- Set current sell lot
         sellProfit += PositionGetDouble(POSITION_PROFIT); //--- Add sell profit
         totalSellLots += PositionGetDouble(POSITION_VOLUME); //--- Add to total sell lots
         minSellLot = MathMin(minSellLot, PositionGetDouble(POSITION_VOLUME)); //--- Update min sell lot
         sellWeightedSum += PositionGetDouble(POSITION_VOLUME) * PositionGetDouble(POSITION_PRICE_OPEN); //--- Add weighted open price
         maxSellPrice = MathMax(maxSellPrice, PositionGetDouble(POSITION_PRICE_OPEN)); //--- Update max sell price
      }
   }
   if (totalBuyLots > 0) {                        //--- Check buy lots
      buyBreakEvenPrice = buyWeightedSum / totalBuyLots; //--- Calculate buy breakeven
   }
   if (totalSellLots > 0) {                       //--- Check sell lots
      sellBreakEvenPrice = sellWeightedSum / totalSellLots; //--- Calculate sell breakeven
   }
   int minutesRemaining, secondsRemaining;        //--- Declare time variables
   minutesRemaining = (int)(PeriodSeconds() - (TimeCurrent() - iTime(Symbol(), PERIOD_CURRENT, 0))); //--- Calculate remaining time
   secondsRemaining = minutesRemaining % 60;      //--- Calculate seconds
   minutesRemaining = minutesRemaining / 60;      //--- Calculate minutes
   long currentSpread = SymbolInfoInteger(Symbol(), SYMBOL_SPREAD); //--- Get current spread
   string spreadPrefix = "", minutesPrefix = "", secondsPrefix = ""; //--- Initialize prefixes
   if (currentSpread < 10) spreadPrefix = "..";   //--- Set spread prefix for single digit
   else if (currentSpread < 100) spreadPrefix = "."; //--- Set spread prefix for double digit
   if (minutesRemaining < 10) minutesPrefix = "0"; //--- Set minutes prefix
   if (secondsRemaining < 10) secondsPrefix = "0"; //--- Set seconds prefix
   int blinkingColorIndex;                        //--- Declare blinking color index
   color equityColor = clrGreen;                  //--- Initialize equity color
   if (AccountInfoDouble(ACCOUNT_EQUITY) - AccountInfoDouble(ACCOUNT_BALANCE) < 0.0) { //--- Check negative equity
      equityColor = clrRed;                       //--- Set equity color to red
   }
   color profitColor = (buyProfit + sellProfit >= 0) ? clrGreen : clrRed; //--- Set profit color
   MqlDateTime currentDateTime;                   //--- Declare datetime structure
   TimeToStruct(TimeCurrent(), currentDateTime);  //--- Convert current time
   if (currentDateTime.sec >= 0 && currentDateTime.sec < 10) { //--- Check first 10 seconds
      blinkingColorIndex = clrRed;                //--- Set red color
   }
   if (currentDateTime.sec >= 10 && currentDateTime.sec < 20) { //--- Check next 10 seconds
      blinkingColorIndex = clrOrange;             //--- Set orange color
   }
   if (currentDateTime.sec >= 20 && currentDateTime.sec < 30) { //--- Check next 10 seconds
      blinkingColorIndex = clrBlue;               //--- Set blue color
   }
   if (currentDateTime.sec >= 30 && currentDateTime.sec < 40) { //--- Check next 10 seconds
      blinkingColorIndex = clrDodgerBlue;         //--- Set dodger blue color
   }
   if (currentDateTime.sec >= 40 && currentDateTime.sec < 50) { //--- Check next 10 seconds
      blinkingColorIndex = clrYellow;             //--- Set yellow color
   }
   if (currentDateTime.sec >= 50 && currentDateTime.sec <= 59) { //--- Check last 10 seconds
      blinkingColorIndex = clrYellow;             //--- Set yellow color
   }
   if (ObjectFind(0, "DashboardBG") < 0) {        //--- Check dashboard background
      ObjectCreate(0, "DashboardBG", OBJ_RECTANGLE_LABEL, 0, 0, 0); //--- Create dashboard background
      ObjectSetInteger(0, "DashboardBG", OBJPROP_CORNER, 0); //--- Set corner
      ObjectSetInteger(0, "DashboardBG", OBJPROP_XDISTANCE, 100); //--- Set x distance
      ObjectSetInteger(0, "DashboardBG", OBJPROP_YDISTANCE, 20); //--- Set y distance
      ObjectSetInteger(0, "DashboardBG", OBJPROP_XSIZE, 260); //--- Set width
      ObjectSetInteger(0, "DashboardBG", OBJPROP_YSIZE, 300); //--- Set height
      ObjectSetInteger(0, "DashboardBG", OBJPROP_BGCOLOR, clrLightGray); //--- Set background color
      ObjectSetInteger(0, "DashboardBG", OBJPROP_BORDER_TYPE, BORDER_FLAT); //--- Set border type
      ObjectSetInteger(0, "DashboardBG", OBJPROP_COLOR, clrBlack); //--- Set border color
      ObjectSetInteger(0, "DashboardBG", OBJPROP_BACK, false); //--- Set to foreground
   }
   if (ObjectFind(0, "CLOSE ALL") < 0) {          //--- Check close all button
      ObjectCreate(0, "CLOSE ALL", OBJ_BUTTON, 0, 0, 0); //--- Create close all button
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_CORNER, 0); //--- Set corner
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_XDISTANCE, 110); //--- Set x distance
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_YDISTANCE, 280); //--- Set y distance
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_XSIZE, 240); //--- Set width
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_YSIZE, 25); //--- Set height
      ObjectSetString(0, "CLOSE ALL", OBJPROP_TEXT, "Close All Positions"); //--- Set button text
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_COLOR, clrWhite); //--- Set text color
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_BGCOLOR, clrRed); //--- Set background color
      ObjectSetInteger(0, "CLOSE ALL", OBJPROP_BORDER_COLOR, clrBlack); //--- Set border color
   }
   string headerText = "Pin Bar Averaging EA";    //--- Set header text
   LABEL("Header", "Impact", 20, 110, 20, clrNavy, 0, headerText); //--- Create header label
   string copyrightText = "Copyright 2025, Allan Munene Mutiiria"; //--- Set copyright text
   LABEL("Copyright", "Arial", 9, 110, 55, clrBlack, 0, copyrightText); //--- Create copyright label
   string linkText = "https://t.me/Forex_Algo_Trader"; //--- Set link text
   LABEL("Link", "Arial", 9, 110, 70, clrBlue, 0, linkText); //--- Create link label
   string accountHeader = "Account Information";  //--- Set account header
   LABEL("AccountHeader", "Arial Bold", 10, 110, 90, clrBlack, 0, accountHeader); //--- Create account header label
   string balanceText = "Balance: " + DoubleToString(AccountInfoDouble(ACCOUNT_BALANCE), 2); //--- Set balance text
   LABEL("Balance", "Arial", 9, 120, 105, clrBlack, 0, balanceText); //--- Create balance label
   string equityText = "Equity: " + DoubleToString(AccountInfoDouble(ACCOUNT_EQUITY), 2); //--- Set equity text
   LABEL("Equity", "Arial", 9, 120, 120, equityColor, 0, equityText); //--- Create equity label
   string marginText = "Free Margin: " + DoubleToString(AccountInfoDouble(ACCOUNT_MARGIN_FREE), 2); //--- Set margin text
   LABEL("Margin", "Arial", 9, 120, 135, clrBlack, 0, marginText); //--- Create margin label
   string profitText = "Open Profit: " + DoubleToString(buyProfit + sellProfit, 2); //--- Set profit text
   LABEL("Profit", "Arial", 9, 120, 150, profitColor, 0, profitText); //--- Create profit label
   string positionsText = "Buy Positions: " + IntegerToString((int)buyCount) + " Sell Positions: " + IntegerToString((int)sellCount); //--- Set positions text
   LABEL("Positions", "Arial", 9, 120, 165, clrBlack, 0, positionsText); //--- Create positions label
   string buyBEText = "Buy Break Even: " + (buyCount > 0 ? DoubleToString(buyBreakEvenPrice, _Digits) : "-"); //--- Set buy breakeven text
   LABEL("BuyBE", "Arial", 9, 120, 180, clrBlack, 0, buyBEText); //--- Create buy breakeven label
   string sellBEText = "Sell Break Even: " + (sellCount > 0 ? DoubleToString(sellBreakEvenPrice, _Digits) : "-"); //--- Set sell breakeven text
   LABEL("SellBE", "Arial", 9, 120, 195, clrBlack, 0, sellBEText); //--- Create sell breakeven label
   string spreadText = "Spread: " + spreadPrefix + IntegerToString((int)currentSpread) + " points"; //--- Set spread text
   LABEL("Spread", "Arial", 9, 120, 210, clrBlack, 0, spreadText); //--- Create spread label
   string timeText = "Time to next bar: " + minutesPrefix + IntegerToString(minutesRemaining) + ":" + secondsPrefix + IntegerToString(secondsRemaining); //--- Set time text
   LABEL("Time", "Arial", 9, 120, 225, clrBlack, 0, timeText); //--- Create time label
   string pinbarText;                             //--- Declare pinbar text
   if (IsBuyPinbar()) pinbarText = "Buy Pinbar";  //--- Check buy pinbar
   else if (IsSellPinbar()) pinbarText = "Sell Pinbar"; //--- Check sell pinbar
   else pinbarText = "None";                      //--- Set no pinbar
   LABEL("Pinbar", "Arial", 9, 120, 240, clrBlack, 0, "Pinbar Signal: " + pinbarText); //--- Create pinbar label
   string patternText = "Candle Pattern: " + CandleStick_Analyzer(); //--- Set candlestick pattern text
   LABEL("Pattern", "Arial", 9, 120, 255, clrBlack, 0, patternText); //--- Create pattern label
}
Implementamos la función «Display_Info» para crear un panel de control completo que permita supervisar las operaciones en tiempo real. En primer lugar, restablecemos las métricas clave, como «buyCount» y otras, a sus respectivos valores iniciales; a continuación, recorremos todas las posiciones para actualizar estas métricas en las posiciones de compra y venta que coincidan con «Symbol», incrementando los recuentos, sumando los beneficios, los volúmenes y los precios de apertura ponderados, y haciendo un seguimiento de los precios mínimos y máximos, además de calcular los precios de equilibrio, si procede.
A continuación, calculamos el tiempo que queda hasta la siguiente barra utilizando PeriodSeconds menos la diferencia entre la hora actual y iTime, lo convertimos en «minutesRemaining» y «secondsRemaining», y establecemos los prefijos de formato para la visualización del intervalo y la hora. A continuación, determinamos «equityColor» (verde o rojo, en función del patrimonio frente al saldo) y «profitColor» (verde o rojo, en función del beneficio total), y establecemos un índice de color parpadeante basado en el segundo actual para conseguir un efecto visual. Por último, creamos un fondo para el panel de control con ObjectCreate como OBJ_RECTANGLE_LABEL si «DashboardBG» no existe, un botón «CLOSE ALL» como «OBJ_BUTTON», y varias etiquetas utilizando la función «LABEL» para mostrar el título del EA, los derechos de autor, el enlace, la información de la cuenta (saldo, equidad, margen libre, beneficios), el número de posiciones, los precios de equilibrio, el spread, el tiempo hasta la siguiente barra, la señal de barra pin y los patrones de velas de «CandleStick_Analyzer», lo que garantiza una visualización clara y dinámica de la información de las operaciones. En cuanto al botón, implementamos su lógica en el controlador de eventos OnChartEvent.
//+------------------------------------------------------------------+
//| Handle chart events                                              |
//+------------------------------------------------------------------+
void OnChartEvent(const int id, const long &lparam, const double &dparam, const string &sparam) {
   if (id == CHARTEVENT_OBJECT_CLICK) {           //--- Check object click event
      if (sparam == "CLOSE ALL") {                //--- Check close all button
         ObjectSetInteger(0, "CLOSE ALL", OBJPROP_STATE, false); //--- Reset button state
         for (int positionIndex = PositionsTotal() - 1; positionIndex >= 0; positionIndex--) { //--- Iterate through positions
            ulong ticket = PositionGetTicket(positionIndex); //--- Get position ticket
            if (ticket == 0) continue;            //--- Skip invalid tickets
            if (PositionGetString(POSITION_SYMBOL) == Symbol()) { //--- Check symbol
               obj_Trade.PositionClose(ticket);   //--- Close position
            }
         }
      }
   }
}
En la función OnChartEvent, comprobamos si el «id» del evento es CHARTEVENT_OBJECT_CLICK para detectar los clics sobre los objetos del gráfico. A continuación, comprobamos si el objeto sobre el que se ha hecho clic, «sparam», es el botón «CLOSE ALL» y, en caso afirmativo, restablecemos el estado del botón a «false» utilizando ObjectSetInteger con «OBJPROP_STATE». A continuación, recorremos todas las posiciones, recuperamos el ticket de cada una de ellas mediante PositionGetTicket, descartamos los tickets no válidos y comprobamos si el símbolo de la posición coincide con el «Símbolo» actual mediante la función PositionGetString. Por último, en el caso de las posiciones coincidentes, las cerramos mediante «obj_Trade.PositionClose» para ejecutar la orden del usuario de cerrar todas las posiciones, lo que garantiza que el botón «Cerrar todas las posiciones» del panel de control ofrezca una forma ágil de gestionar manualmente las operaciones abiertas. Al llamar a la función en OnTick y compilarla, obtenemos el siguiente resultado.
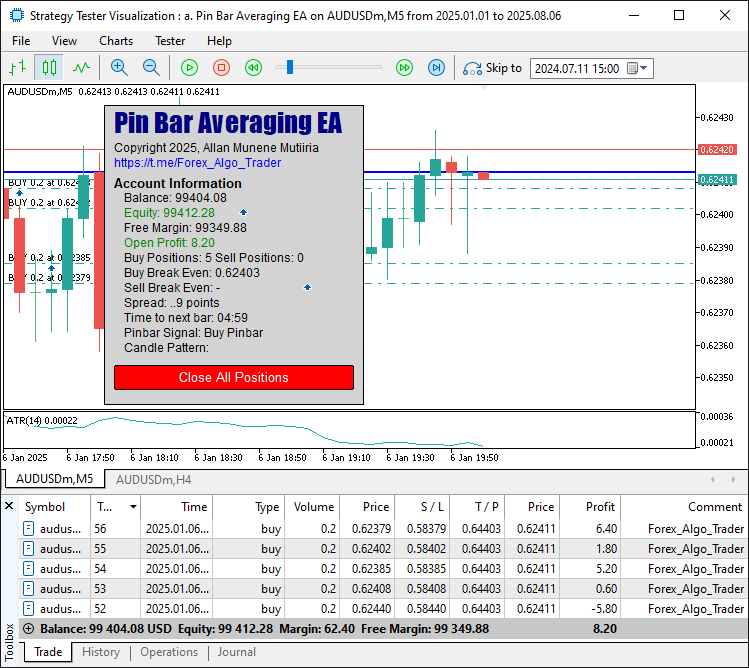
En la imagen podemos ver que el sistema detecta y visualiza los niveles de soporte y resistencia, abrir y promediar posiciones, aplicar trailing a las posiciones y visualizar los metadatos de la cuenta en un panel, con lo que se logran nuestros objetivos. Lo que queda por hacer es realizar un backtest del programa, y eso se trata en la siguiente sección.
Backtesting
Tras un backtesting exhaustivo, hemos obtenido los siguientes resultados.
Gráfico de backtest:
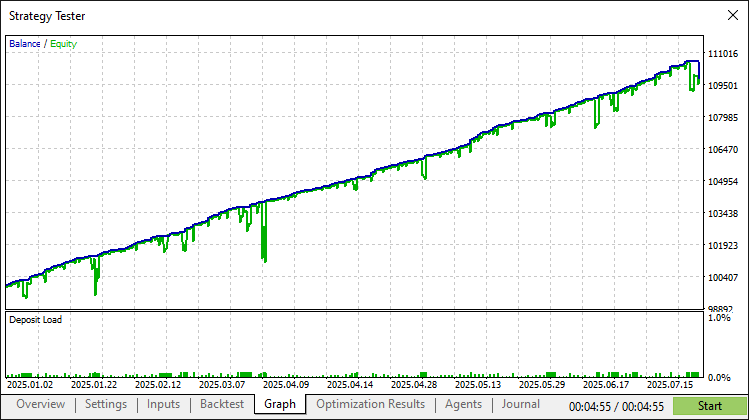
Informe de backtesting:
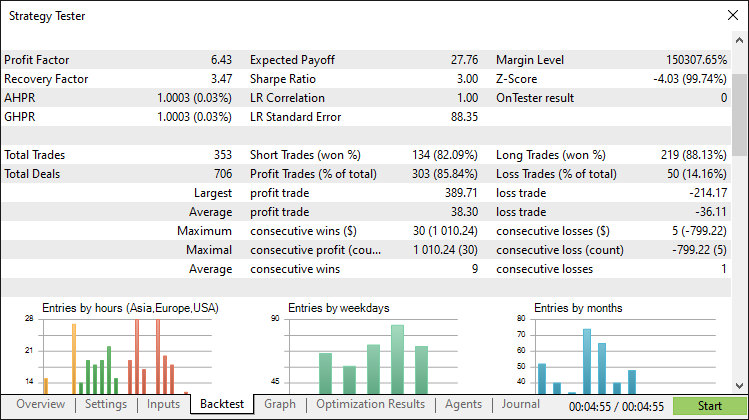
Conclusión
En conclusión, hemos desarrollado un sistema de promedios basado en Pin Bar en MQL5, que aprovecha los patrones de velas «pin bar» para iniciar operaciones y gestionar múltiples posiciones mediante una estrategia de promedios, mejorada con stops dinámicos, ajustes al punto de equilibrio y un panel de control dinámico para el seguimiento en tiempo real. A través de componentes modulares como las funciones «CandleStick_Analyzer» y «addAveragingOrder», este programa ofrece un enfoque disciplinado para la negociación de reversiones con controles de riesgo personalizables.
Descargo de responsabilidad: Este artículo tiene fines exclusivamente educativos. Operar en los mercados financieros conlleva riesgos financieros significativos, y la volatilidad del mercado puede ocasionar pérdidas. Es fundamental realizar pruebas retrospectivas exhaustivas y una gestión de riesgos cuidadosa antes de implementar este programa en mercados reales.
Aprovechando los conceptos y la implementación presentados, podrá adaptar este sistema de barras pin a su estilo de trading, mejorando así sus estrategias algorítmicas. ¡Feliz trading!
Traducción del inglés realizada por MetaQuotes Ltd.
Artículo original: https://www.mql5.com/en/articles/19087
Advertencia: todos los derechos de estos materiales pertenecen a MetaQuotes Ltd. Queda totalmente prohibido el copiado total o parcial.
Este artículo ha sido escrito por un usuario del sitio web y refleja su punto de vista personal. MetaQuotes Ltd. no se responsabiliza de la exactitud de la información ofrecida, ni de las posibles consecuencias del uso de las soluciones, estrategias o recomendaciones descritas.
 Red neuronal en la práctica: Perceptrón
 Automatización de estrategias de trading en MQL5 (Parte 25): Sistema de líneas de tendencia con ajuste por mínimos cuadrados y generación dinámica de señales
 Del nivel básico al intermedio: Objetos y subventanas (II)
 Integración de MQL5 con paquetes de procesamiento de datos (Parte 5): Aprendizaje adaptativo y flexibilidad

- Aplicaciones de trading gratuitas
- 8 000+ señales para copiar
- Noticias económicas para analizar los mercados financieros
Usted acepta la política del sitio web y las condiciones de uso