Auto Optimized SpeedAngle
- Indicators
- Version: 1.0
- Activations: 5

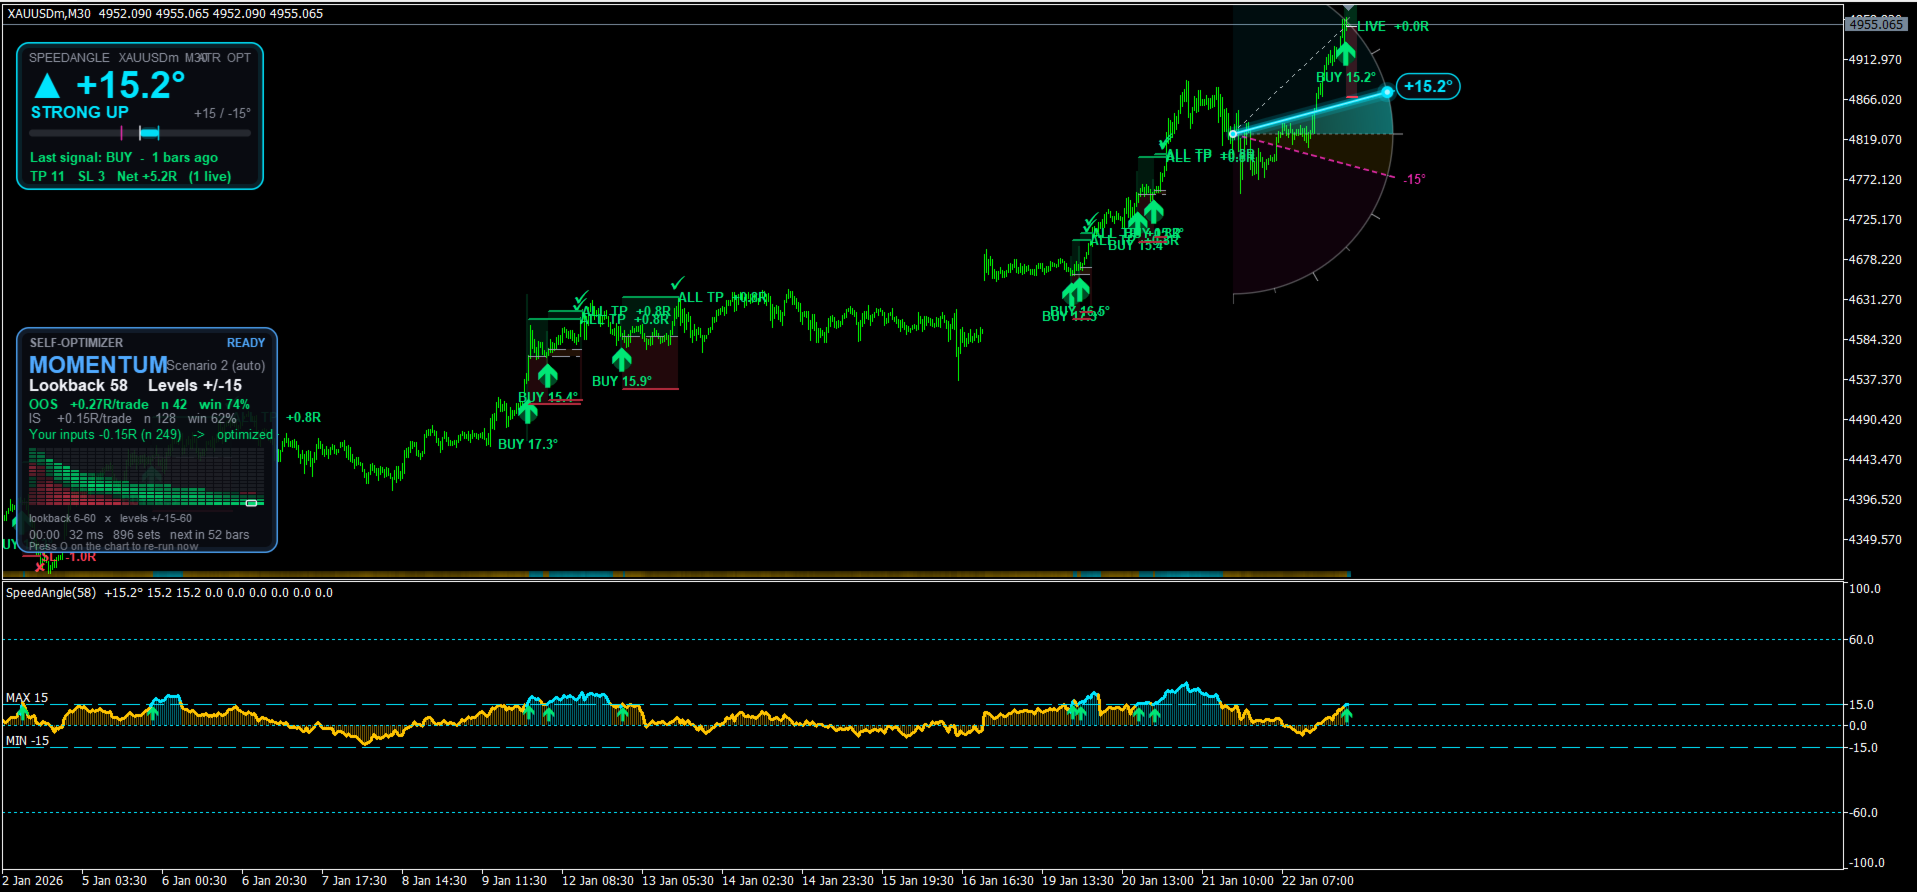
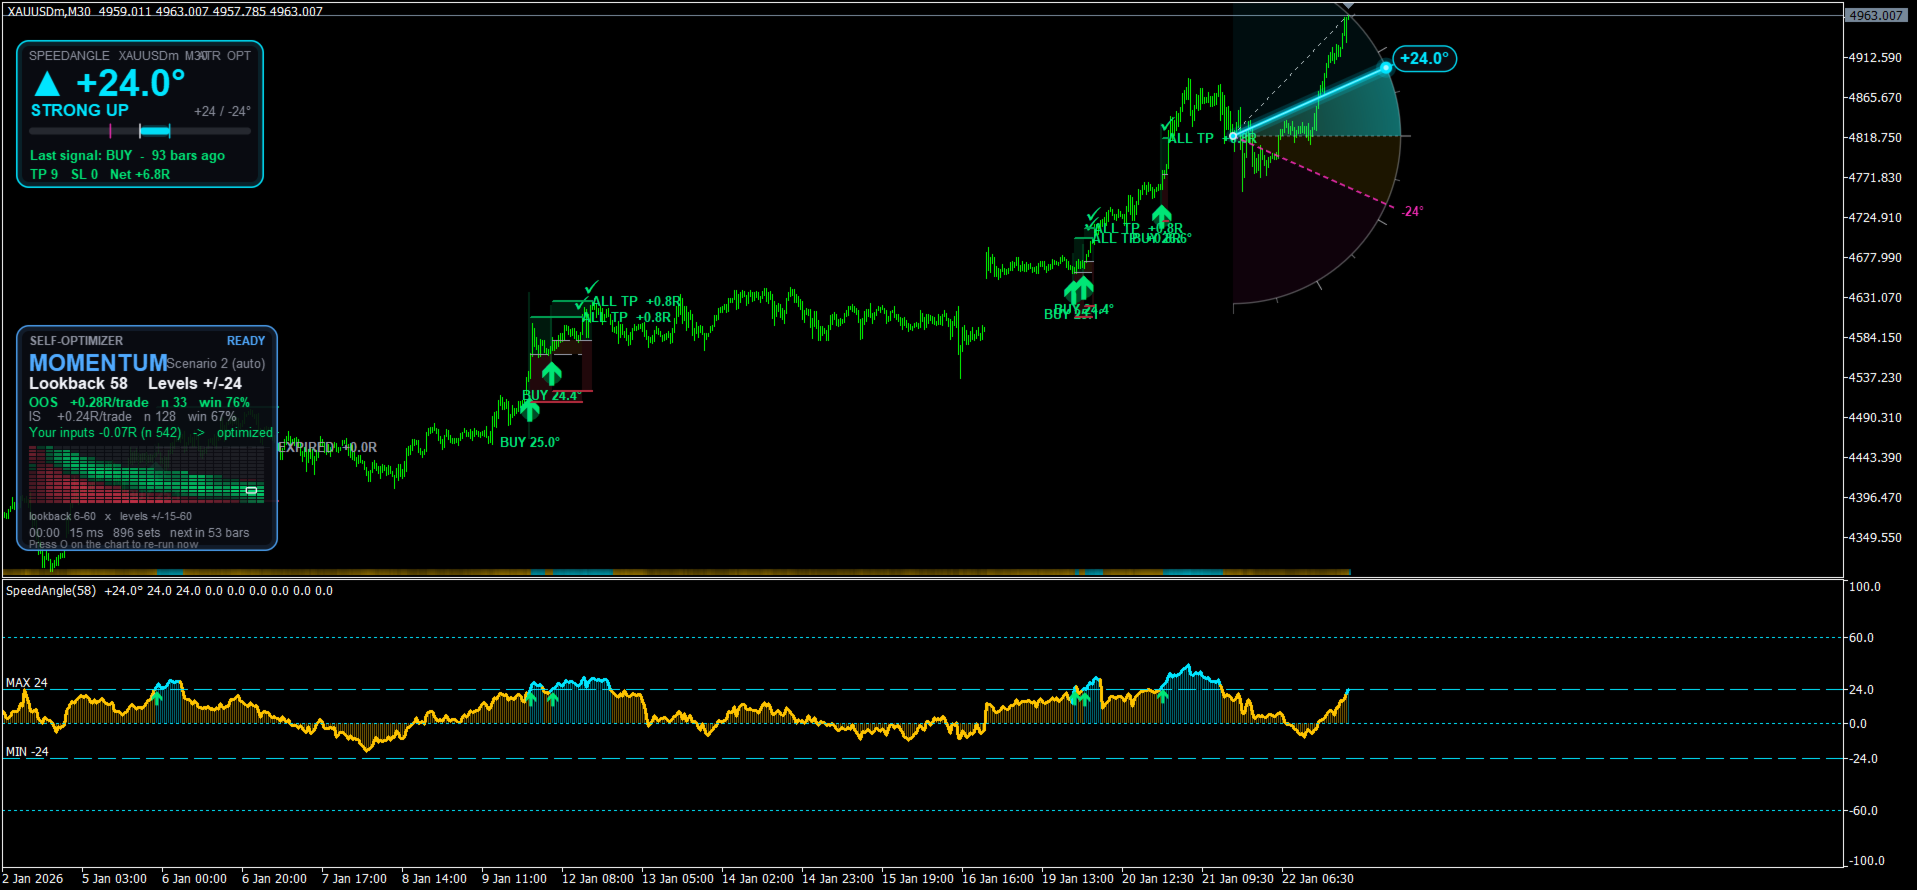
Auto Optimized SpeedAngle is an institutional-grade momentum vectoring system that eliminates curve-fitting through continuous Walk-Forward Optimization (WFO). Rather than relying on static inputs that degrade when market regimes shift, the indicator dynamically recalibrates its parameters using Out-of-Sample (OOS) validation, ensuring the displayed signals represent genuine statistical edges rather than historical anomalies.
By shifting the focus from subjective visual angles to normalized, quantitative logic, it operates as a complete, self-tuning trade management suite.
Core Institutional Framework
-
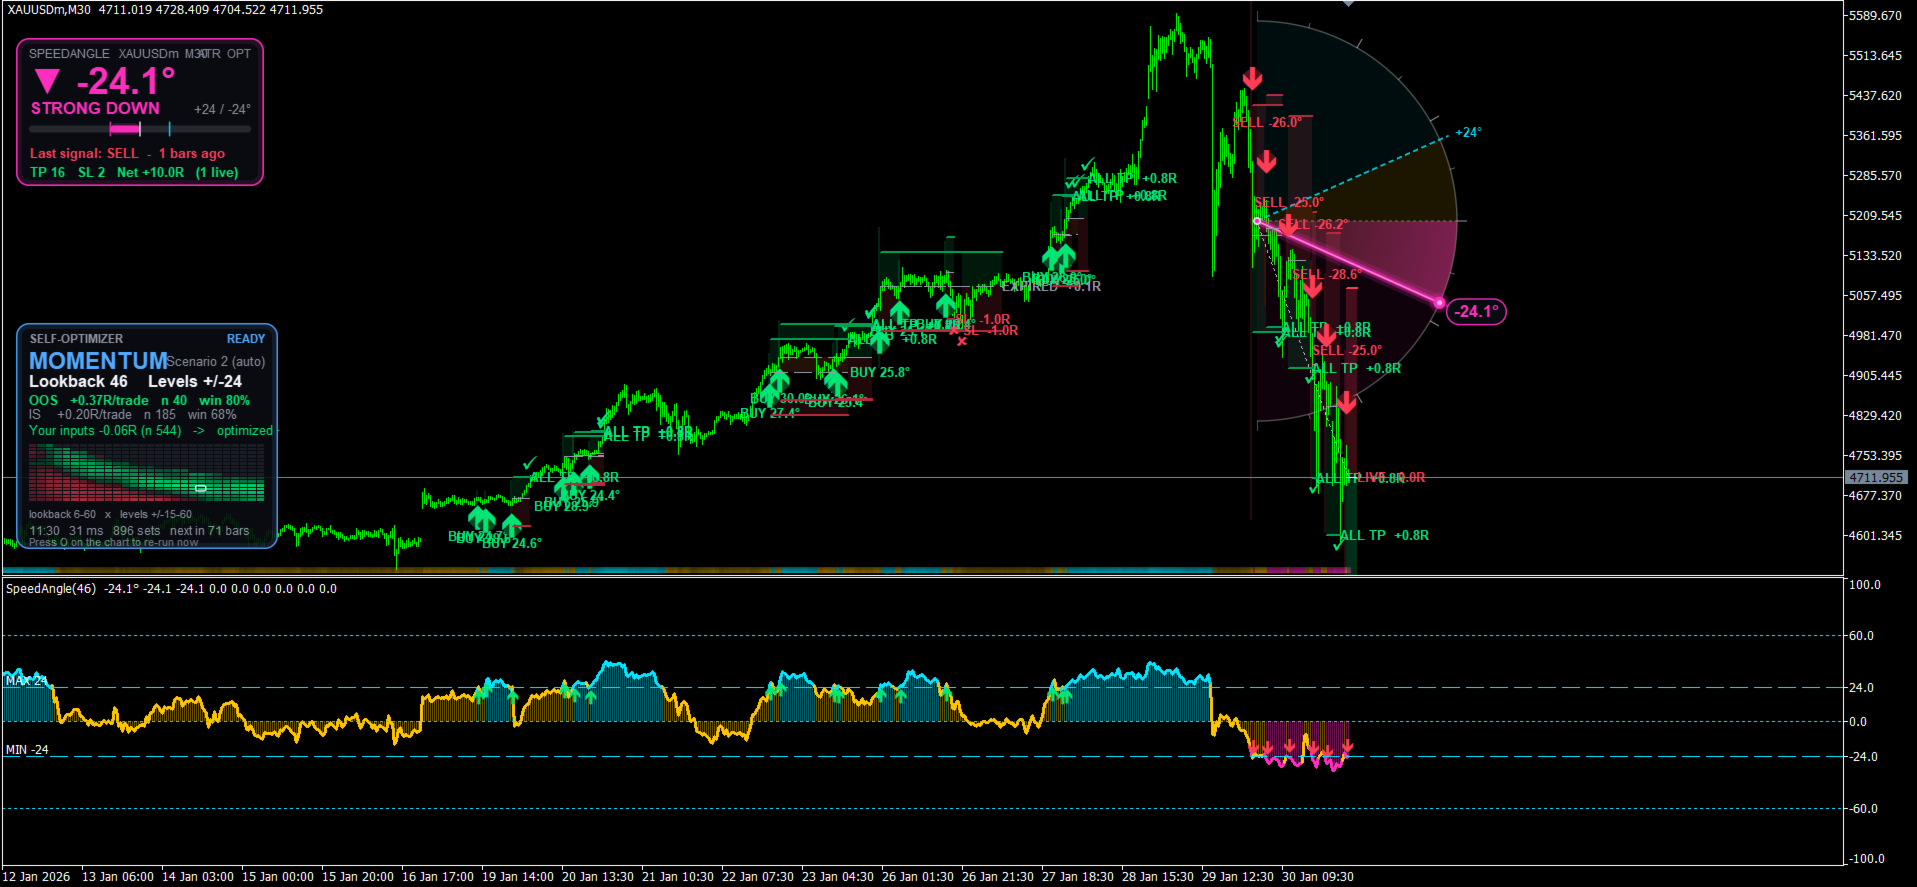
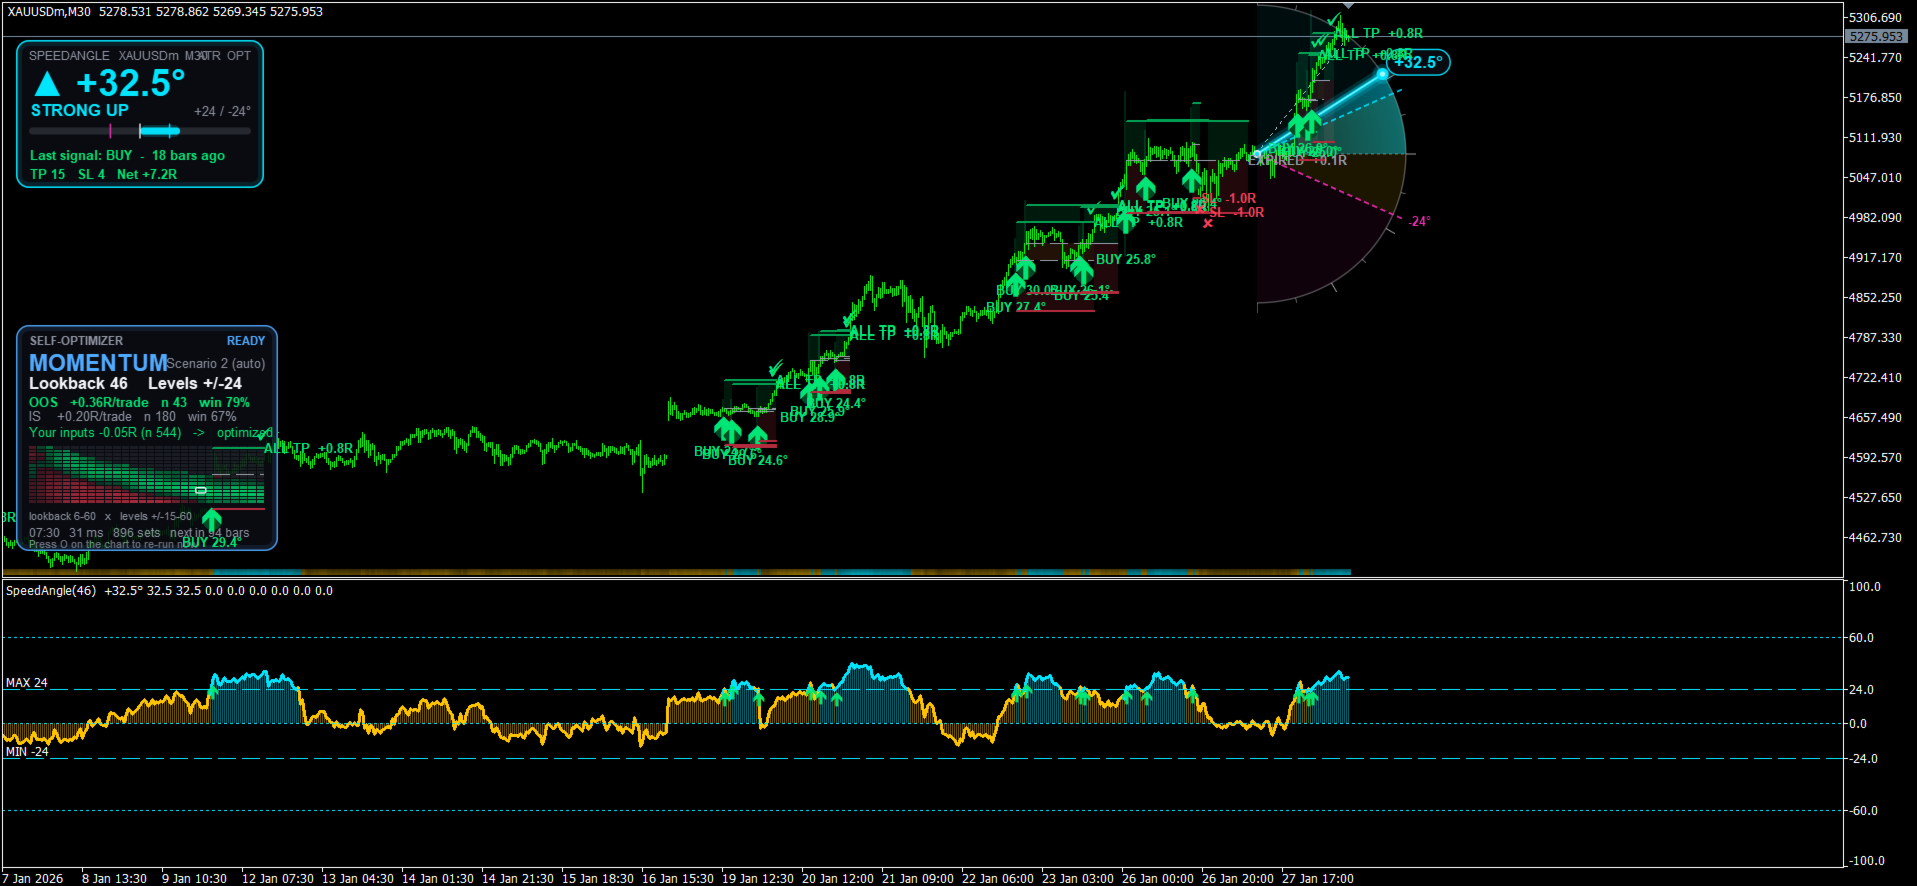
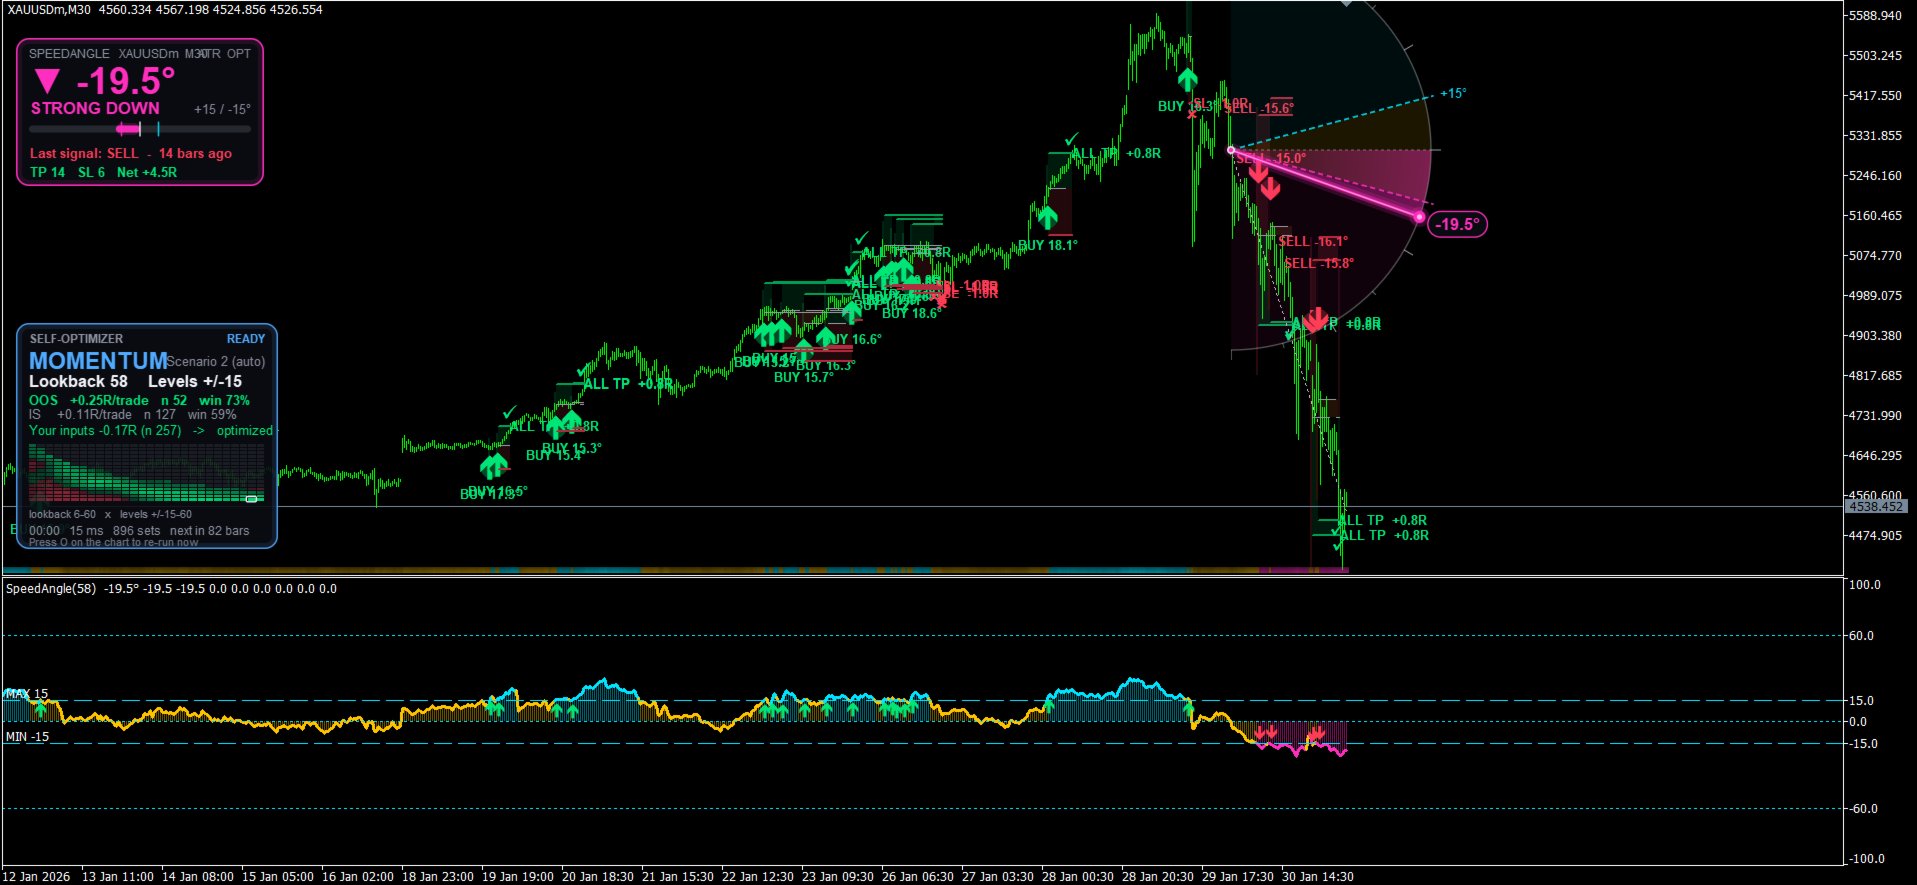
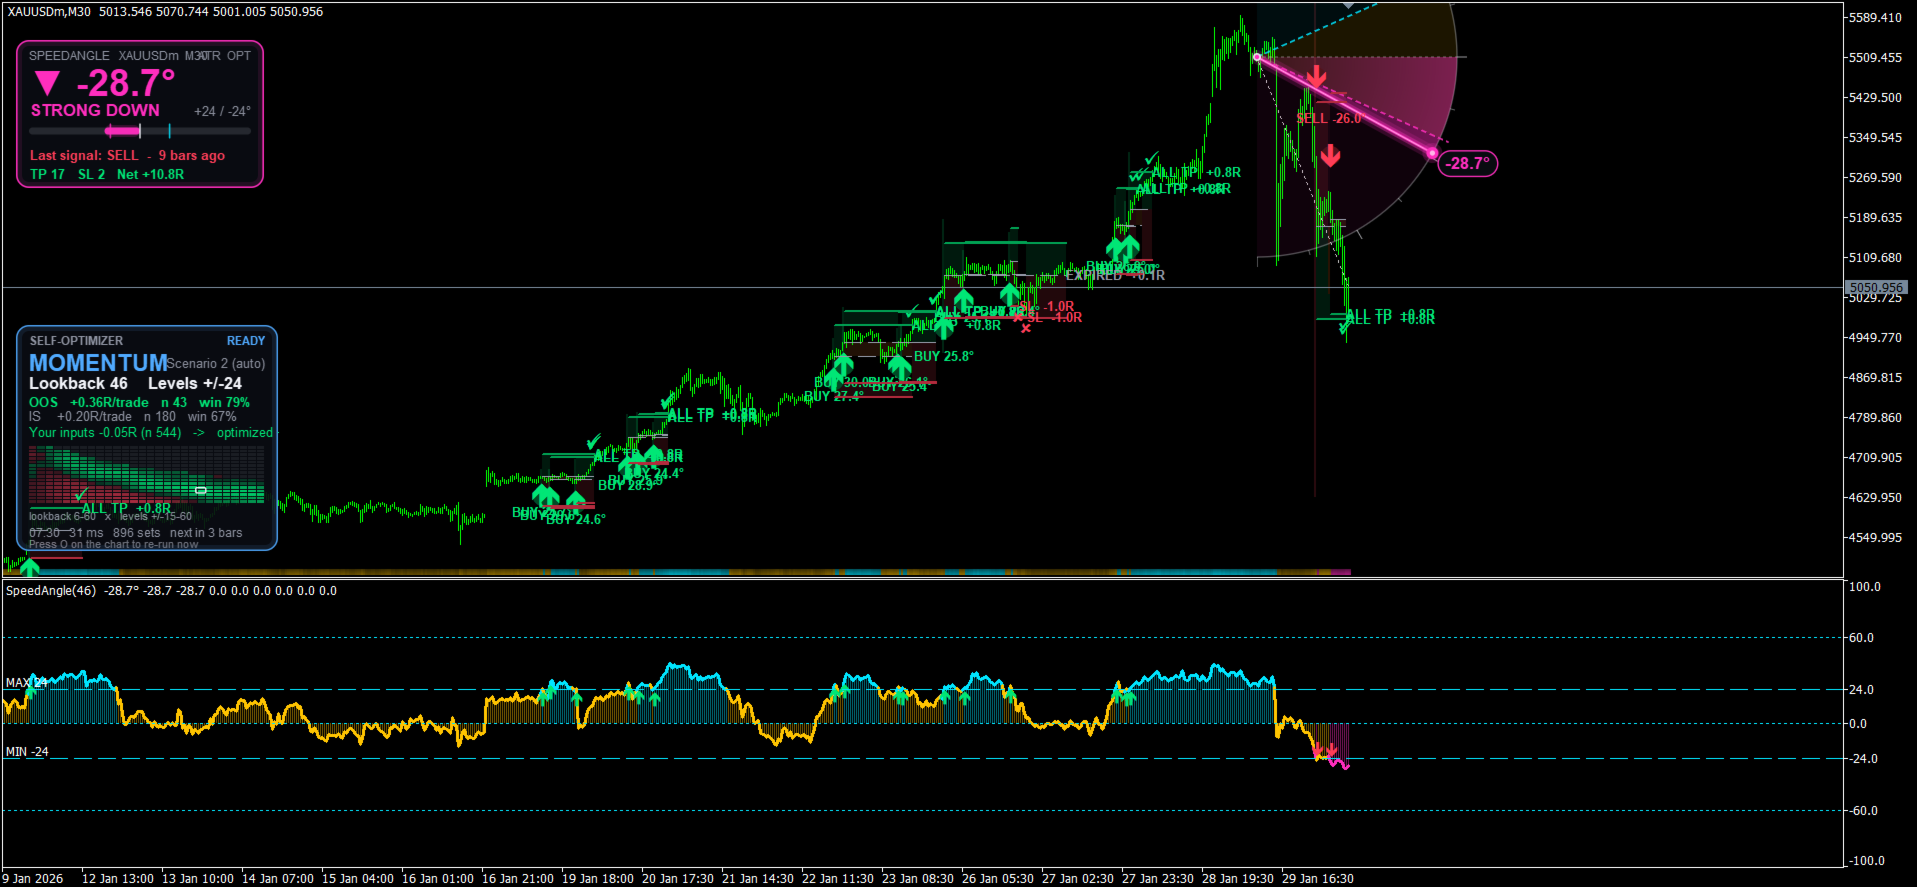
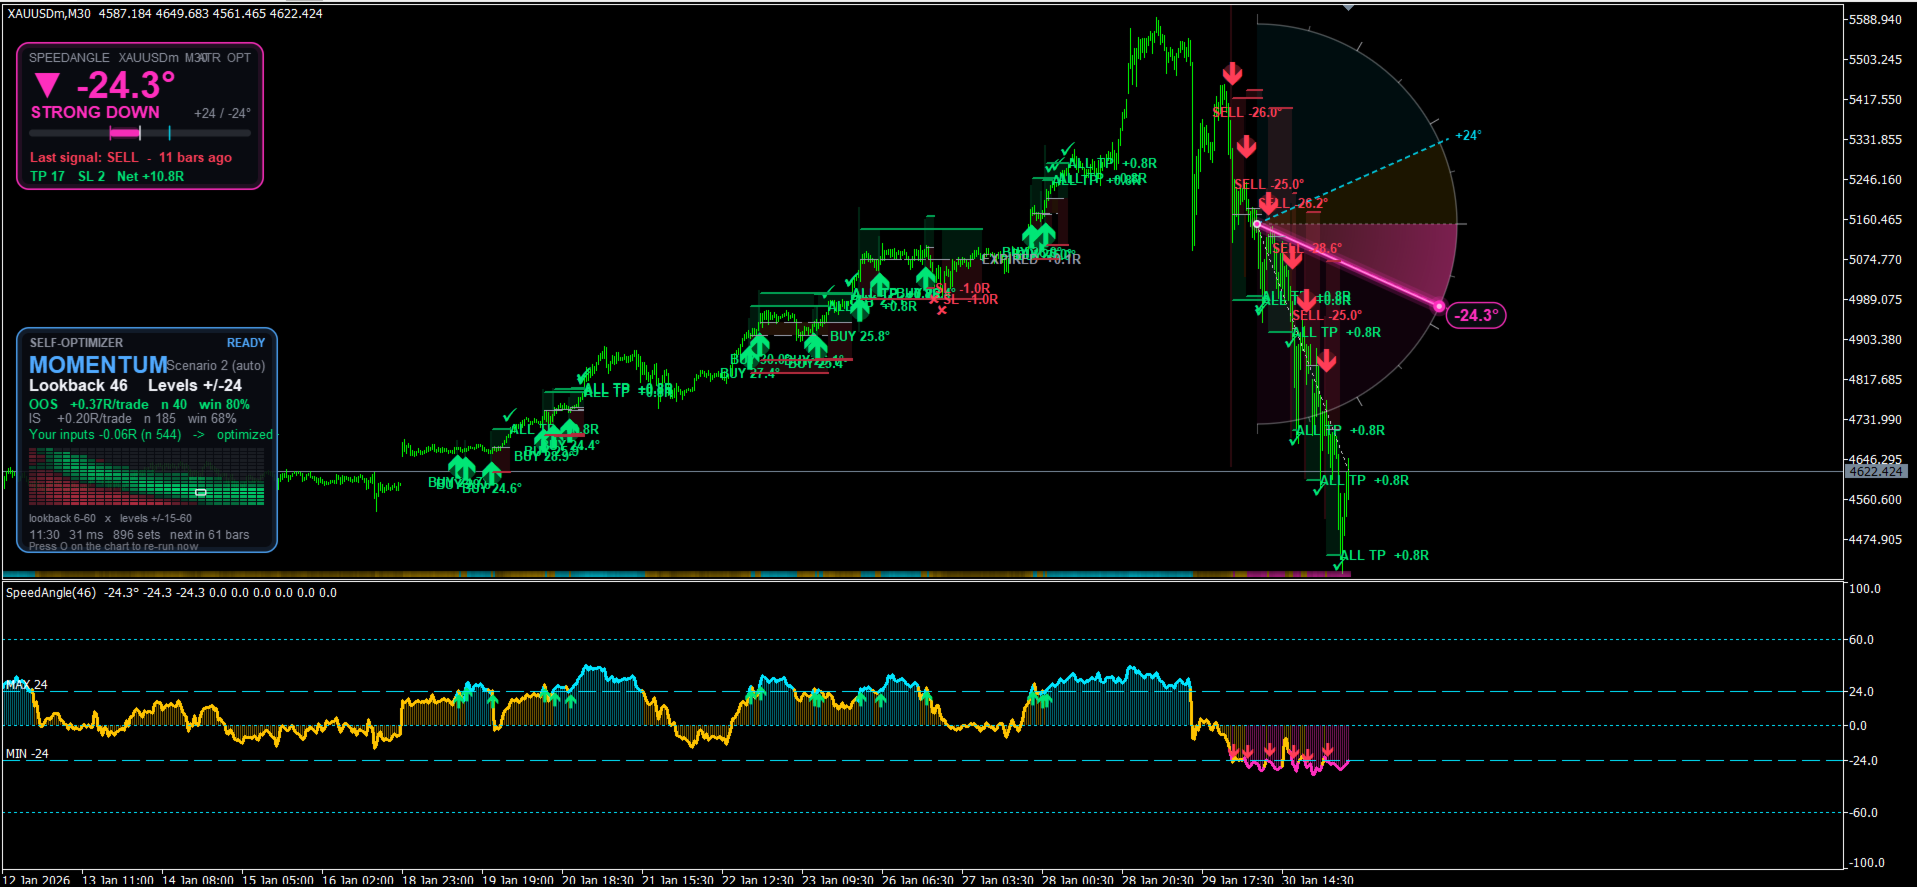
Walk-Forward Optimization Engine: The core algorithm continuously scans thousands of lookback and threshold combinations, strictly segregating data into in-sample and out-of-sample sets. It only adopts a new parameter configuration if it proves mathematically superior in unseen data environments.
-
Quantitative Objective Functions: Instead of chasing pure gross profit, the optimization engine targets institutional stability metrics. Users can optimize for System Quality Number (SQN), Expectancy (Average R-Multiple per trade), or Net R, prioritizing smooth equity progression over isolated, lucky strikes.
-
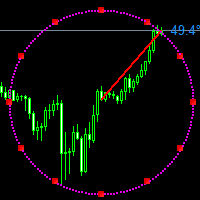
ATR-Normalized Geometry: Standard chart angles are deeply flawed—they repaint and distort based on terminal zoom and vertical scaling. SpeedAngle calculates its vector by normalizing price delta against the Average True Range (ATR). This creates a scale-independent, non-repainting momentum measurement that remains mathematically identical across all screen resolutions.
-
Integrated Trade Analytics: The system does not just print arrows; it actively forward-tests them. It projects dynamic multi-tier Take Profit and Stop Loss levels (calculated via ATR or fixed points) natively on the chart. The integrated HUD continuously tracks live Win Rate, Net R, and Profit Factor based on the current optimized parameter set.
-
Regime Auto-Detection: The engine automatically tests both Mean Reversion and Momentum Breakout scenarios, assigning the optimal structural logic based on current market behavior.
Auto Optimized SpeedAngle removes the manual backtesting loop from the trader's workflow, delivering a mathematically validated, self-adjusting momentum reading designed for rigorous algorithmic deployment.