Articles on machine learning in trading

Creating AI-based trading robots: native integration with Python, matrices and vectors, math and statistics libraries and much more.
Find out how to use machine learning in trading. Neurons, perceptrons, convolutional and recurrent networks, predictive models — start with the basics and work your way up to developing your own AI. You will learn how to train and apply neural networks for algorithmic trading in financial markets.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Exploring Conformal Forecasting of Financial Time Series
In this article, we will consider conformal predictions and the MAPIE library that implements them. This approach is one of the most modern ones in machine learning and allows us to focus on risk management for existing diverse machine learning models. Conformal predictions, by themselves, are not a way to find patterns in data. They only determine the degree of confidence of existing models in predicting specific examples and allow filtering for reliable predictions.


Neural Networks in Trading: Contrastive Pattern Transformer
The Contrastive Transformer is designed to analyze markets both at the level of individual candlesticks and based on entire patterns. This helps improve the quality of market trend modeling. Moreover, the use of contrastive learning to align representations of candlesticks and patterns fosters self-regulation and improves the accuracy of forecasts.


Neural Networks in Trading: Controlled Segmentation (Final Part)
We continue the work started in the previous article on building the RefMask3D framework using MQL5. This framework is designed to comprehensively study multimodal interaction and feature analysis in a point cloud, followed by target object identification based on a description provided in natural language.

Propensity score in causal inference
The article examines the topic of matching in causal inference. Matching is used to compare similar observations in a data set. This is necessary to correctly determine causal effects and get rid of bias. The author explains how this helps in building trading systems based on machine learning, which become more stable on new data they were not trained on. The propensity score plays a central role and is widely used in causal inference.


Neural networks made easy (Part 51): Behavior-Guided Actor-Critic (BAC)
The last two articles considered the Soft Actor-Critic algorithm, which incorporates entropy regularization into the reward function. This approach balances environmental exploration and model exploitation, but it is only applicable to stochastic models. The current article proposes an alternative approach that is applicable to both stochastic and deterministic models.

Neural Networks in Trading: Hybrid Graph Sequence Models (Final Part)
We continue exploring hybrid graph sequence models (GSM++), which integrate the advantages of different architectures, providing high analysis accuracy and efficient distribution of computing resources. These models effectively identify hidden patterns, reducing the impact of market noise and improving forecasting quality.

Neural Networks Made Easy (Part 86): U-Shaped Transformer
We continue to study timeseries forecasting algorithms. In this article, we will discuss another method: the U-shaped Transformer.


Time Evolution Travel Algorithm (TETA)
This is my own algorithm. The article presents the Time Evolution Travel Algorithm (TETA) inspired by the concept of parallel universes and time streams. The basic idea of the algorithm is that, although time travel in the conventional sense is impossible, we can choose a sequence of events that lead to different realities.


Population optimization algorithms: Differential Evolution (DE)
In this article, we will consider the algorithm that demonstrates the most controversial results of all those discussed previously - the differential evolution (DE) algorithm.

Data Science and ML (Part 43): Hidden Patterns Detection in Indicators Data Using Latent Gaussian Mixture Models (LGMM)
Have you ever looked at the chart and felt that strange sensation… that there’s a pattern hidden just beneath the surface? A secret code that might reveal where prices are headed if only you could crack it? Meet LGMM, the Market’s Hidden Pattern Detector. A machine learning model that helps identify those hidden patterns in the market.


Neural Networks Made Easy (Part 85): Multivariate Time Series Forecasting
In this article, I would like to introduce you to a new complex timeseries forecasting method, which harmoniously combines the advantages of linear models and transformers.


Integrate Your Own LLM into EA (Part 5): Develop and Test Trading Strategy with LLMs (II)-LoRA-Tuning
With the rapid development of artificial intelligence today, language models (LLMs) are an important part of artificial intelligence, so we should think about how to integrate powerful LLMs into our algorithmic trading. For most people, it is difficult to fine-tune these powerful models according to their needs, deploy them locally, and then apply them to algorithmic trading. This series of articles will take a step-by-step approach to achieve this goal.


Hidden Markov Models in Machine Learning-Based Trading Systems
Hidden Markov Models (HMMs) are a powerful class of probabilistic models designed to analyze sequential data, where observed events depend on some sequence of unobserved (hidden) states that form a Markov process. The main assumptions of HMM include the Markov property for hidden states, meaning that the probability of transition to the next state depends only on the current state, and the independence of observations given knowledge of the current hidden state.


Data Science and Machine Learning (Part 16): A Refreshing Look at Decision Trees
Dive into the intricate world of decision trees in the latest installment of our Data Science and Machine Learning series. Tailored for traders seeking strategic insights, this article serves as a comprehensive recap, shedding light on the powerful role decision trees play in the analysis of market trends. Explore the roots and branches of these algorithmic trees, unlocking their potential to enhance your trading decisions. Join us for a refreshing perspective on decision trees and discover how they can be your allies in navigating the complexities of financial markets.


Quantitative Analysis of Trends: Collecting Statistics in Python
What is quantitative trend analysis in the Forex market? We collect statistics on trends, their magnitude and distribution across the EURUSD currency pair. How quantitative trend analysis can help you create a profitable trading expert advisor.


Neural Networks in Trading: Node-Adaptive Graph Representation with NAFS
We invite you to get acquainted with the NAFS (Node-Adaptive Feature Smoothing) method, which is a non-parametric approach to creating node representations that does not require parameter training. NAFS extracts features of each node given its neighbors and then adaptively combines these features to form a final representation.


Reimagining Classic Strategies (Part 17): Modelling Technical Indicators
In this discussion, we focus on how we can break the glass ceiling imposed by classical machine learning techniques in finance. It appears that the greatest limitation to the value we can extract from statistical models does not lie in the models themselves — neither in the data nor in the complexity of the algorithms — but rather in the methodology we use to apply them. In other words, the true bottleneck may be how we employ the model, not the model’s intrinsic capability.


Matrix Factorization: A more practical modeling
You might not have noticed that the matrix modeling was a little strange, since only columns were specified, not rows and columns. This looks very strange when reading the code that performs matrix factorizations. If you were expecting to see the rows and columns listed, you might get confused when trying to factorize. Moreover, this matrix modeling method is not the best. This is because when we model matrices in this way, we encounter some limitations that force us to use other methods or functions that would not be necessary if the modeling were done in a more appropriate way.

Neural networks made easy (Part 74): Trajectory prediction with adaptation
This article introduces a fairly effective method of multi-agent trajectory forecasting, which is able to adapt to various environmental conditions.

Implementing Practical Modules from Other Languages in MQL5 (Part 03): Schedule Module from Python, the OnTimer Event on Steroids
The schedule module in Python offers a simple way to schedule repeated tasks. While MQL5 lacks a built-in equivalent, in this article we’ll implement a similar library to make it easier to set up timed events in MetaTrader 5.


A Reinforcement Learning System for Algorithmic Trading in MQL5
The article describes the development of a multi-agent machine learning system for algorithmic trading on MetaTrader 5 based on reinforcement learning. The system has a three-tier architecture: memory neurons store experience, agents make independent decisions, and the collective mind combines them through weighted voting. The system is continuously improved through Q-learning, pruning of ineffective neurons, and evolutionary reduction of exploration.


Feature Engineering for ML (Part 1): Fractional Differentiation — Stationarity Without Memory Loss
Integer differentiation forces a binary choice between stationarity and memory: returns (d=1) are stationary but discard all price-level information; raw prices (d=0) preserve memory but violate ML stationarity assumptions. We implement the fixed-width fractional differentiation (FFD) method from AFML Chapter 5, covering get_weights_ffd (iterative recurrence with threshold cutoff), frac_diff_ffd (bounded dot product per bar), and fracdiff_optimal (binary search for minimum stationary d*).


Neural Networks Made Easy (Part 83): The "Conformer" Spatio-Temporal Continuous Attention Transformer Algorithm
This article introduces the Conformer algorithm originally developed for the purpose of weather forecasting, which in terms of variability and capriciousness can be compared to financial markets. Conformer is a complex method. It combines the advantages of attention models and ordinary differential equations.


MetaTrader 5 Machine Learning Blueprint (Part 13): Implementing Bet Sizing in MQL5
We build a production MQL5 bet‑sizing toolkit: utilities, snippets, and user‑level functions that mirror the Python originals. The methods cover probability‑to‑size mapping with overlap correction, dynamic forecast‑price sizing (calibrated sigmoid/power with limit price), occupancy‑based budgeting, and mixture‑model reserve sizing (EF3M). The result is a signed [−1, ..., 1] position plus diagnostics you can plug directly into order logic.


Overcoming The Limitation of Machine Learning (Part 6): Effective Memory Cross Validation
In this discussion, we contrast the classical approach to time series cross-validation with modern alternatives that challenge its core assumptions. We expose key blind spots in the traditional method—especially its failure to account for evolving market conditions. To address these gaps, we introduce Effective Memory Cross-Validation (EMCV), a domain-aware approach that questions the long-held belief that more historical data always improves performance.


Analyzing Overbought and Oversold Trends Via Chaos Theory Approaches
We determine the overbought and oversold condition of the market according to chaos theory: integrating the principles of chaos theory, fractal geometry and neural networks to forecast financial markets. The study demonstrates the use of the Lyapunov exponent as a measure of market randomness and the dynamic adaptation of trading signals. The methodology includes an algorithm for generating fractal noise, hyperbolic tangent activation, and moment optimization.


CFTC Data Mining in Python and Building an AI Model
Let's try mining CFTC data, downloading COT and TFF reports via Python, connecting all this with MetaTrader 5 quotes and an AI model, and get forecasts. What are COT reports in the Forex market? How to use COT and TFF reports for forecasting?


Swap Arbitrage in Forex: Building a Synthetic Portfolio and Generating a Consistent Swap Flow
Do you want to know how to benefit from the difference in interest rates? This article considers how to use swap arbitrage in Forex to earn stable profit every night, creating a portfolio that is resistant to market fluctuations.

Category Theory in MQL5 (Part 4): Spans, Experiments, and Compositions
Category Theory is a diverse and expanding branch of Mathematics which as of yet is relatively uncovered in the MQL5 community. These series of articles look to introduce and examine some of its concepts with the overall goal of establishing an open library that provides insight while hopefully furthering the use of this remarkable field in Traders' strategy development.

Neural networks made easy (Part 71): Goal-Conditioned Predictive Coding (GCPC)
In previous articles, we discussed the Decision Transformer method and several algorithms derived from it. We experimented with different goal setting methods. During the experiments, we worked with various ways of setting goals. However, the model's study of the earlier passed trajectory always remained outside our attention. In this article. I want to introduce you to a method that fills this gap.

MQL5 Wizard Techniques you should know (Part 51): Reinforcement Learning with SAC
Soft Actor Critic is a Reinforcement Learning algorithm that utilizes 3 neural networks. An actor network and 2 critic networks. These machine learning models are paired in a master slave partnership where the critics are modelled to improve the forecast accuracy of the actor network. While also introducing ONNX in these series, we explore how these ideas could be put to test as a custom signal of a wizard assembled Expert Advisor.

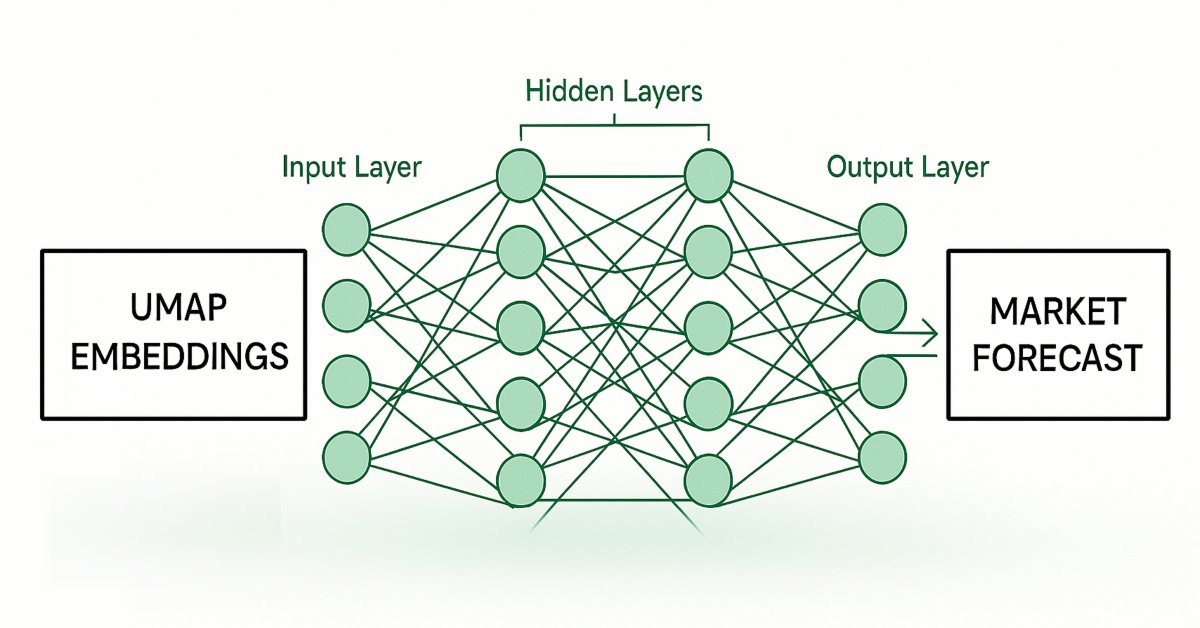
Feature Engineering With Python And MQL5 (Part IV): Candlestick Pattern Recognition With UMAP Regression
Dimension reduction techniques are widely used to improve the performance of machine learning models. Let us discuss a relatively new technique known as Uniform Manifold Approximation and Projection (UMAP). This new technique has been developed to explicitly overcome the limitations of legacy methods that create artifacts and distortions in the data. UMAP is a powerful dimension reduction technique, and it helps us group similar candle sticks in a novel and effective way that reduces our error rates on out of sample data and improves our trading performance.


Example of CNA (Causality Network Analysis), SMOC (Stochastic Model Optimal Control) and Nash Game Theory with Deep Learning
We will add Deep Learning to those three examples that were published in previous articles and compare results with previous. The aim is to learn how to add DL to other EA.

MQL5 Wizard Techniques you should know (Part 72): Using Patterns of MACD and the OBV with Supervised Learning
We follow up on our last article, where we introduced the indicator pair of the MACD and the OBV, by looking at how this pairing could be enhanced with Machine Learning. MACD and OBV are a trend and volume complimentary pairing. Our machine learning approach uses a convolution neural network that engages the Exponential kernel in sizing its kernels and channels, when fine-tuning the forecasts of this indicator pairing. As always, this is done in a custom signal class file that works with the MQL5 wizard to assemble an Expert Advisor.


Neuro-Structural Trading Engine — NSTE (Part I): How to Build a Prop-Firm-Safe Multi-Account System
This article lays the system architecture for a multi‑account algorithmic trading setup that operates cryptocurrency CFDs on MetaTrader 5 while respecting prop‑firm constraints. It defines three core principles—fixed dollar risk, one script per account, and centralized configuration—then details the Python–MQL5 split, the 60‑second processing loop, and JSON-based signaling. Readers get practical lot‑size computation, safety checks, and position management patterns for reliable deployment.

Neural Networks in Trading: A Complex Trajectory Prediction Method (Traj-LLM)
In this article, I would like to introduce you to an interesting trajectory prediction method developed to solve problems in the field of autonomous vehicle movements. The authors of the method combined the best elements of various architectural solutions.


Crystal Structure Algorithm (CryStAl)
This article presents two versions of the Crystal Structure Algorithm: the original and the modified version. The Crystal Structure Algorithm (CryStAl), published in 2021 and inspired by the physics of crystal structures, was positioned as a parameter-free metaheuristic for global optimization. However, testing revealed a critical problem with the algorithm. A modified version, CryStAlm, is also presented; it addresses the original's key shortcomings.


Generative Adversarial Networks (GANs) for Synthetic Data in Financial Modeling (Part 1): Introduction to GANs and Synthetic Data in Financial Modeling
This article introduces traders to Generative Adversarial Networks (GANs) for generating Synthetic Financial data, addressing data limitations in model training. It covers GAN basics, python and MQL5 code implementations, and practical applications in finance, empowering traders to enhance model accuracy and robustness through synthetic data.


Neural Networks Made Easy (Part 95): Reducing Memory Consumption in Transformer Models
Transformer architecture-based models demonstrate high efficiency, but their use is complicated by high resource costs both at the training stage and during operation. In this article, I propose to get acquainted with algorithms that allow to reduce memory usage of such models.

Neural networks made easy (Part 42): Model procrastination, reasons and solutions
In the context of reinforcement learning, model procrastination can be caused by several reasons. The article considers some of the possible causes of model procrastination and methods for overcoming them.