Articles on machine learning in trading

Creating AI-based trading robots: native integration with Python, matrices and vectors, math and statistics libraries and much more.
Find out how to use machine learning in trading. Neurons, perceptrons, convolutional and recurrent networks, predictive models — start with the basics and work your way up to developing your own AI. You will learn how to train and apply neural networks for algorithmic trading in financial markets.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

Integrating ML models with the Strategy Tester (Part 3): Managing CSV files (II)
This material provides a complete guide to creating a class in MQL5 for efficient management of CSV files. We will see the implementation of methods for opening, writing, reading, and transforming data. We will also consider how to use them to store and access information. In addition, we will discuss the limitations and the most important aspects of using such a class. This article ca be a valuable resource for those who want to learn how to process CSV files in MQL5.


Pipelines in MQL5
In this piece, we look at a key data preparation step for machine learning that is gaining rapid significance. Data Preprocessing Pipelines. These in essence are a streamlined sequence of data transformation steps that prepare raw data before it is fed to a model. As uninteresting as this may initially seem to the uninducted, this ‘data standardization’ not only saves on training time and execution costs, but it goes a long way in ensuring better generalization. In this article we are focusing on some SCIKIT-LEARN preprocessing functions, and while we are not exploiting the MQL5 Wizard, we will return to it in coming articles.

Category Theory in MQL5 (Part 3)
Category Theory is a diverse and expanding branch of Mathematics which as of yet is relatively uncovered in the MQL5 community. These series of articles look to introduce and examine some of its concepts with the overall goal of establishing an open library that provides insight while hopefully furthering the use of this remarkable field in Traders' strategy development.

Neural Networks in Trading: Hierarchical Vector Transformer (HiVT)
We invite you to get acquainted with the Hierarchical Vector Transformer (HiVT) method, which was developed for fast and accurate forecasting of multimodal time series.


Data Science and Machine Learning (Part 17): Money in the Trees? The Art and Science of Random Forests in Forex Trading
Discover the secrets of algorithmic alchemy as we guide you through the blend of artistry and precision in decoding financial landscapes. Unearth how Random Forests transform data into predictive prowess, offering a unique perspective on navigating the complex terrain of stock markets. Join us on this journey into the heart of financial wizardry, where we demystify the role of Random Forests in shaping market destiny and unlocking the doors to lucrative opportunities


Dingo Optimization Algorithm Modification (DOAm)
The custom modification of the Dingo algorithm presented in the article has raised the bar for finding the best optimization algorithm. Are even better results possible?

Neural Networks Made Easy (Part 94): Optimizing the Input Sequence
When working with time series, we always use the source data in their historical sequence. But is this the best option? There is an opinion that changing the sequence of the input data will improve the efficiency of the trained models. In this article I invite you to get acquainted with one of the methods for optimizing the input sequence.


MetaTrader 5 Machine Learning Blueprint (Part 11): Kelly Criterion, Prop Firm Integration, and CPCV Dynamic Backtesting
The bet-sizing signal from Part 10 is concurrency-corrected but carries no payoff-ratio adjustment, no response to a hard drawdown budget, and no validation across combinatorial paths. This article covers three additions: a two-stage architecture in which a Kelly payoff multiplier is applied on top of get_signal, preserving the concurrency correction while incorporating win/loss asymmetry; a prop firm integration layer that calibrates the sigmoid w parameter continuously from the remaining drawdown budget under FundedNext Stellar 2-Step rules; and a CPCV backtest framework that simulates a fresh account state across all φ[N, k] paths, producing a Sharpe distribution and a PBO audit.


Data Science and Machine Learning (Part 19): Supercharge Your AI models with AdaBoost
AdaBoost, a powerful boosting algorithm designed to elevate the performance of your AI models. AdaBoost, short for Adaptive Boosting, is a sophisticated ensemble learning technique that seamlessly integrates weak learners, enhancing their collective predictive strength.


Data Science and ML (Part 27): Convolutional Neural Networks (CNNs) in MetaTrader 5 Trading Bots — Are They Worth It?
Convolutional Neural Networks (CNNs) are renowned for their prowess in detecting patterns in images and videos, with applications spanning diverse fields. In this article, we explore the potential of CNNs to identify valuable patterns in financial markets and generate effective trading signals for MetaTrader 5 trading bots. Let us discover how this deep machine learning technique can be leveraged for smarter trading decisions.


Integrate Your Own LLM into EA (Part 5): Develop and Test Trading Strategy with LLMs(I)-Fine-tuning
With the rapid development of artificial intelligence today, language models (LLMs) are an important part of artificial intelligence, so we should think about how to integrate powerful LLMs into our algorithmic trading. For most people, it is difficult to fine-tune these powerful models according to their needs, deploy them locally, and then apply them to algorithmic trading. This series of articles will take a step-by-step approach to achieve this goal.

Feature Engineering With Python And MQL5 (Part I): Forecasting Moving Averages For Long-Range AI Models
The moving averages are by far the best indicators for our AI models to predict. However, we can improve our accuracy even further by carefully transforming our data. This article will demonstrate, how you can build AI Models capable of forecasting further into the future than you may currently be practicing without significant drops to your accuracy levels. It is truly remarkable, how useful the moving averages are.

Population optimization algorithms: Cuckoo Optimization Algorithm (COA)
The next algorithm I will consider is cuckoo search optimization using Levy flights. This is one of the latest optimization algorithms and a new leader in the leaderboard.


Neural Networks in Trading: An Agent with Layered Memory (Final Part)
We continue our work on creating the FinMem framework, which uses layered memory approaches that mimic human cognitive processes. This allows the model not only to effectively process complex financial data but also to adapt to new signals, significantly improving the accuracy and effectiveness of investment decisions in dynamically changing markets.


Neural networks made easy (Part 44): Learning skills with dynamics in mind
In the previous article, we introduced the DIAYN method, which offers the algorithm for learning a variety of skills. The acquired skills can be used for various tasks. But such skills can be quite unpredictable, which can make them difficult to use. In this article, we will look at an algorithm for learning predictable skills.


Trading Insights Through Volume: Moving Beyond OHLC Charts
Algorithmic trading system that combines volume analysis with machine learning techniques, specifically LSTM neural networks. Unlike traditional trading approaches that primarily focus on price movements, this system emphasizes volume patterns and their derivatives to predict market movements. The methodology incorporates three main components: volume derivatives analysis (first and second derivatives), LSTM predictions for volume patterns, and traditional technical indicators.


Build a Remote Forex Risk Management System in Python
We are making a remote professional risk manager for Forex in Python, deploying it on the server step by step. In the course of the article, we will understand how to programmatically manage Forex risks, and how not to waste a Forex deposit any more.

Reimagining Classic Strategies (Part VI): Multiple Time-Frame Analysis
In this series of articles, we revisit classic strategies to see if we can improve them using AI. In today's article, we will examine the popular strategy of multiple time-frame analysis to judge if the strategy would be enhanced with AI.


Neural networks made easy (Part 38): Self-Supervised Exploration via Disagreement
One of the key problems within reinforcement learning is environmental exploration. Previously, we have already seen the research method based on Intrinsic Curiosity. Today I propose to look at another algorithm: Exploration via Disagreement.

Neural Networks in Trading: A Multi-Agent Self-Adaptive Model (Final Part)
In the previous article, we introduced the multi-agent self-adaptive framework MASA, which combines reinforcement learning approaches and self-adaptive strategies, providing a harmonious balance between profitability and risk in turbulent market conditions. We have built the functionality of individual agents within this framework. In this article, we will continue the work we started, bringing it to its logical conclusion.


ARIMA Forecasting Indicator in MQL5
In this article we are implementing ARIMA forecasting indicator in MQL5. It examines how the ARIMA model generates forecasts, its applicability to the Forex market and the stock market in general. It also explains what AR autoregression is, how autoregressive models are used for forecasting, and how the autoregression mechanism works.

Seasonality Filtering and time period for Deep Learning ONNX models with python for EA
Can we benefit from seasonality when creating models for Deep Learning with Python? Does filtering data for the ONNX models help to get better results? What time period should we use? We will cover all of this over this article.

Neural Networks in Trading: Hyperbolic Latent Diffusion Model (Final Part)
The use of anisotropic diffusion processes for encoding the initial data in a hyperbolic latent space, as proposed in the HypDIff framework, assists in preserving the topological features of the current market situation and improves the quality of its analysis. In the previous article, we started implementing the proposed approaches using MQL5. Today we will continue the work we started and will bring it to its logical conclusion.

Billiards Optimization Algorithm (BOA)
The BOA method is inspired by the classic game of billiards and simulates the search for optimal solutions as a game with balls trying to fall into pockets representing the best results. In this article, we will consider the basics of BOA, its mathematical model, and its efficiency in solving various optimization problems.

Neural networks made easy (Part 47): Continuous action space
In this article, we expand the range of tasks of our agent. The training process will include some aspects of money and risk management, which are an integral part of any trading strategy.

Neural networks made easy (Part 43): Mastering skills without the reward function
The problem of reinforcement learning lies in the need to define a reward function. It can be complex or difficult to formalize. To address this problem, activity-based and environment-based approaches are being explored to learn skills without an explicit reward function.


Neural networks made easy (Part 50): Soft Actor-Critic (model optimization)
In the previous article, we implemented the Soft Actor-Critic algorithm, but were unable to train a profitable model. Here we will optimize the previously created model to obtain the desired results.


Population optimization algorithms: Nelder–Mead, or simplex search (NM) method
The article presents a complete exploration of the Nelder-Mead method, explaining how the simplex (function parameter space) is modified and rearranged at each iteration to achieve an optimal solution, and describes how the method can be improved.


MQL5 Wizard Techniques you should know (Part 08): Perceptrons
Perceptrons, single hidden layer networks, can be a good segue for anyone familiar with basic automated trading and is looking to dip into neural networks. We take a step by step look at how this could be realized in a signal class assembly that is part of the MQL5 Wizard classes for expert advisors.

Integrate Your Own LLM into EA (Part 4): Training Your Own LLM with GPU
With the rapid development of artificial intelligence today, language models (LLMs) are an important part of artificial intelligence, so we should think about how to integrate powerful LLMs into our algorithmic trading. For most people, it is difficult to fine-tune these powerful models according to their needs, deploy them locally, and then apply them to algorithmic trading. This series of articles will take a step-by-step approach to achieve this goal.


Algorithmic Arbitrage Trading Using Graph Theory
In this article, triangular arbitrage is presented as a problem of finding cycles in a directed graph, where the vertices are currencies and the edges are currency pairs with weight rates. Profitable cycle: product of weights >1. Our Floyd-Warshall and DFS algorithms find optimal currency exchange paths that return to the starting point with a profit.

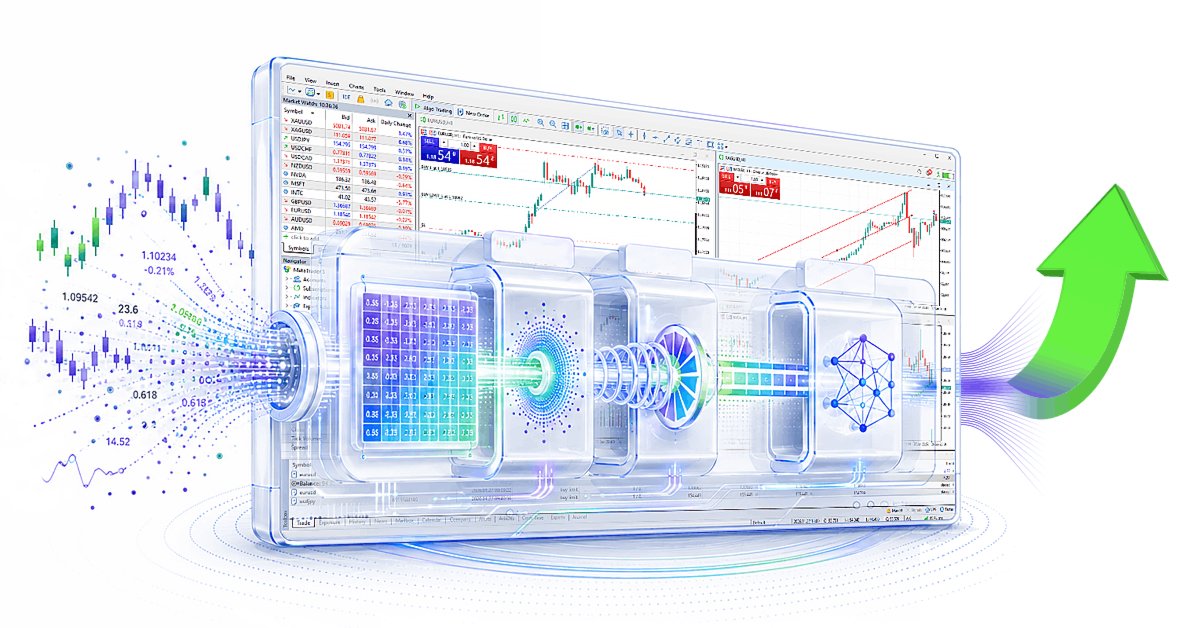
From Matrices to Models: How to Build an ML Pipeline in MQL5 and Export It to ONNX
The article describes the arrangement of a coordinated ML pipeline in MetaTrader 5 with separation of roles: Python trains and exports the model to ONNX, MQL5 reproduces normalization and PCA via matrix/vector and performs inference. This approach makes the model's inputs stable and verifiable, and the MetaTrader 5 strategy tester provides metrics for analyzing the system behavior.


Neural networks made easy (Part 48): Methods for reducing overestimation of Q-function values
In the previous article, we introduced the DDPG method, which allows training models in a continuous action space. However, like other Q-learning methods, DDPG is prone to overestimating Q-function values. This problem often results in training an agent with a suboptimal strategy. In this article, we will look at some approaches to overcome the mentioned issue.


Neural Networks in Trading: Enhancing Transformer Efficiency by Reducing Sharpness (Final Part)
SAMformer offers a solution to the key drawbacks of Transformer models in long-term time series forecasting, such as training complexity and poor generalization on small datasets. Its shallow architecture and sharpness-aware optimization help avoid suboptimal local minima. In this article, we will continue to implement approaches using MQL5 and evaluate their practical value.

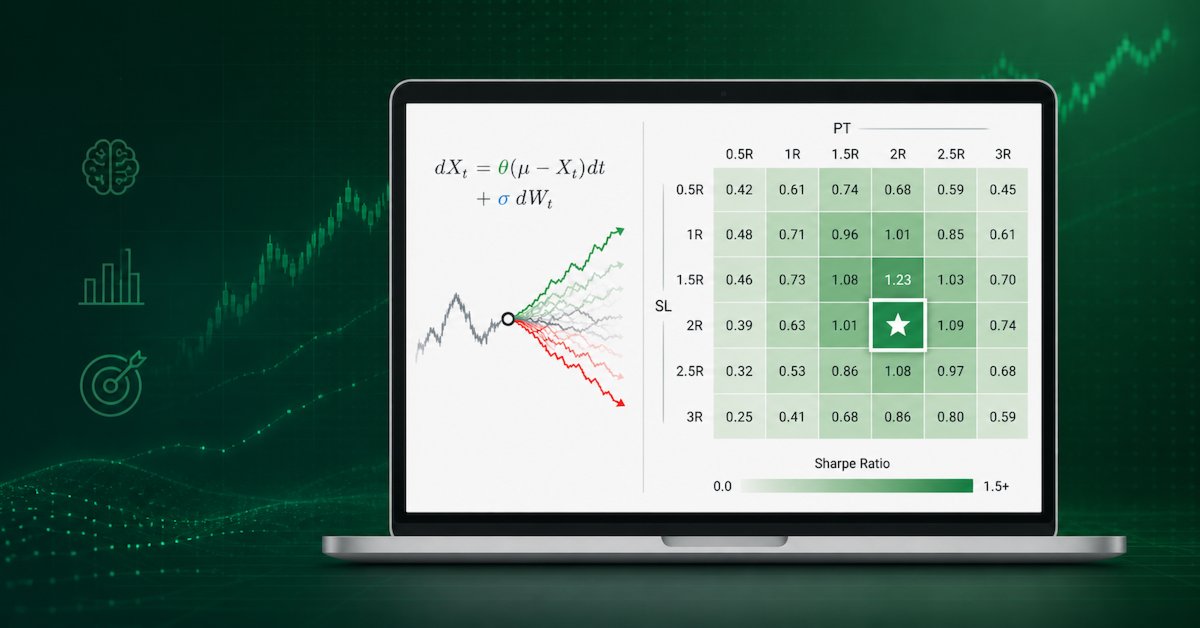
MetaTrader 5 Machine Learning Blueprint (Part 15): How to Calibrate Profit-Taking and Stop-Loss Targets from Synthetic Data
This article applies the Optimal Trading Rule from AFML Chapter 13 to set profit targets and stop-losses without in-sample calibration. We model post-entry P&L with a discrete Ornstein–Uhlenbeck process, run a 100,000-path search, and implement Python, multiprocessing, and a Numba @njit parallel kernel (242× faster). The result is an optimal (PT, SL) under three forecast specifications, constrained by the prop-firm daily loss limit.


Reimagining Classic Strategies (Part III): Forecasting Higher Highs And Lower Lows
In this series article, we will empirically analyze classic trading strategies to see if we can improve them using AI. In today's discussion, we tried to predict higher highs and lower lows using the Linear Discriminant Analysis model.


Mining Central Bank Balance Sheet Data to Get a Picture of Global Liquidity
Mining central bank balance sheet data provides a picture of global liquidity in the Forex market and key currencies. We combine data from the Fed, ECB, BOJ and PBoC into a composite index and use machine learning to uncover hidden patterns. This approach turns raw data into real trading signals by combining fundamental and technical analysis.

Using association rules in Forex data analysis
How to apply predictive rules of supermarket retail analytics to the real Forex market? How are purchases of cookies, milk and bread related to stock exchange transactions? The article discusses an innovative approach to algorithmic trading based on the use of association rules.


Neural Networks in Trading: Disentangling Structured Components (Encoder)
We invite you to explore the next stage in implementing the SCNN framework, which combines flexibility and interpretability, allowing structural components of a time series to be identified precisely. The article provides a detailed explanation of the mechanisms of adaptive normalization and attention, which ensure the model's resilience to changing market conditions.

Neural Networks in Trading: Using Language Models for Time Series Forecasting
We continue to study time series forecasting models. In this article, we get acquainted with a complex algorithm built on the use of a pre-trained language model.