Articles on data analysis and statistics in MQL5

Articles on mathematical models and laws of probability are interesting for many traders. Mathematics is the basis of technical indicators, and statistics is required to analyze trading results and develop strategies.
Read about the fuzzy logic, digital filters, market profile, Kohonen maps, neural gas and many other tools that can be used for trading.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


MQL5 Trading Tools (Part 37): Adding a Per-Object Property-Editing Ribbon to the Canvas Drawing Layer
We add a descriptor-driven property stack and a floating ribbon that binds to the current selection on the drawing layer. The article covers the descriptor list for each tool, the engine get/set API with snapshot-and-restore live preview, and widget renderers for color, opacity, line width, line style, fonts, and level visibility. You get in-place, real-time editing of object appearance via a compact, draggable panel.


Community of Scientists Optimization (CoSO): Theory
Secrets of effective optimization of trading strategies in metaheuristic approaches. Community of Scientists Optimization is a new population-based algorithm inspired by the mechanisms of the scientific community. Unlike traditional nature-inspired metaphors, CoSO models unique aspects of human scientific activity: publishing results in journals, competing for grants, and forming research teams.


Introduction to MQL5 (Part 39): Beginner Guide to File Handling in MQL5 (I)
This article introduces file handling in MQL5 using a practical, project-based workflow. You will use FileSelectDialog to choose or create a CSV file, open it with FileOpen, and write structured account headers such as account name, balance, login, date range, and last update. The result is a clear foundation for a reusable trading journal and safe file operations in MetaTrader 5.


Creating an HTML Dashboard for Strategy Tester and Prop Firm Challenge Analysis in MQL5
This article demonstrates how to build a reusable prop‑firm evaluation module for MQL5 Expert Advisors and export results to an HTML dashboard. The module monitors balance and equity during backtests, simulates single or rolling challenges, checks profit target, daily and overall drawdown, and minimum trading days, then outputs both a terminal summary and a browser‑readable report.


From Novice to Expert: Animated News Headline Using MQL5 (V)—Event Reminder System
In this discussion, we’ll explore additional advancements as we integrate refined event‑alerting logic for the economic calendar events displayed by the News Headline EA. This enhancement is critical—it ensures users receive timely notifications a short time before key upcoming events. Join this discussion to discover more.


Forecasting a Conditional Distribution Using MLP
In this article, we will consider an MLP-based regression model that predicts not only the conditional expectation but also the conditional variance. In other words, we will train our network to predict the entire distribution of future prices based on the input feature vector. But for this purpose we will have to implement our own loss function.


MQL5 Trading Tools (Part 38): Adding a Tabbed Settings Window for Editing Object Properties
We add a tabbed settings window opened from the ribbon and bound to the selected object. The tabs — Style, Text, Coordinates, and Visibility — are built from the same descriptor system, with scrolling, per-level rows, and shared color/width/style popovers. The article covers layout, rendering, interaction, and inline price/time and numeric editing. You get one place to edit every property with live preview and commit-or-discard on close.


Execution Cost and Slippage Sensitivity Analyzer
Backtests often understate spread, commission, and slippage. This MQL5 analyzer loads closing deals and simulates rising execution costs to measure robustness. It computes the breakeven cost per deal, the cushion over an assumed cost, the net profit and profit factor at that cost, and how many winners turn into losers, then summarizes the result with an A+ to F grade and targeted guidance.


Building a Future Swing Projection Indicator in MQL5
We implement a Future Swing Projection indicator in MQL5 that analyzes historical swing structure and estimates the next move from recent price behavior. It locates six alternating swing points, measures five completed legs, and uses their average distance to project a target five bars ahead. The indicator draws swing legs, a projection line, ATR‑based support and resistance zones, and a label with the projected price to keep the process rule‑based and reproducible.


Bayesian Online Change-Point Detection (BOCPD) in MQL5: One Regime-Break Signal, Three Ways to Use It
This article delivers Bayesian Online Change-Point Detection as a single, dependency-free MQL5 class that maintains a per-bar, causal probability of a regime break. We use it three ways: a live monitor, a moving average that flushes on breaks, and a risk overlay with a matched-frequency random control. Readers get a reusable primitive to watch structural change, adapt indicators, and gate exposure after detected shifts.


Market Simulation: Position View (V)
Despite what was shown in the previous article, all of this may seem simple at first. In reality, several problems remain, along with many tasks that still need to be completed. You, dear reader, may imagine that everything is easy and straightforward. Out of inexperience, you may simply accept whatever is presented to you. And that is a mistake you should try to avoid. Even worse is trying to use something without truly understanding what exactly you are using. Beginners often pass through a copy-and-paste stage. If you do not want to remain stuck at that stage forever, you should learn how to use certain tools. One of the tools most often used by programmers is documentation. The second is testing, supported by log files. Here we will see how to do this.


Building Volatility Models in MQL5 (Part III): Implementing the SLSQP Algorithm for Model Estimation
An SLSQP optimizer is implemented in MQL5 to resolve parameter discrepancies between a volatility library and Python's ARCH module. The article details constraint handling, gradient options, configuration, and convergence controls and shows how to integrate the solver into existing code. Practical examples and comparisons demonstrate matched log‑likelihoods and parameters on shared datasets.


Color Harmony Algorithm (CHA)
We take a closer look at the Color Harmony Algorithm (CHA) — a meta-heuristic optimization method based on Munsell's theory of color harmony. We explore the structure of the hue circle, harmony templates, the alternation between the concentration and dispersion phases, and the role of solution memory. From a theoretical framework to a working implementation in MQL5 and unbiased testing on a standard benchmark.


Atmosphere Clouds Model Optimization (ACMO): Theory
The article is devoted to the metaheuristic Atmosphere Clouds Model Optimization (ACMO) algorithm, which simulates the behavior of clouds to solve optimization problems. The algorithm uses the principles of cloud generation, movement and propagation, adapting to the "weather conditions" in the solution space. The article reveals how the algorithm's meteorological simulation finds optimal solutions in a complex possibility space and describes in detail the stages of ACMO operation, including "sky" preparation, cloud birth, cloud movement, and rain concentration.


MQL5 Trading Tools (Part 27): Rendering Parametric Butterfly Curve on Canvas
In this article, we explore the butterfly curve, a parametric mathematical equation, and render it visually on a MQL5 canvas. We build an interactive display with a draggable, resizable canvas window, supersampled curve rendering, gradient backgrounds, and a color-segmented legend. By the end, we have a fully functional visual tool that plots the butterfly curve directly on the MetaTrader 5 chart.


Symbolic Price Forecasting Equation Using SymPy
The article describes an interesting approach to algorithmic trading based on symbolic mathematical equations instead of traditional machine learning "black boxes". The author demonstrates how to transform opaque neural networks into readable mathematical equations using the SymPy library and polynomial regression, allowing for a full understanding of the logic behind trading decisions. The approach combines the computational power of ML with the transparency of classical methods, giving traders the ability to analyze, adjust, and adapt models in real time.


Bivariate Copulae in MQL5 (Part 3): Implementation and Tuning of Mixed Copula Models in MQL5
The article extends our copula toolkit with mixed copulas implemented natively in MQL5. We construct Clayton–Frank–Gumbel and Clayton–Student–t–Gumbel mixtures, estimate them via EM, and enable sparsity control through SCAD with cross‑validation. Provided scripts tune hyperparameters, compare mixtures using information criteria, and save trained models. Practitioners can apply these components to capture asymmetric tail dependence and embed the selected model in indicators or Expert Advisors.


Introduction to MQL5 (Part 41): Beginner Guide to File Handling in MQL5 (III)
Learn how to read a CSV file in MQL5 and organize its trading data into dynamic arrays. This article shows step by step how to count file elements, store all data in a single array, and separate each column into dedicated arrays, laying the foundation for advanced analysis and trading performance visualization.


Developing a Multi-Currency Expert Advisor (Part 28): Adding a Position Closing Manager
When running multiple strategies in parallel, you may want to periodically close all open positions and start the strategies over again. The existing code only allows this behavior to be implemented through manual intervention. Let's try to automate this part.


MQL5 Trading Tools (Part 25): Expanding to Multiple Distributions with Interactive Switching
In this article, we expand the MQL5 graphing tool to support seventeen statistical distributions with interactive cycling via a header switch icon. We add type-specific data loading, discrete and continuous histogram computation, and theoretical density functions for each model, with dynamic titles, axis labels, and parameter panels that adapt automatically. The result lets you overlay distribution models on the same sample and compare fit across families without reloading the tool.


Quantum Neural Network in MQL5 (Part II): Training a Neural Network with Backpropagation on ALGLIB Markov Matrices
The article presents an innovative quantum neural network architecture for algorithmic trading that combines the principles of quantum mechanics with modern machine learning methods. The system includes quantum effects (resonance, interference, decoherence), multi-level memory of different time scales, Markov chains with the ALGLIB library, and adaptive parameter control. The full implementation is done in MQL5 using the built-in matrix/vector types, which removes implementation barriers in MetaTrader 5.


Market Microstructure in MQL5 (Part 2): Measuring long memory in MQL5 with Hurst estimators
Part 2 focuses on practical long-memory detection for intraday data. Three complementary Hurst estimators are implemented and combined into a confidence‑weighted composite, with confidence tied to valid regression scales. The final H and confidence populate the shared analysis struct, enabling indicators to act only when H departs from the neutral 0.40–0.60 band and to select trend‑following above 0.60 or mean‑reversion below 0.40.


MQL5 Trading Tools (Part 28): Filling Sweep Polygons for Butterfly Curve in MQL5
We expand the capabilities of the MetaTrader 5 butterfly curve canvas by adding multi-layered wing fills, vein lines, scale dots, and a full body (abdomen, thorax, head, eyes, antennae). This article implements polygon fills with vertical and radial gradients, as well as filled circles and ellipses, all using supersampling antialiasing. You will also receive reusable MQL5 helper functions and a rendering order that transforms a simple curve into a customizable, detailed chart illustration.


Implementing Practical Modules from Other Languages in MQL5 (Part 05): The Logging module from Python, Log Like a Pro
Integrating Python's logging module with MQL5 empowers traders with a systematic logging approach, simplifying the process of monitoring, debugging, and documenting trading activities. This article explains the adaptation process, offering traders a powerful tool for maintaining clarity and organization in trading software development.


Developing a Replay System (Part 57): Understanding a Test Service
One point to note: although the service code is not included in this article and will only be provided in the next one, I'll explain it since we'll be using that same code as a springboard for what we're actually developing. So, be attentive and patient. Wait for the next article, because every day everything becomes more interesting.


How to Train an MLP Using Markov Chain Features in MQL5
The article describes the two-level MarkovMLPOscillator indicator: a three-state Markov chain uses historical data to construct a transition matrix and generate 15 probabilistic features for each bar, and an MLP is trained on these features to predict price direction at a specified forecast horizon. The article covers feature generation, the validation procedure using a holdout set, and parameter settings. The result is an interpretable oscillator with a color histogram, a smoothed signal, and a display of the current transition matrix.


Biogeography-Based Optimization (BBO)
Biogeography-Based Optimization (BBO) is an elegant global optimization method inspired by natural processes of species migration between islands within archipelagos. The algorithm is based on a simple yet powerful idea: high-quality solutions actively share their characteristics, while low-quality ones actively adopt new features, creating a natural flow of information from the best solutions to the worst. A unique adaptive mutation operator provides an excellent balance between exploration and exploitation. BBO demonstrates high efficiency on a variety of tasks.

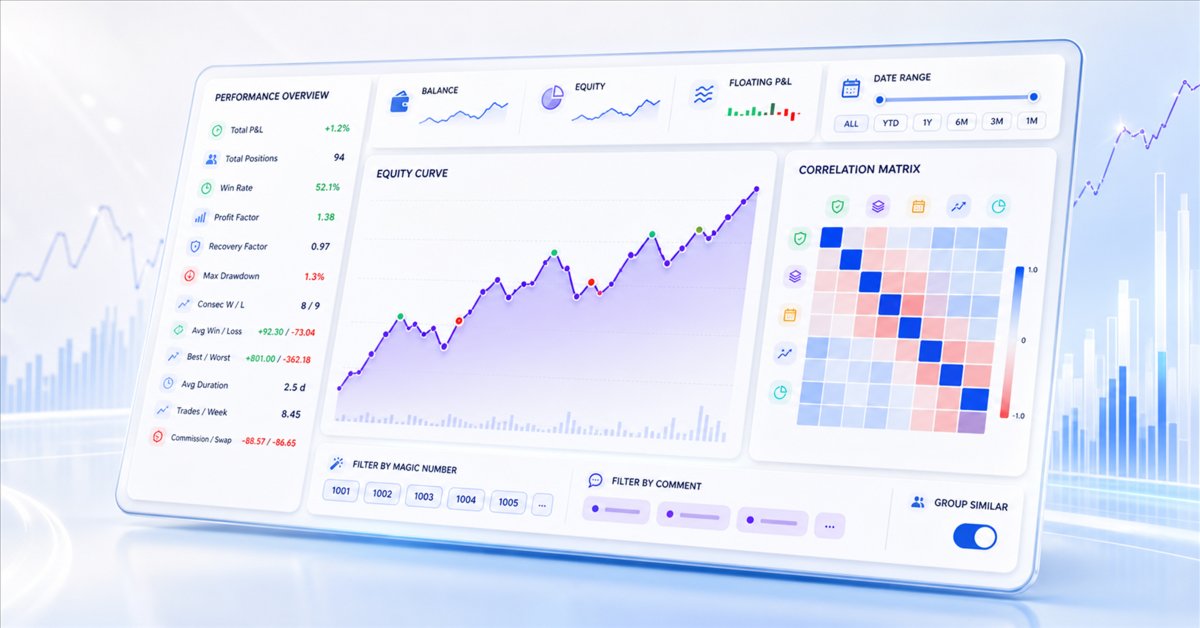
Creating an Interactive Portfolio Analyzer Dashboard with CCanvas in MQL5
This article presents a standalone Portfolio Analyzer dashboard implemented as an Expert Advisor for MetaTrader 5. It reads account deal history, reconstructs closed positions, and attributes results by magic number or normalized comment to deliver clear per-strategy metrics. The interface provides a vector equity curve, date filters, and strategy selectors, plus a Pearson correlation matrix to reveal strategy redundancy. You can attach it to a separate chart without modifying existing trading EAs.


Overcoming Accessibility Problems in MQL5 Trading Tools (Part IV): Remote voice trading
Learn a practical way to execute MetaTrader 5 trades from Telegram voice notes using a Python middleware and an MQL5 EA acting as an HTTP client. The article covers architecture, WebRequest polling, in-memory queuing, JSON parsing with null-terminator stripping, and a constrained command grammar with a 0.001-lot default. You will configure the environment and validate round‑trip latency suitable for mobile data connections.


Exploring Regression Models for Causal Inference and Trading
The article explores the possibility of using regression models in algorithmic trading. Regression models, unlike binary classification, allow for the creation of more flexible trading strategies by quantifying predicted price changes.

MQL5 Trading Toolkit (Part 6): Expanding the History Management EX5 Library with the Last Filled Pending Order Functions
Learn how to create an EX5 module of exportable functions that seamlessly query and save data for the most recently filled pending order. In this comprehensive step-by-step guide, we will enhance the History Management EX5 library by developing dedicated and compartmentalized functions to retrieve essential properties of the last filled pending order. These properties include the order type, setup time, execution time, filling type, and other critical details necessary for effective pending orders trade history management and analysis.


Gaussian Processes in Machine Learning (Part 1): Classification Model in MQL5
The article considers the classification model of Gaussian processes. We will start by studying its theoretical principles moving on to the practical development of the GP library in MQL5.


Symbolic Aggregate Approximation (SAX) in MQL5: Historical Analog Search and Forecasting
Symbolic Aggregate approXimation (SAX) encodes price windows as short words to enable fast, sound similarity search on history. We implement SAX in pure MQL5, including Gaussian breakpoints, PAA, and the lower-bounding MINDIST, and validate it with a test harness. An indicator applies a no-lookahead, two-stage search, summarizes forward paths in ATR units, and draws a forecast fan, explicitly indicating when the sample shows no edge.


MQL5 Wizard Techniques you should know (Part 10). The Unconventional RBM
Restrictive Boltzmann Machines are at the basic level, a two-layer neural network that is proficient at unsupervised classification through dimensionality reduction. We take its basic principles and examine if we were to re-design and train it unorthodoxly, we could get a useful signal filter.


Kohonen Self-Organizing Maps in an MQL5 Expert Advisor
Kohonen's self-organizing maps transform the chaos of market data into an ordered two-dimensional map, where similar patterns are grouped together. The article demonstrates a complete implementation of a SOM in an MQL5 Expert Advisor with 400 neurons and continuous learning. We break down the Best Matching Unit search algorithm, weight updates using a Gaussian neighborhood function, integration with quantum effects, and the generation of trading signals. The code is open-source, the math is clear, and the results are verifiable.


Community of Scientists Optimization (CoSO): Practice
We resume the topic of optimization by the scientific community. CoSO should not be viewed as a ready-made solution, but as a promising research platform. With proper development, CoSO can find its niche in tasks where adaptability and resilience to change are important, and computation time is not critical.


Population optimization algorithms: Bacterial Foraging Optimization - Genetic Algorithm (BFO-GA)
The article presents a new approach to solving optimization problems by combining ideas from bacterial foraging optimization (BFO) algorithms and techniques used in the genetic algorithm (GA) into a hybrid BFO-GA algorithm. It uses bacterial swarming to globally search for an optimal solution and genetic operators to refine local optima. Unlike the original BFO, bacteria can now mutate and inherit genes.


Developing a Replay System (Part 60): Playing the Service (I)
We have been working on just the indicators for a long time now, but now it's time to get the service working again and see how the chart is built based on the data provided. However, since the whole thing is not that simple, we will have to be attentive to understand what awaits us ahead.


Market Simulation (Part 12): Sockets (VI)
In this article, we will look at how to solve certain problems and issues that arise when using Python code within other programs. More specifically, we will demonstrate a common issue encountered when using Excel in conjunction with MetaTrader 5, although we will be using Python to facilitate this interaction. However, this implementation has a minor drawback. It does not occur in all cases, but only in certain specific situations. When it does happen, it is necessary to understand the cause. In today’s article, we will begin explaining how to resolve this issue.


Atmosphere Clouds Model Optimization (ACMO): Practice
In this article, we will continue diving into the implementation of the ACMO (Atmospheric Cloud Model Optimization) algorithm. In particular, we will discuss two key aspects: the movement of clouds into low-pressure regions and the rain simulation, including the initialization of droplets and their distribution among clouds. We will also look at other methods that play an important role in managing the state of clouds and ensuring their interaction with the environment.