Articles on data analysis and statistics in MQL5

Articles on mathematical models and laws of probability are interesting for many traders. Mathematics is the basis of technical indicators, and statistics is required to analyze trading results and develop strategies.
Read about the fuzzy logic, digital filters, market profile, Kohonen maps, neural gas and many other tools that can be used for trading.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


The case for using a Composite Data Set this Q4 in weighing SPDR XLY's next performance
We consider XLY, SPDR’s consumer discretionary spending ETF and see if with tools in MetaTrader’s IDE we can sift through an array of data sets in selecting what could work with a forecasting model with a forward outlook of not more than a year.

Causal inference in time series classification problems
In this article, we will look at the theory of causal inference using machine learning, as well as the custom approach implementation in Python. Causal inference and causal thinking have their roots in philosophy and psychology and play an important role in our understanding of reality.

MQL5 Wizard Techniques you should know (Part 34): Price-Embedding with an Unconventional RBM
Restricted Boltzmann Machines are a form of neural network that was developed in the mid 1980s at a time when compute resources were prohibitively expensive. At its onset, it relied on Gibbs Sampling and Contrastive Divergence in order to reduce dimensionality or capture the hidden probabilities/properties over input training data sets. We examine how Backpropagation can perform similarly when the RBM ‘embeds’ prices for a forecasting Multi-Layer-Perceptron.


Statistical Arbitrage Through Cointegrated Stocks (Part 9): Backtesting Portfolio Weights Updates
This article describes the use of CSV files for backtesting portfolio weights updates in a mean-reversion-based strategy that uses statistical arbitrage through cointegrated stocks. It goes from feeding the database with the results of a Rolling Windows Eigenvector Comparison (RWEC) to comparing the backtest reports. In the meantime, the article details the role of each RWEC parameter and its impact in the overall backtest result, showing how the comparison of the relative drawdown can help us to further improve those parameters.


Market Simulation (Part 04): Creating the C_Orders Class (I)
In this article, we will start creating the C_Orders class to be able to send orders to the trading server. We'll do this little by little, as our goal is to explain in detail how this will happen through the messaging system.


Developing a Replay System (Part 40): Starting the second phase (I)
Today we'll talk about the new phase of the replay/simulator system. At this stage, the conversation will become truly interesting and quite rich in content. I strongly recommend that you read the article carefully and use the links provided in it. This will help you understand the content better.

The Group Method of Data Handling: Implementing the Combinatorial Algorithm in MQL5
In this article we continue our exploration of the Group Method of Data Handling family of algorithms, with the implementation of the Combinatorial Algorithm along with its refined incarnation, the Combinatorial Selective Algorithm in MQL5.

Category Theory in MQL5 (Part 19): Naturality Square Induction
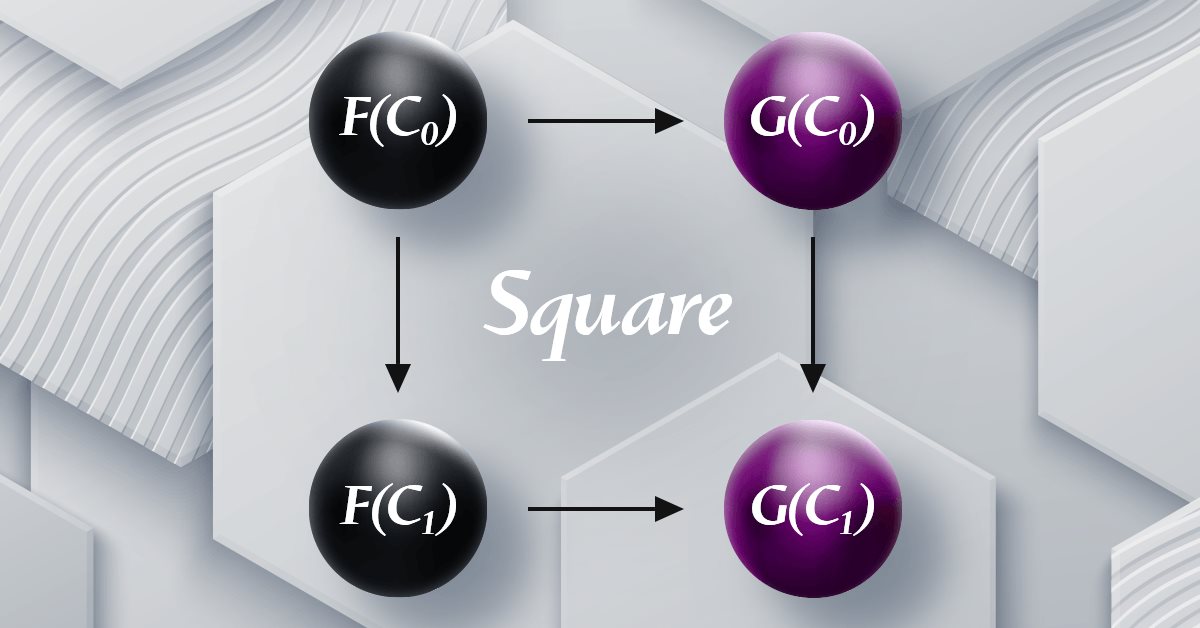
We continue our look at natural transformations by considering naturality square induction. Slight restraints on multicurrency implementation for experts assembled with the MQL5 wizard mean we are showcasing our data classification abilities with a script. Principle applications considered are price change classification and thus its forecasting.


Building Volatility models in MQL5 (Part I): The Initial Implementation
In this article, we present an MQL5 library for modeling volatility, designed to function similarly to Python's arch package. The library currently supports the specification of common conditional mean (HAR, AR, Constant Mean, Zero Mean) and conditional volatility (Constant Variance, ARCH, GARCH) models.


Category Theory in MQL5 (Part 21): Natural Transformations with LDA
This article, the 21st in our series, continues with a look at Natural Transformations and how they can be implemented using linear discriminant analysis. We present applications of this in a signal class format, like in the previous article.


Dolphin Echolocation Algorithm (DEA)
In this article, we take a closer look at the DEA algorithm, a metaheuristic optimization method inspired by dolphins' unique ability to find prey using echolocation. From mathematical foundations to practical implementation in MQL5, from analysis to comparison with classical algorithms, we will examine in detail why this relatively new method deserves a place in the arsenal of researchers facing optimization problems.

MQL5 Wizard Techniques you should know (Part 32): Regularization
Regularization is a form of penalizing the loss function in proportion to the discrete weighting applied throughout the various layers of a neural network. We look at the significance, for some of the various regularization forms, this can have in test runs with a wizard assembled Expert Advisor.


Low-Frequency Quantitative Strategies in MetaTrader 5 (Part 5): Pre-Backtest Evaluation of Machine-Learning-Generated Signals Through Formulaic Alphas
The article shows how to evaluate machine-learning alphas before a full backtest by expressing them as formulaic alphas. We compute Information Coefficient (IC), Rank IC, Information Ratio (ICIR), and t-statistics to quantify forecasting strength and stability. A MetaTrader 5 backtest illustrates differences versus execution-dependent tests, and a Python parser facilitates reproducible calculations and bulk screening.

Spurious Regressions in Python
Spurious regressions occur when two time series exhibit a high degree of correlation purely by chance, leading to misleading results in regression analysis. In such cases, even though variables may appear to be related, the correlation is coincidental and the model may be unreliable.


Market Simulation (Part 21): First Steps with SQL (IV)
Many of you may have far more experience working with databases than I do, and therefore may have a different opinion. Since it was necessary to explain why databases are designed the way they are, and why SQL has the form it does—especially why primary and foreign keys emerged—some things had to remain somewhat abstract.

Camel Algorithm (CA)
The Camel Algorithm, developed in 2016, simulates the behavior of camels in the desert to solve optimization problems, taking into account temperature, supply, and endurance. This article also presents a modified version of the algorithm (CAm) with key improvements: the use of a Gaussian distribution in generating solutions and the optimization of the oasis effect parameters.

Developing a Replay System (Part 46): Chart Trade Project (V)
Tired of wasting time searching for that very file that you application needs in order to work? How about including everything in the executable? This way you won't have to search for the things. I know that many people use this form of distribution and storage, but there is a much more suitable way. At least as far as the distribution of executable files and their storage is concerned. The method that will be presented here can be very useful, since you can use MetaTrader 5 itself as an excellent assistant, as well as MQL5. Furthermore, it is not that difficult to understand.

Economic forecasts: Exploring the Python potential
How to use World Bank economic data for forecasts? What happens when you combine AI models and economics?


Feature Engineering for ML (Part 13): Trend-Scanning Features in Python
Trend-scanning supports both forward and backward windows, and the labeling default is unsafe for features: it looks ahead and boosts next-bar agreement well above chance on random walks. We provide a dedicated wrapper, get trend scanning features, that forces computational causal and returns only window, slope, t value, and rsquared. A second analysis quantifies errors introduced by the default log transform on signed series.


Battle Royale Optimizer (BRO)
The article explores the Battle Royale Optimizer algorithm — a metaheuristic in which solutions compete with their nearest neighbors, accumulate “damage,” are replaced when a threshold is exceeded, and periodically shrink the search space around the current best solution. It presents both pseudocode and an MQL5 implementation of the CAOBRO class, including neighbor search, movement toward the best solution, and an adaptive delta interval. Test results on the Hilly, Forest, and Megacity functions highlight the strengths and limitations of the approach. The reader is provided with a ready-to-use foundation for experimentation and tuning key parameters such as popSize and maxDamage.


MQL5 Wizard Techniques you should know (Part 87): Volatility-Scaled Money Management with Monotonic Queue in MQL5
This article presents a custom MQL5 money management class that adapts position sizing to real-time volatility using a monotonic queue for O(N) sliding-window extremes. The class applies inverse volatility scaling and optionally validates risk with an RBF network. We show implementation details in the Optimize method and compare results with the inbuilt Size-Optimized class to assess latency and risk control benefits.


A Team of AI Agents with Profit-Based Rotation: The Evolution of a Living Trading System in MQL5
Financial management as an ecosystem: Seven AI traders with different personalities and strategies instead of a single algorithm. They compete for capital, learn from their mistakes, and make decisions collectively. The article explains the principles behind the Modern RL Trader system, in which the code possesses consciousness and emotions, creating a living, evolving trading mind.


Market Simulation (Part 10): Sockets (IV)
In this article, we'll look at what you need to do to start using Excel to manage MetaTrader 5, but in a very interesting way. To do this, we will use an Excel add-in to avoid using built-in VBA. If you don't know what add-in is meant, read this article and learn how to program in Python directly in Excel.


Mutual information as criteria for Stepwise Feature Selection
In this article, we present an MQL5 implementation of Stepwise Feature Selection based on the mutual information between an optimal predictor set and a target variable.


Developing a Replay System (Part 29): Expert Advisor project — C_Mouse class (III)
After improving the C_Mouse class, we can focus on creating a class designed to create a completely new framework fr our analysis. We will not use inheritance or polymorphism to create this new class. Instead, we will change, or better said, add new objects to the price line. That's what we will do in this article. In the next one, we will look at how to change the analysis. All this will be done without changing the code of the C_Mouse class. Well, actually, it would be easier to achieve this using inheritance or polymorphism. However, there are other methods to achieve the same result.


Deterministic Oscillatory Search (DOS)
Deterministic Oscillatory Search (DOS) algorithm is an innovative global optimization method that combines the advantages of gradient and swarm algorithms without the use of random numbers. The fitness oscillation and slope mechanism allows DOS to explore complex search spaces in a deterministic manner.


An introduction to Receiver Operating Characteristic curves
ROC curves are graphical representations used to evaluate the performance of classifiers. Despite ROC graphs being relatively straightforward, there exist common misconceptions and pitfalls when using them in practice. This article aims to provide an introduction to ROC graphs as a tool for practitioners seeking to understand classifier performance evaluation.


Creating a Probabilistic Market-Neutral Trading Robot Based on a Return Distribution
A market-neutral trading strategy based on the empirical return distribution offers an alternative to traditional technical analysis methods, replacing price direction forecasting with the statistical placement of orders at levels the price is likely to reach. This article provides a detailed analysis of the mathematical framework for calculating percentiles, algorithms for weighting position sizes based on the probability of an order being triggered, and mechanisms for adapting to changing market conditions through grid expiration. A complete implementation in MQL5 is provided.

Data Science and ML (Part 44): Forex OHLC Time series Forecasting using Vector Autoregression (VAR)
Explore how Vector Autoregression (VAR) models can forecast Forex OHLC (Open, High, Low, and Close) time series data. This article covers VAR implementation, model training, and real-time forecasting in MetaTrader 5, helping traders analyze interdependent currency movements and improve their trading strategies.


Integrating MQL5 with Data Processing Packages (Part 8): Using Graph Neural Networks for Liquidity Zone Recognition
This article shows how to represent market structure as a graph in MQL5, turning swing highs/lows into nodes with features and linking them by edges. It trains a Graph Neural Network to score potential liquidity zones, exports the model to ONNX, and runs real-time inference in an Expert Advisor. Readers learn how to build the data pipeline, integrate the model, visualize zones on the chart, and use the signals for rule-based execution.


Price Action Analysis Toolkit Development (Part 76): One-Click Symbol Dashboard for Centralized Multi-Chart Management in MQL5
Learn to assemble an MT5 Expert Advisor that hosts a chart management dashboard written in MQL5. The guide walks through shared definitions, symbol acquisition and filtering, chart lifecycle functions, and a UI panel with search, scrolling, and state indicators, all driven by events and a timer. The result is a reproducible tool that reduces clicks and accelerates multi-symbol analysis.


Application of the Grey Model in Technical Analysis of Financial Time Series
This article explores the grey model, a promising tool that can expand trader's capabilities. We will look at some options for applying this model to technical analysis and building trading strategies.


Developing a Replay System (Part 69): Getting the Time Right (II)
Today we will look at why we need the iSpread feature. At the same time, we will understand how the system informs us about the remaining time of the bar when there is not a single tick available for it. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.

Brain Storm Optimization algorithm (Part I): Clustering
In this article, we will look at an innovative optimization method called BSO (Brain Storm Optimization) inspired by a natural phenomenon called "brainstorming". We will also discuss a new approach to solving multimodal optimization problems the BSO method applies. It allows finding multiple optimal solutions without the need to pre-determine the number of subpopulations. We will also consider the K-Means and K-Means++ clustering methods.


Implementing Practical Modules from Other Languages in MQL5 (Part 06): Python-Like File IO operations in MQL5
This article shows how to simplify complex MQL5 file operations by building a Python-style interface for effortless reading and writing. It explains how to recreate Python’s intuitive file-handling patterns through custom functions and classes. The result is a cleaner, more reliable approach to MQL5 file I/O.


Developing a Replay System (Part 67): Refining the Control Indicator
In this article, we'll look at what can be achieved with a little code refinement. This refinement is aimed at simplifying our code, making more use of MQL5 library calls and, above all, making it much more stable, secure and easy to use in other projects that we may develop in the future.


Linear Regression Prediction Channels in MQL5: Constructing Statistically Grounded Confidence and Prediction Bands
The article implements rolling OLS regression channels in MQL5 and computes confidence and prediction bands with Student's t critical values instead of a fixed standard-deviation multiplier. It explains the leverage-driven widening at window edges, contrasts the result with Bollinger and Donchian channels, and reviews OLS assumptions on price data. A five-line rendering is documented to ensure reliable display in MetaTrader 5.

Feature Engineering for ML (Part 2): Implementing Fixed-Width Fractional Differentiation in MQL5
This article delivers a production-grade MQL5 implementation of fixed-width fractional differentiation for live MetaTrader 5 feeds. We introduce a header-only CFFDEngine that precomputes weights without a fixed cap, performs O(width) per-bar updates, and avoids per-tick allocations. The FFD.mq5 indicator supports all ENUM_APPLIED_PRICE types and prev_calculated optimization. Validation scripts confirm numerical equivalence with the standard Python frac diff_ffd pipeline.

Most notable Artificial Cooperative Search algorithm modifications (ACSm)
Here we will consider the evolution of the ACS algorithm: three modifications aimed at improving the convergence characteristics and the algorithm efficiency. Transformation of one of the leading optimization algorithms. From matrix modifications to revolutionary approaches regarding population formation.

Chemical reaction optimization (CRO) algorithm (Part I): Process chemistry in optimization
In the first part of this article, we will dive into the world of chemical reactions and discover a new approach to optimization! Chemical reaction optimization (CRO) uses principles derived from the laws of thermodynamics to achieve efficient results. We will reveal the secrets of decomposition, synthesis and other chemical processes that became the basis of this innovative method.