Articles on data analysis and statistics in MQL5

Articles on mathematical models and laws of probability are interesting for many traders. Mathematics is the basis of technical indicators, and statistics is required to analyze trading results and develop strategies.
Read about the fuzzy logic, digital filters, market profile, Kohonen maps, neural gas and many other tools that can be used for trading.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

Redefining MQL5 and MetaTrader 5 Indicators
An innovative approach to collecting indicator information in MQL5 enables more flexible and streamlined data analysis by allowing developers to pass custom inputs to indicators for immediate calculations. This approach is particularly useful for algorithmic trading, as it provides enhanced control over the information processed by indicators, moving beyond traditional constraints.


From Novice to Expert: Animated News Headline Using MQL5 (IV) — Locally hosted AI model market insights
In today's discussion, we explore how to self-host open-source AI models and use them to generate market insights. This forms part of our ongoing effort to expand the News Headline EA, introducing an AI Insights Lane that transforms it into a multi-integration assistive tool. The upgraded EA aims to keep traders informed through calendar events, financial breaking news, technical indicators, and now AI-generated market perspectives—offering timely, diverse, and intelligent support to trading decisions. Join the conversation as we explore practical integration strategies and how MQL5 can collaborate with external resources to build a powerful and intelligent trading work terminal.

MQL5 Wizard Techniques you should know (Part 51): Reinforcement Learning with SAC
Soft Actor Critic is a Reinforcement Learning algorithm that utilizes 3 neural networks. An actor network and 2 critic networks. These machine learning models are paired in a master slave partnership where the critics are modelled to improve the forecast accuracy of the actor network. While also introducing ONNX in these series, we explore how these ideas could be put to test as a custom signal of a wizard assembled Expert Advisor.


MQL5 Trading Tools (Part 12): Enhancing the Correlation Matrix Dashboard with Interactivity
In this article, we enhance the correlation matrix dashboard in MQL5 with interactive features like panel dragging, minimizing/maximizing, hover effects on buttons and timeframes, and mouse event handling for improved user experience. We add sorting of symbols by average correlation strength in ascending/descending modes, toggle between correlation and p-value views, and incorporate light/dark theme switching with dynamic color updates.


Low-Frequency Quantitative Strategies in Metatrader 5: (Part 1) Setting Up An OLAP-Friendly Data Store
The article outlines a practical data pipeline for quantitative analysis based on Parquet storage, Hive-style partitions, and DuckDB. It details migrating selected SQLite tables to Parquet, structuring market data by source, symbol, timeframe, and date, and querying it with SQL window functions. A Golden Cross example illustrates cross‑symbol evaluation of forward returns. Accompanying Python scripts handle data download, conversion, and execution.


Crystal Structure Algorithm (CryStAl)
This article presents two versions of the Crystal Structure Algorithm: the original and the modified version. The Crystal Structure Algorithm (CryStAl), published in 2021 and inspired by the physics of crystal structures, was positioned as a parameter-free metaheuristic for global optimization. However, testing revealed a critical problem with the algorithm. A modified version, CryStAlm, is also presented; it addresses the original's key shortcomings.


Developing a Replay System — Market simulation (Part 13): Birth of the SIMULATOR (III)
Here we will simplify a few elements related to the work in the next article. I'll also explain how you can visualize what the simulator generates in terms of randomness.


Developing a Replay System (Part 42): Chart Trade Project (I)
Let's create something more interesting. I don't want to spoil the surprise, so follow the article for a better understanding. From the very beginning of this series on developing the replay/simulator system, I was saying that the idea is to use the MetaTrader 5 platform in the same way both in the system we are developing and in the real market. It is important that this is done properly. No one wants to train and learn to fight using one tool while having to use another one during the fight.


Developing a Replay System (Part 73): An Unusual Communication (II)
In this article, we will look at how to transmit information in real time between the indicator and the service, and also understand why problems may arise when changing the timeframe and how to solve them. As a bonus, you will get access to the latest version of the replay /simulation app.


Recurrence Quantification Analysis (RQA) in MQL5: Building a Complete Analysis Library
This article builds a complete Recurrence Quantification Analysis (RQA) toolkit for MetaTrader 5 in pure MQL5. We cover phase-space reconstruction, time-delay embedding, distance and recurrence matrix construction, RQA metric extraction, automatic epsilon selection, and rolling-window computation through a modular library design. The article concludes by applying the library in a practical indicator that plots RR, DET, LAM, ENTR, and TREND directly on the chart, providing a solid foundation for nonlinear time-series analysis in MQL5.


Three MACD Filters on US_TECH100: Five Years of Broker Data
This article tests three common filters on a standard MACD crossover for US_TECH100 H1 using five years of broker-native data. Filters are layered incrementally: regime, higher timeframe (HTF) alignment, and US session timing, to isolate each one's marginal impact. Results show session timing contributes far more than indicator refinements, while regime and HTF add little on their own. Includes a reproducible MQL5 regime classifier.


Quantum Neural Network in MQL5 (Part III): A Virtual Quantum Processor Based on Qubits
The article focuses on creating a trading system with a real quantum simulator instead of mathematical analogies. The system uses 3 virtual qubits, quantum gates and superposition principles to analyze markets. It is implemented as a trading EA for MetaTrader 5 in MQL5. The main achievement is the transition from simulation to real quantum principles of financial information processing.


Developing a Replay System (Part 70): Getting the Time Right (III)
In this article, we will look at how to use the CustomBookAdd function correctly and effectively. Despite its apparent simplicity, it has many nuances. For example, it allows you to tell the mouse indicator whether a custom symbol is on auction, being traded, or the market is closed. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


Eagle Strategy (ES)
Eagle Strategy is an algorithm that mimics the eagle's two-phase hunting strategy: global search via Levy flights using Mantegna method, alternating with intense local exploitation using the firefly algorithm, a mathematically sound approach to balancing exploration and exploitation, and a bioinspired concept that combines two natural phenomena into a single computational method.


Data Science and ML (Part 47): Forecasting the Market Using the DeepAR model in Python
In this article, we will attempt to predict the market with a decent model for time series forecasting named DeepAR. A model that is a combination of deep neural networks and autoregressive properties found in models like ARIMA and Vector Autoregressive (VAR).


Creating Custom Indicators in MQL5 (Part 7): Hybrid Time Price Opportunity (TPO) Market Profiles for Session Analysis
In this article, we develop a custom indicator in MQL5 for hybrid Time Price Opportunity (TPO) market profiles, supporting multiple session timeframes such as intraday, daily, weekly, monthly, and fixed periods with timezone adjustments. The indicator quantizes prices into a grid, tracks session data including highs, lows, opens, and closes, and calculates key elements like the point of control and value area based on TPO counts. It renders profiles visually on the chart with customizable colors for TPO letters, single prints, value areas, POC, and close markers, enabling detailed session analysis


CAPM Model Indicator for the Forex Market
Adaptation of the classical CAPM model for the Forex currency market in MQL5. The indicator calculates expected return and risk premium based on historical volatility. The indicators rise at peaks and bottoms, reflecting the fundamental principles of pricing. Practical application for counter-trend and trend-following strategies, taking into account the dynamics of the risk-reward ratio in real time. The article includes mathematical apparatus and technical implementation.

MQL5 Wizard Techniques you should know (Part 21): Testing with Economic Calendar Data
Economic Calendar Data is not available for testing with Expert Advisors within Strategy Tester, by default. We look at how Databases could help in providing a work around this limitation. So, for this article we explore how SQLite databases can be used to archive Economic Calendar news such that wizard assembled Expert Advisors can use this to generate trade signals.


Market Simulation (Part 23): Position View (I)
The content we will cover from this point on is much more complex in terms of theory and concepts. I will try to make the material as simple as possible. The programming part itself is quite simple and straightforward. But if you do not understand the theory behind it, you will be left with no practical basis at all for refining or adapting the replay/simulation system to tasks different from the ones I am going to show. I do not want you merely to compile and use the code I present. I want you to learn, understand and, if possible, be able to create something even better.

Population optimization algorithms: Mind Evolutionary Computation (MEC) algorithm
The article considers the algorithm of the MEC family called the simple mind evolutionary computation algorithm (Simple MEC, SMEC). The algorithm is distinguished by the beauty of its idea and ease of implementation.


Price Action Analysis Toolkit Development (Part 9): External Flow
This article explores a new dimension of analysis using external libraries specifically designed for advanced analytics. These libraries, like pandas, provide powerful tools for processing and interpreting complex data, enabling traders to gain more profound insights into market dynamics. By integrating such technologies, we can bridge the gap between raw data and actionable strategies. Join us as we lay the foundation for this innovative approach and unlock the potential of combining technology with trading expertise.

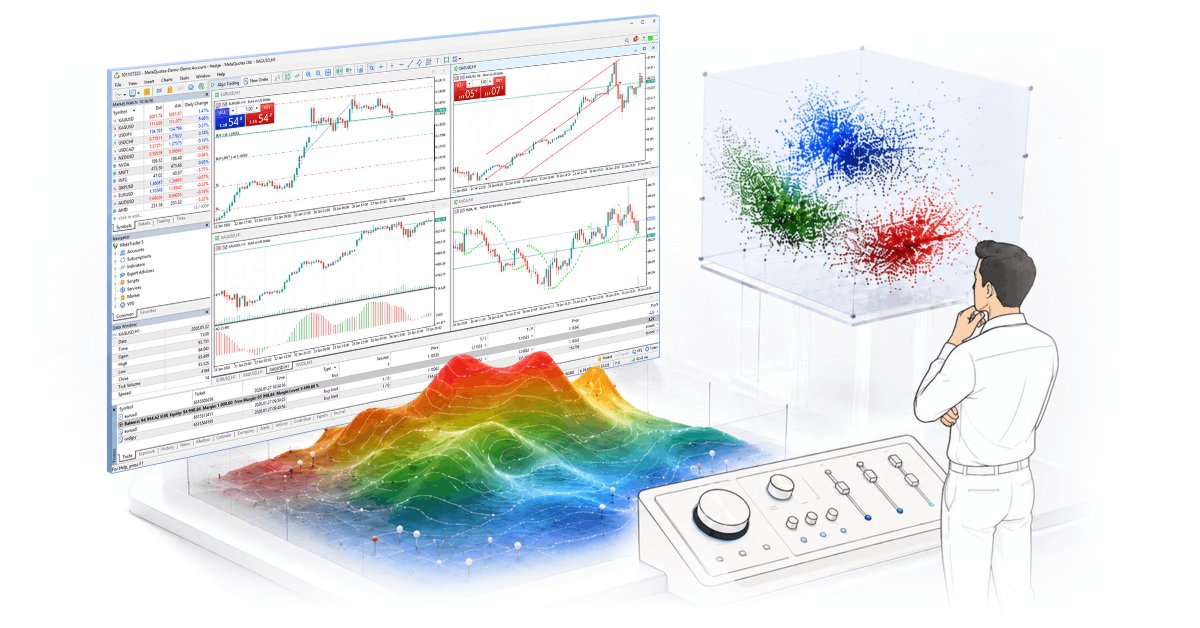
3D Visualization Without External Libraries: How MetaTrader 5 Reveals Optimization Results via MQL5 + DX11
The article describes the practical application of DirectX 11 and built-in MQL5 tools for creating 3D visualizations and interactive interfaces in MetaTrader 5. The focus is on cognitive efficiency - the ability of 3D charts and guided scenes to help in understanding optimization data, liquidity clusters, and multi-dimensional trading scenarios. The basics of the DX pipeline, working with shaders, binding mouse and keyboard events, and objective technological limitations are discussed in detail. The article is intended for MQL5 developers and algorithmic traders who are ready to transform strategy metrics into understandable 3D analytical landscapes, where the visual layer accelerates decision-making.


Population optimization algorithms: Evolution Strategies, (μ,λ)-ES and (μ+λ)-ES
The article considers a group of optimization algorithms known as Evolution Strategies (ES). They are among the very first population algorithms to use evolutionary principles for finding optimal solutions. We will implement changes to the conventional ES variants and revise the test function and test stand methodology for the algorithms.


From Novice to Expert: Market Periods Synchronizer
In this discussion, we introduce a Higher-to-Lower Timeframe Synchronizer tool designed to solve the problem of analyzing market patterns that span across higher timeframe periods. The built-in period markers in MetaTrader 5 are often limited, rigid, and not easily customizable for non-standard timeframes. Our solution leverages the MQL5 language to develop an indicator that provides a dynamic and visual way to align higher timeframe structures within lower timeframe charts. This tool can be highly valuable for detailed market analysis. To learn more about its features and implementation, I invite you to join the discussion.

Neural networks made easy (Part 40): Using Go-Explore on large amounts of data
This article discusses the use of the Go-Explore algorithm over a long training period, since the random action selection strategy may not lead to a profitable pass as training time increases.


Market Simulation (Part 01): Cross Orders (I)
Today we will begin the second stage, where we will look at the market replay/simulation system. First, we will show a possible solution for cross orders. I will show you the solution, but it is not final yet. It will be a possible solution to a problem that we will need to solve in the near future.


Price Action Analysis Toolkit Development (Part 80): Building a History Navigator for MetaTrader 5
We implement a History Navigator for MetaTrader 5 that jumps the chart to an exact historical period by date and time. The dialog validates inputs, converts them to datetime, and searches bar times with a binary-search routine before centering the selected candle. The navigation logic is separated from chart control, improving testability and maintenance, and a one-click return restores the live market view.

Blood inheritance optimization (BIO)
I present to you my new population optimization algorithm - Blood Inheritance Optimization (BIO), inspired by the human blood group inheritance system. In this algorithm, each solution has its own "blood type" that determines the way it evolves. Just as in nature where a child's blood type is inherited according to specific rules, in BIO new solutions acquire their characteristics through a system of inheritance and mutations.


Developing a Replay System — Market simulation (Part 23): FOREX (IV)
Now the creation occurs at the same point where we converted ticks into bars. This way, if something goes wrong during the conversion process, we will immediately notice the error. This is because the same code that places 1-minute bars on the chart during fast forwarding is also used for the positioning system to place bars during normal performance. In other words, the code that is responsible for this task is not duplicated anywhere else. This way we get a much better system for both maintenance and improvement.

Neural networks made easy (Part 41): Hierarchical models
The article describes hierarchical training models that offer an effective approach to solving complex machine learning problems. Hierarchical models consist of several levels, each of which is responsible for different aspects of the task.

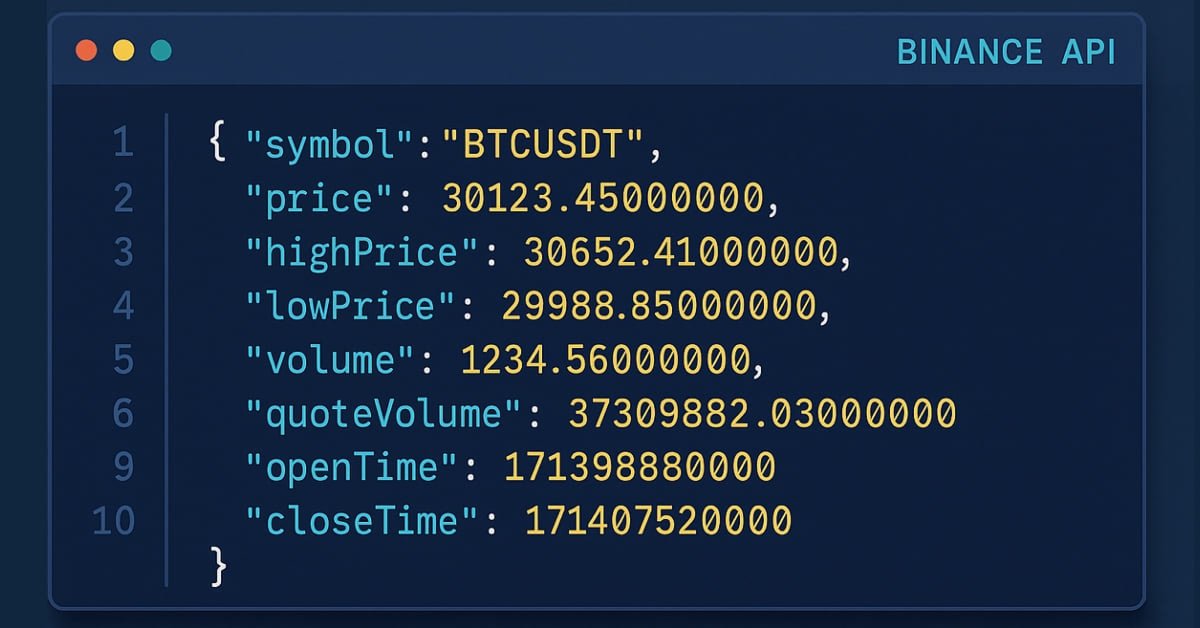
Introduction to MQL5 (Part 31): Mastering API and WebRequest Function in MQL5 (V)
Learn how to use WebRequest and external API calls to retrieve recent candle data, convert each value into a usable type, and save the information neatly in a table format. This step lays the groundwork for building an indicator that visualizes the data in candle format.


Developing a Replay System — Market simulation (Part 22): FOREX (III)
Although this is the third article on this topic, I must explain for those who have not yet understood the difference between the stock market and the foreign exchange market: the big difference is that in the Forex there is no, or rather, we are not given information about some points that actually occurred during the course of trading.


How to implement AutoARIMA forecasting in MQL5
This article presents an MQL5 implementation of AutoARIMA that builds ARIMA models without manual tuning. It estimates d via a variance-based heuristic, fits ARMA(p,q) by gradient optimization with Adam, and selects p and q using AICc. The code returns a one-step-ahead price forecast by differencing, model estimation, and integration back to price level, ready to call on a Close series.

Big Bang - Big Crunch (BBBC) algorithm
The article presents the Big Bang - Big Crunch method, which has two key phases: cyclic generation of random points and their compression to the optimal solution. This approach combines exploration and refinement, allowing us to gradually find better solutions and open up new optimization opportunities.

Statistical Arbitrage Through Cointegrated Stocks (Part 5): Screening
This article proposes an asset screening process for a statistical arbitrage trading strategy through cointegrated stocks. The system starts with the regular filtering by economic factors, like asset sector and industry, and finishes with a list of criteria for a scoring system. For each statistical test used in the screening, a respective Python class was developed: Pearson correlation, Engle-Granger cointegration, Johansen cointegration, and ADF/KPSS stationarity. These Python classes are provided along with a personal note from the author about the use of AI assistants for software development.

Data Science and ML (Part 39): News + Artificial Intelligence, Would You Bet on it?
News drives the financial markets, especially major releases like Non-Farm Payrolls (NFPs). We've all witnessed how a single headline can trigger sharp price movements. In this article, we dive into the powerful intersection of news data and Artificial Intelligence.

Data Science and ML (Part 35): NumPy in MQL5 – The Art of Making Complex Algorithms with Less Code
NumPy library is powering almost all the machine learning algorithms to the core in Python programming language, In this article we are going to implement a similar module which has a collection of all the complex code to aid us in building sophisticated models and algorithms of any kind.


Developing a Replay System (Part 37): Paving the Path (I)
In this article, we will finally begin to do what we wanted to do much earlier. However, due to the lack of "solid ground", I did not feel confident to present this part publicly. Now I have the basis to do this. I suggest that you focus as much as possible on understanding the content of this article. I mean not simply reading it. I want to emphasize that if you do not understand this article, you can completely give up hope of understanding the content of the following ones.


Developing a Replay System (Part 75): New Chart Trade (II)
In this article, we will talk about the C_ChartFloatingRAD class. This is what makes Chart Trade work. However, the explanation does not end there. We will complete it in the next article, as the content of this article is quite extensive and requires deep understanding. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


Developing a Replay System (Part 51): Things Get Complicated (III)
In this article, we will look into one of the most difficult issues in the field of MQL5 programming: how to correctly obtain a chart ID, and why objects are sometimes not plotted on the chart. The materials presented here are for didactic purposes only. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.