Articles on trading system automation in MQL5

Read articles on the trading systems with a wide variety of ideas at the core. Learn how to use statistical methods and patterns on candlestick charts, how to filter signals and where to use semaphore indicators.
The MQL5 Wizard will help you create robots without programming to quickly check your trading ideas. Use the Wizard to learn about genetic algorithms.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Foundation Models for Trading (Part I): Porting Kronos to Native MQL5
Kronos is a pretrained transformer that models OHLCV bars the way a language model predicts words. We reimplement its tokenizer/encoder and transformer block in native MQL5, export weights to flat .bin files, and remove Python from runtime entirely. Part 1 delivers preprocessing and BSQ tokenization plus a bit-for-bit verification harness against PyTorch, so you can run the encoder inside MetaTrader 5 with confidence.


MQL5 Wizard Techniques you should know (Part 95): Using Disjoint Set Union and Deep Belief Network in a Custom Signal Class
For this article we switch to a custom MQL5 Wizard class that examines entry Signals. Our custom class is ‘CSignalDSUDBN’ this time around, and is coded by combining the Disjoint Set Union algorithm with a Deep Belief network. As has been the case throughout these series, our model is testable with MQL5 Wizard-Assembled Expert Advisors that can be tuned with different trailing stops and money management classes.


MQL5 Wizard Techniques you should know (Part 93): Using Suffix Automation and an Auto Encoder in a Custom Money Management Class
For this article we switch to a custom MQL5 Wizard class implementation that explores Money Management. We are labelling our custom class ‘CMoneySuffixAE’ that we derive by combining the Suffix Automaton algorithm with an Autoencoder neural network. As always, this formulation is testable with MQL5 Wizard Assembled Expert Advisors that can be tuned with various entry signals and trailing stop approaches.


Development and Forward Testing of an Autonomous LLM Agent for Trading with SEAL
A hybrid architecture based on Llama 3.2 and SEAL is being tested on eight currency pairs (M15), with forward-period data isolation and information leakage control. The methodology combines adversarial self-play, curriculum learning, and class balancing to ensure stable training. The experiments confirm the gap between forecast accuracy and actual returns, providing readers with practical guidelines for testing strategies and accurately assessing their generalizability.


Carry Trade Logic in MQL5: Building an EA That Factors Swap Rates Into Position Sizing and Holding Decisions
Most retail traders ignore overnight swap rates, but for long-term positions, these interest payments can make or break your strategy. This article shows you how to build a dynamic MQL5 module that retrieves real-time swap data and converts it into actual profit or loss in your account currency. You will learn how to program an Expert Advisor that automatically calculates if a trade is worth holding based on carry income and adjusts your position size to account for expected interest. It is a practical guide to turning a hidden cost into a mathematical advantage for your trading systems.


Trends and Traditions: Using Rademacher Functions in Trading
Although the functions we will discuss have been known for quite some time, their application in the field of trading remains terra incognita to this day. In this article, we will explore some of the opportunities these old-but-new functions offer for developing trading strategies and assess their potential.


Neural Networks in Trading: Probabilistic Time Series Forecasting (Conclusion)
We invite you to learn about the K²VAE framework and how the proposed approaches can be integrated into a trading system. You will learn how the hybrid Koopman–Kalman–VAE approach helps build adaptive and interpretable models. The article concludes with practical results from using the implemented solutions.

MQL5 Wizard Techniques you should know (Part 30): Spotlight on Batch-Normalization in Machine Learning
Batch normalization is the pre-processing of data before it is fed into a machine learning algorithm, like a neural network. This is always done while being mindful of the type of Activation to be used by the algorithm. We therefore explore the different approaches that one can take in reaping the benefits of this, with the help of a wizard assembled Expert Advisor.


Beyond GARCH (Part IV): Partition Analysis in MQL5
In this article, we shift from Python research to native MQL5 engineering. We build the first module of the MMAR library: a shared constants header, an SVD-based OLS regression class, a Generalized Hurst Exponent estimator, and the partition analysis engine that computes the partition function, extracts tau(q), estimates H via zero-crossing interpolation, and scores multifractality through three diagnostic tests. Tested on 500,000 bars of EURUSD M10, the engine correctly classifies the data as multifractal in under four seconds. Part 4 of an eight-part series. Part 5 fits the tau(q) curve to four candidate distributions via the Legendre transform.


Feature Engineering for ML (Part 10): Structural Break Tests in MQL5
We port AFML Chapter 17 structural break tests to MQL5 as a single include, CStructuralBreaks, delivering six bar-indexed features for EAs: CSW statistic and critical value, Chow-Type DFC, SADF with a rolling lookback (default 252), SM-Exp, and SM-Power. SADF uses O(L²) rolling windows for real-time viability. A companion StructuralBreaksViewer indicator plots all series with per‑series visibility and optional z‑score normalization. SB_EMPTY marks invalid values for safe integration.


Monochronic Trading (Part 1): How to Detect Broker Timezone and DST in MQL5
We describe an MQL5 framework that aligns entries with session rhythms and scheduled clock events. A script identifies the broker's time zone and DST by detecting NFP spikes on EURUSD and matching them to EU/US/AU transition dates, producing EA‑ready settings. Session-to-broker time conversion and 15-minute marks constrain execution. A multi‑timeframe AMA signal aggregates trends for strategy selection and optimization.


Building a Broker-Agnostic Symbol Resolution Layer in MQL5
We implement a symbol resolution framework that abstracts broker naming differences in MetaTrader 5. Using a persistent mapping store, layered resolution with validation, a hash-indexed registry, and a cache, it returns selectable symbols with live market data and logs unresolved cases. Practically, you can deploy the same EA across brokers and keep symbol access consistent at low runtime cost.


Designing a Strategy State Machine in MQL5: Replacing Nested If-Else Logic with Formal States
Nested if-else logic inside OnTick() creates implicit states that are hard to isolate, debug, and extend without regressions. A formal finite state machine in MQL5 uses an IState interface, a CStrategyContext mediator, and four concrete states to separate detection from behavior. A three-file include structure resolves circular dependencies and keeps declarations, definitions, and instantiation clean, making changes safer and debugging faster.


Beyond the Clock (Part 2): Building Runs Bars in MQL5
We implement tick-, volume-, and dollar-runs bars in Python and MQL5 and align them with the existing bar‑building framework. The article details the dual‑accumulator update, offline calibration with per‑side seeds, state persistence for EAs, and parity verification to match Python and MQL5 outputs. Runs bars expose one‑sided bursts that net imbalance can hide, improving coverage during quiet sessions and for mean‑reversion models.


Building a Position Sizing Engine in MQL5 with Multiple Risk Models
The article presents a position sizing engine for MQL5 Expert Advisors that separates risk policy from lot conversion. Four models—fixed fractional, fixed monetary, ATR-based volatility scaling, and equity-curve scaling—share a CLotConverter that uses OrderCalcProfit() to measure real money per point. A unified CPositionSizer interface exposes CalculateLots(), making model changes straightforward while producing broker-compliant volumes across symbols.


MQL5 Wizard Techniques you should know (Part 97): Using Convex Hull and a miniature GRU Network in a Custom Trailing Stop Class
For this article we look at a custom MQL5 Wizard class for Trailing Stops. Our implemented custom class ‘CTrailingConvexHullGRU’, is built from merging the Convex Hull algorithm with a GRU network. As always we seek to develop a model that is testable with MQL5 Wizard-Assembled Expert Advisors and can be tuned with various Money Management and entry Signals classes. Our testing is with the 'Envelopes' and the RSI classes for Signal.


Developing a Replay System (Part 58): Returning to Work on the Service
After a break in development and improvement of the service used for replay/simulator, we are resuming work on it. Now that we've abandoned the use of resources like terminal globals, we'll have to completely restructure some parts of it. Don't worry, this process will be explained in detail so that everyone can follow the development of our service.


Neural Networks in Trading: An Intelligent Forecast Pipeline (Conclusion)
The article provides a fascinating look at how SwiGLU embedding reveals hidden market patterns, and how a sparse Mixture of Experts within a Decoder-Only Transformer makes forecasts more accurate at reasonable computational cost. We take an in-depth look at the integration of Time‑MoE into MQL5 and OpenCL, and provide a step-by-step guide to configuring and training the model.


Mapping the Shape of Price: The Mapper Lens and Cover in MQL5
The article introduces the Mapper pipeline in MQL5 by implementing the two fundamental components: CTDAMapperFilter (lens) and CTDAMapperCover (overlapping intervals). It explains three lens options—eccentricity, density, and coordinate—plus cover parameters (resolution and gain), and demonstrates how a price point cloud is reduced to one value per point and interval memberships. Readers obtain ready inputs for subsequent clustering and graph construction.


Neural Networks in Trading: Effective Feature Extraction for Accurate Classification (Building Objects)
Mantis is a versatile tool for in-depth time series analysis that can be flexibly scaled to accommodate any financial scenario. Learn how a combination of patching, local convolutions, and cross-attention enables a highly accurate interpretation of market patterns.


First Fractal Breakout — Intraday Strategy, Expert Advisor and Backtesting
This article develops a market‑structure‑driven intraday breakout system based on Bill Williams fractals. We define session bounds, derive volatility‑scaled stops, use fixed risk and take‑profit multipliers, and limit trades to one per direction. An MQL5 Expert Advisor, visualization and statistics, tick-level backtests, an ORB comparison, and a cross-asset forward test provide a complete, replicable workflow.


Neural Networks in Trading: Hierarchical Skill Discovery for Adaptive Agent Behavior (HiSSD)
In this article, we explore the HiSSD framework, which combines hierarchical learning and multi-agent approaches to create adaptive systems. We examine in detail how this innovative methodology helps uncover hidden patterns in financial markets and optimize trading strategies in decentralized environments.

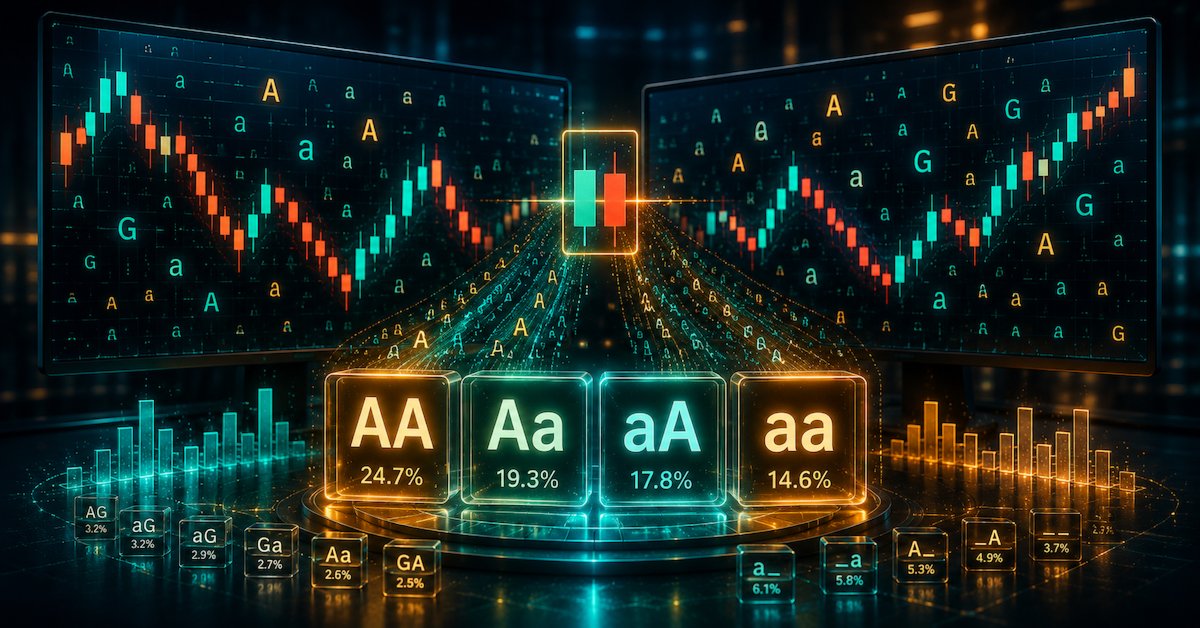
Encoding Candlestick Patterns (Part 4): Frequency Analysis for Double-Candlestick Structures
This article extends single-candlestick analysis to ordered double-candlestick patterns using an MQL5 script. The script encodes candles into symbols, extracts every consecutive two-symbol sequence (treating Aa and aA as different), counts occurrences and percentages, and writes sorted frequency tables to a text file. Readers can quickly identify the most recurrent transitions by symbol, timeframe, and lookback for further statistical testing.


Beyond GARCH (Part VIII): The MMAR Library And Putting it to Work in an Expert Advisor
This article finalizes the MMAR project with a CMMAR facade class and a demo Expert Advisor for MetaTrader 5. The facade exposes a compact API—configure, Fit(), Forecast()—that wraps partition analysis, spectrum fitting and Monte Carlo simulation. You will learn how to load data, fit the model and obtain a volatility forecast, with diagnostics and status handling for robust use in EAs.


Beyond GARCH (Part III): Building the MMAR and the Verdict
With the multifractal parameters from Part 2 in hand, this article builds the full MMAR process. We construct the multiplicative cascade for trading time, generate Fractional Brownian Motion via Davies-Harte FFT, and combine both into X(t) = B_H[theta(t)]. A 100-path Monte Carlo simulation produces the volatility forecast, which we then pit against GARCH on the same EURUSD M5 data. Does Mandelbrot's fractal architecture outforecast Engle's conditional variance framework? Part 3 of a eight-part series leading to a native MQL5 library and Expert Advisor.


Trading with the MQL5 Economic Calendar (Part 12): SQLite Storage and Deduplication
In this article, we replace the embedded CSV snapshot with a SQLite layer that persists calendar events and triggered trade IDs across restarts. The database lives in the common terminal folder and is shared by live charts and the strategy tester, so both modes read the same data without recompiling. An on-demand downloader with a canvas progress bar fetches history from the calendar API and stores it for offline reuse.


MetaTrader 5 Machine Learning Blueprint (Part 19): Bagging Regimes
We test AFML's claim that the sequential bootstrap decorrelates bagged trees on overlapping triple‑barrier labels by isolating two levers: draw count and draw rule. One decision identical tree is bagged under four row‑sampling regimes and evaluated on EURUSD 2022–2023 for draw uniqueness, between‑tree correlation, AUC, and calibration. Decorrelation comes almost entirely from throttling max_samples to average uniqueness; the sequential draw adds little. Out-of-bag inflation is largest under full-count sequential sampling.


MQL5 Wizard Techniques you should know (Part 100): Sliding Window Median and Bidirectional LSTM for a Custom Trailing Stop
CTrailingSlidingMedianBiLSTM is a custom MQL5 Wizard trailing module that combines robust median/MAD outlier filtering with a BiLSTM context score in the range [-1, 1]. Four algorithm modes (standard, bands, RSI, adaptive) target noise, mean-reverting bursts and liquidity spikes, reducing premature stop adjustments. This module is intended for side-by-side evaluation with diverse entry signals and money management settings.


Institutional-Grade Multi-Currency Portfolio Engine in MQL5 (Part 1): Architecture of a Multi-Currency EA Framework
The article details a master–agent MQL5 framework that mitigates cross-symbol risk concentration. A single Portfolio Controller publishes risk limits and halt flags to Instrument Agents through shared channels and a readiness flag, while agents size orders only within the published budget. It contrasts global variables, named pipes, and files, and clarifies timer intervals and latency so data allocation may be up to one cycle stale without breaking coordination.


MetaTrader 5 Machine Learning Blueprint (Part 18): Sequential Bootstrap, Corrected — Clone, Class Erasure, and the Comparison Toolkit
The article diagnoses two defects that neutralize sequential bootstrap during cross‑validation: type erasure of SequentiallyBootstrappedBaggingClassifier and a fold‑level shape mismatch from cloning full samples info sets. It retains the classifier's identity, adds find seq bagging to re‑inject fold‑sliced t1 in CalibratorCV.fit, and resets state per split. A new bootstrap_comparison module reports OOF and OOB metrics and memory, letting you verify that sequential sampling is applied correctly and quantify its impact.


Neural Networks in Trading: Heterogeneity-Informed Meta-Parameter Learning (HimNet)
We invite you to explore the HimNet framework, which combines the flexibility of spatio-temporal adaptation with high computational efficiency, enabling accurate and stable forecasts for financial time series. The article explains in detail how its key components interact with one another, transforming complex algorithms into a manageable architecture.


MQL5 Wizard Techniques you should know (Part 98): Using an Unscented Kalman Filter and a Capsule Network in a Custom Signal Class
This article presents 'CSignalUKFCapsNet', as a custom class coded in MQL5. This class is meant to be used with the MQL5 Wizard when assembling an Expert Advisor and when selected in the Wizard it defines the Expert Advisor's entry signals. In building this custom class, we brought together the algorithm Unscented Kalman Filter and the Capsule Neural Network. Our algorithm is showcased with four operation modes, and the coding of this as a custom class for the MQL5 Wizard, allows testing with various Trailing Stop methods and Money Management systems.


Neural Networks in Trading: Generalizing Time Series Without Data-Specific Dependence (Conclusion)
The article will show you how Mamba4Cast turns theory into a working trading algorithm and lays the groundwork for your own experiments. Do not miss this opportunity to gain a full range of knowledge and inspiration for developing your own strategy.


Building a Trade Analytics System (Part 3): Storing MetaTrader 5 Trades in SQLite
This article extends a Flask backend to reliably receive, validate, and store closed trade data from MetaTrader 5 using SQLite and Flask‑SQLAlchemy. It implements required‑field checks, timestamp conversion, transaction‑safe persistence, and working retrieval endpoints for all trades and single records, plus a basic summary. The result is a complete data pipeline with local testing that records trades and exposes them through a structured API for further analysis.


Engineering Trading Discipline into Code (Part 8): Building a Setup Confirmation and Trade Authorization Layer in MQL5
This article introduces an MQL5 trade authorization framework built around CDisciplineLayer, CDisciplineGuardian, and CDisciplinePanel. The framework manages setup lifecycles, signal freshness, session restrictions, setup expiry, and global trading locks through a centralized authorization layer. It also provides automated enforcement of violations and a real-time dashboard, enabling consistent trade validation and monitoring before and after execution.


Building a Position Lifecycle Manager in MQL5 (Part 1): The Foundation of Reusable Position Management
A state-driven Position Lifecycle Manager brings structure to post-entry trade handling in MetaTrader 5. It discovers open positions, tracks them via managed objects, applies ATR-based protection, executes break-even transitions, and removes completed trades, with a clear NEW → PROTECTED → BREAKEVEN → CLOSED flow. The article shows integration with the standard MACD EA to enable reuse across strategies.


Exporting MetaTrader 5 Open Positions to a Live-Refreshing HTML Dashboard
The article builds an MQL5 Expert Advisor that writes a self-refreshing HTML positions dashboard to MQL5/Files on every tick, so you can monitor open trades in any browser. It covers reading live position data, generating a complete page with inline CSS and a JavaScript reload timer, and writing the file atomically. The design escapes HTML in comments, shows an explicit empty state, and writes a clear offline page on EA shutdown.


Neural Networks in Trading: Effective Feature Extraction for Accurate Classification (Final Part)
The Mantis framework transforms complex time series into informative tokens and serves as a reliable foundation for an intelligent trading agent capable of operating in real time.


Adaptive Spread Monitoring and Order Gating in MQL5
This article presents a distribution-adaptive spread monitor for MQL5 that replaces fixed thresholds with a rolling histogram of each symbol's recent spread. It explains percentile estimation from bins, a four-state GREEN/YELLOW/RED/WARMING classification, and a CCanvas dashboard rendered from real histogram data. You will get a ready workflow for per-symbol order gating and controlled alerting via arm/disarm hysteresis plus cooldown, with a verification script and clear calibration and resolution limits.


Cross Recurrence Quantification Analysis (CRQA) in MQL5: Building a Complete Analysis Library
This article extends the MQL5 RQA library to Cross-Recurrence Quantification Analysis (CRQA) for comparing two time series. We implement dual‑series embedding, cross‑recurrence matrix construction, adapted metrics (CRR, CDET, CLAM, CENTR, and others), and rolling‑window analysis, with optional GPU acceleration via OpenCL. A ready-to-use indicator compares two symbols in real time, supporting timestamp alignment and normalization for practical inter-market analysis.