Articles on trading system automation in MQL5

Read articles on the trading systems with a wide variety of ideas at the core. Learn how to use statistical methods and patterns on candlestick charts, how to filter signals and where to use semaphore indicators.
The MQL5 Wizard will help you create robots without programming to quickly check your trading ideas. Use the Wizard to learn about genetic algorithms.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Neural Networks in Trading: Disentangling Structured Components (SCNN)
We invite you to explore the innovative SCNN framework, which takes time series analysis to a new level by clearly separating data into long-term, seasonal, short-term, and residual components. This approach significantly improves forecasting accuracy by allowing the model to adapt to complex and changing market dynamics.

Data Science and ML (Part 44): Forex OHLC Time series Forecasting using Vector Autoregression (VAR)
Explore how Vector Autoregression (VAR) models can forecast Forex OHLC (Open, High, Low, and Close) time series data. This article covers VAR implementation, model training, and real-time forecasting in MetaTrader 5, helping traders analyze interdependent currency movements and improve their trading strategies.


Neural Networks in Trading: Multi-Task Learning Based on the ResNeXt Model (Final Part)
We continue exploring a multi-task learning framework based on ResNeXt, which is characterized by modularity, high computational efficiency, and the ability to identify stable patterns in data. Using a single encoder and specialized "heads" reduces the risk of model overfitting and improves the quality of forecasts.

Neural Networks in Trading: Generalized 3D Referring Expression Segmentation
While analyzing the market situation, we divide it into separate segments, identifying key trends. However, traditional analysis methods often focus on one aspect and thus limit the proper perception. In this article, we will learn about a method that enables the selection of multiple objects to ensure a more comprehensive and multi-layered understanding of the situation.


Neural networks made easy (Part 82): Ordinary Differential Equation models (NeuralODE)
In this article, we will discuss another type of models that are aimed at studying the dynamics of the environmental state.


Developing a Replay System (Part 69): Getting the Time Right (II)
Today we will look at why we need the iSpread feature. At the same time, we will understand how the system informs us about the remaining time of the bar when there is not a single tick available for it. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


MQL5 Wizard Techniques you should know (Part 87): Volatility-Scaled Money Management with Monotonic Queue in MQL5
This article presents a custom MQL5 money management class that adapts position sizing to real-time volatility using a monotonic queue for O(N) sliding-window extremes. The class applies inverse volatility scaling and optionally validates risk with an RBF network. We show implementation details in the Optimize method and compare results with the inbuilt Size-Optimized class to assess latency and risk control benefits.


Overcoming Accessibility Problems in MQL5 Trading Tools (Part III): Bidirectional Speech Communication Between a Trader and an Expert Advisor
Build a local, bidirectional voice interface for MetaTrader 5 using MQL5 WebRequest and two Python services. The article implements offline speech recognition with Vosk, wake‑word detection, an HTTP command endpoint, and a text‑to‑speech server on localhost. You will wire an Expert Advisor that fetches commands, executes trades, and returns spoken confirmations for hands‑free operation.


Application of the Grey Model in Technical Analysis of Financial Time Series
This article explores the grey model, a promising tool that can expand trader's capabilities. We will look at some options for applying this model to technical analysis and building trading strategies.


A Team of AI Agents with Profit-Based Rotation: The Evolution of a Living Trading System in MQL5
Financial management as an ecosystem: Seven AI traders with different personalities and strategies instead of a single algorithm. They compete for capital, learn from their mistakes, and make decisions collectively. The article explains the principles behind the Modern RL Trader system, in which the code possesses consciousness and emotions, creating a living, evolving trading mind.


Implementing Practical Modules from Other Languages in MQL5 (Part 06): Python-Like File IO operations in MQL5
This article shows how to simplify complex MQL5 file operations by building a Python-style interface for effortless reading and writing. It explains how to recreate Python’s intuitive file-handling patterns through custom functions and classes. The result is a cleaner, more reliable approach to MQL5 file I/O.


MQL5 Trading Tools (Part 17): Exploring Vector-Based Rounded Rectangles and Triangles
In this article, we explore vector-based methods for drawing rounded rectangles and triangles in MQL5 using canvas, with supersampling for anti-aliased rendering. We implement scanline filling, geometric precomputations for arcs and tangents, and border drawing to create smooth, customizable shapes. This approach lays the groundwork for modern UI elements in future trading tools, supporting inputs for sizes, radii, borders, and opacities.

Chemical reaction optimization (CRO) algorithm (Part I): Process chemistry in optimization
In the first part of this article, we will dive into the world of chemical reactions and discover a new approach to optimization! Chemical reaction optimization (CRO) uses principles derived from the laws of thermodynamics to achieve efficient results. We will reveal the secrets of decomposition, synthesis and other chemical processes that became the basis of this innovative method.


Price Action Analysis Toolkit Development (Part 77): Building a Searchable Indicator Panel for MetaTrader 5
A modular indicator search system for MetaTrader 5 that replaces manual navigation through built-in indicator categories with a searchable interface. The application integrates an indicator catalog, search engine, chart launcher, and graphical panel, allowing indicators to be located, filtered, and attached to the appropriate chart window from a single interface.


Introduction to MQL5 (Part 43): Beginner Guide to File Handling in MQL5 (V)
The article explains how to use MQL5 structures with binary files to persist Expert Advisor parameters. It covers defining structures, accessing members, and distinguishing simple from complex layouts, then writing and reading entire records using FileWriteStruct and FileReadStruct in FILE BIN mode. You will learn safe patterns for fixed-size data and how shared storage (FILE COMMON) enables reuse across sessions and terminals.


Market Simulation (Part 02): Cross Orders (II)
Unlike what was done in the previous article, here we will test the selection option using an Expert Advisor. Although this is not a final solution yet, it will be enough for now. With the help of this article, you will be able to understand how to implement one of the possible solutions.


OrderSend retries and circuit breaker in MQL5
Volatile-market failures such as requotes, connection drops, and partial fills expose a common weakness in EAs: unclassified retries and no cumulative failure control. This article introduces CRetryExecutor with exponential backoff and explicit error classification, plus a three-state CCircuitBreaker with cooldown and half-open probes, unified in CExecutionGateway. You can plug it into an EA to stop futile retries, prevent duplicate submissions, and improve diagnostics.


Category Theory in MQL5 (Part 17): Functors and Monoids
This article, the final in our series to tackle functors as a subject, revisits monoids as a category. Monoids which we have already introduced in these series are used here to aid in position sizing, together with multi-layer perceptrons.

MQL5 Wizard Techniques You Should Know (Part 15): Support Vector Machines with Newton's Polynomial
Support Vector Machines classify data based on predefined classes by exploring the effects of increasing its dimensionality. It is a supervised learning method that is fairly complex given its potential to deal with multi-dimensioned data. For this article we consider how it’s very basic implementation of 2-dimensioned data can be done more efficiently with Newton’s Polynomial when classifying price-action.


Price Action Analysis Toolkit Development (Part 76): One-Click Symbol Dashboard for Centralized Multi-Chart Management in MQL5
Learn to assemble an MT5 Expert Advisor that hosts a chart management dashboard written in MQL5. The guide walks through shared definitions, symbol acquisition and filtering, chart lifecycle functions, and a UI panel with search, scrolling, and state indicators, all driven by events and a timer. The result is a reproducible tool that reduces clicks and accelerates multi-symbol analysis.


Reinforcement Learning Meets MetaTrader 5: A Complete Pipeline for Training, Validating and Honestly Evaluating a Gold Trading Bot
This article presents a complete RL trading pipeline for XAUUSD: a supervised signal baseline with triple-barrier labels, PPO training, purged walk-forward validation with embargo, multi-seed checks, and contract-guarded deployment with normalization. It includes runnable code for data validation, features, environment, training, and broker‑based reconciliation. The live demo over 763 closed trades showed no statistically significant edge, and the methods highlight where information and costs, not architecture, set performance limits.


Mapping Dealer Gamma Exposure (GEX) in MetaTrader 5: Walls, the Zero-Gamma Flip, and a Chart Overlay
In this article we build a dealer gamma-exposure map in MQL5. From an option chain, the tool computes per-strike GEX, finds the call and put walls, and solves for the zero-gamma flip that separates a mean-reverting regime from a trending one, then draws it all on the chart. CSV and native-symbol data paths included.

Implementing Practical Modules from Other Languages in MQL5 (Part 01): Building the SQLite3 Library, Inspired by Python
The sqlite3 module in Python offers a straightforward approach for working with SQLite databases, it is fast and convenient. In this article, we are going to build a similar module on top of built-in MQL5 functions for working with databases to make it easier to work with SQLite3 databases in MQL5 as in Python.


Extremal Optimization (EO)
The article discusses the Extremal Optimization (EO) algorithm, an optimization method inspired by the Bak-Sneppen self-organized criticality model, where evolution occurs through the elimination of the worst-case components of the system. The modified population version of the algorithm demonstrates a shift away from theoretical principles in favor of practical efficiency, leading to the creation of powerful computational tools.

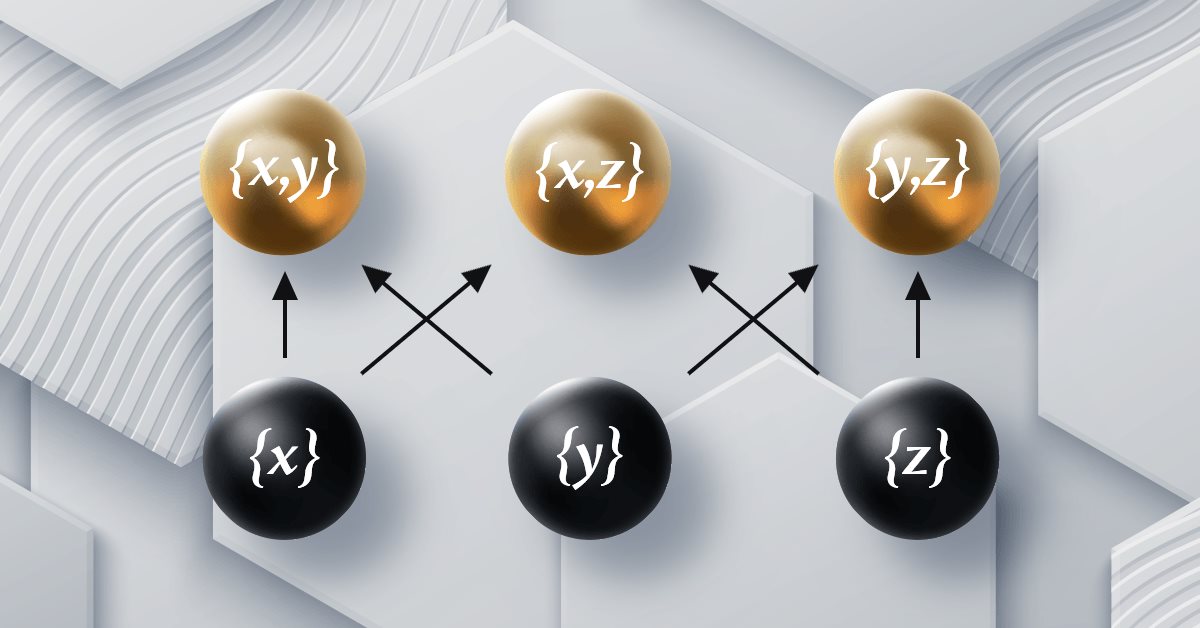
Category Theory in MQL5 (Part 12): Orders
This article which is part of a series that follows Category Theory implementation of Graphs in MQL5, delves in Orders. We examine how concepts of Order-Theory can support monoid sets in informing trade decisions by considering two major ordering types.


Markets Positioning Codex in MQL5 (Part 2): Bitwise Learning, with Multi-Patterns for Nvidia
We continue our new series on Market-Positioning, where we study particular assets, with specific trade directions over manageable test windows. We started this by considering Nvidia Corp stock in the last article, where we covered 5 signal patterns from the complimentary pairing of the RSI and DeMarker oscillators. For this article, we cover the remaining 5 patterns and also delve into multi-pattern options that not only feature untethered combinations of all ten, but also specialized combinations of just a pair.


Statistical Arbitrage Through Cointegrated Stocks (Part 10): Detecting Structural Breaks
This article presents the Chow test for detecting structural breaks in pair relationships and the application of the Cumulative Sum of Squares - CUSUM - for structural breaks monitoring and early detection. The article uses the Nvidia/Intel partnership announcement and the US Gov foreign trade tariff announcement as examples of slope inversion and intercept shift, respectively. Python scripts for all the tests are provided.

MQL5 Wizard Techniques you should know (Part 40): Parabolic SAR
The Parabolic Stop-and-Reversal (SAR) is an indicator for trend confirmation and trend termination points. Because it is a laggard in identifying trends its primary purpose has been in positioning trailing stop losses on open positions. We, however, explore if indeed it could be used as an Expert Advisor signal, thanks to custom signal classes of wizard assembled Expert Advisors.


Creating a Probabilistic Market-Neutral Trading Robot Based on a Return Distribution
A market-neutral trading strategy based on the empirical return distribution offers an alternative to traditional technical analysis methods, replacing price direction forecasting with the statistical placement of orders at levels the price is likely to reach. This article provides a detailed analysis of the mathematical framework for calculating percentiles, algorithms for weighting position sizes based on the probability of an order being triggered, and mechanisms for adapting to changing market conditions through grid expiration. A complete implementation in MQL5 is provided.


Market Microstructure in MQL5 (Part 1): Robust Foundation
This article builds the foundation layer of a twelve-part MQL5 market microstructure toolkit. It implements guarded math helpers (SafeDivide, SafeLog, SafeSqrt, SafeExp, SafeTanh), robust data validation (ValidateSymbolV2, SafeCopyClose), trimmed statistical estimators (robust mean var), a linear regression slope, shared structs, and an FFT. You compile a single include file that hardens indicators and expert advisors against silent numerical failures and standardizes data flow for later parts.


Unified Multi-Timeframe Renko: Synthesizing the Market's Temporal Dimensions
The article presents an innovative concept for a multi-timeframe Renko chart that combines signals from four timeframes (M5, M15, H1, H4) into a unified synthetic instrument. The system creates a virtual symbol in MetaTrader 5 by using the EMA of each timeframe to generate a composite signal through three methods: simple average, weighted average, and consensus. The implementation includes ATR-based adaptive brick sizing, real-time operation, and full integration with MetaTrader 5.


Low-Frequency Quantitative Strategies in MetaTrader 5 (Part 5): Pre-Backtest Evaluation of Machine-Learning-Generated Signals Through Formulaic Alphas
The article shows how to evaluate machine-learning alphas before a full backtest by expressing them as formulaic alphas. We compute Information Coefficient (IC), Rank IC, Information Ratio (ICIR), and t-statistics to quantify forecasting strength and stability. A MetaTrader 5 backtest illustrates differences versus execution-dependent tests, and a Python parser facilitates reproducible calculations and bulk screening.


Building a Trade Analytics System (Part 4): Summary Metrics and Dashboard
This article extends the existing Flask backend to compute performance analytics from stored MetaTrader 5 closed trades and deliver them as both JSON and a simple web view. It calculates total trades, total profit, win rate, average profit, and trade duration metrics, returning JSON at /api/v1/analytics/summary and rendering a dashboard at /api/v1. The result provides a quick, consistent way to review trading performance from persisted SQLite records.


MQL5 Bootstrap (I): Reusable Functions for Working with Positions and Orders
This article presents a compact MQL5 utility layer for routine trade operations. It includes position existence checkers, position counters, bulk close helpers, and functions to retrieve the most recent or oldest position by symbol, magic, or type. A simple SMA crossover Expert Advisor demonstrates integration. The result is cleaner EAs, fewer inconsistencies across projects, and faster maintenance.

Neural Networks in Trading: Reducing Memory Consumption with Adam-mini Optimization
One of the directions for increasing the efficiency of the model training and convergence process is the improvement of optimization methods. Adam-mini is an adaptive optimization method designed to improve on the basic Adam algorithm.


The MQL5 Standard Library Explorer (Part 12): Multi-Timeframe Composite-Score Dashboard
The article implements CMultiTimeframeMatrix, a reusable dashboard that maps symbols vs. timeframes and displays a numeric, colour‑coded score. The score combines trend, momentum, and volatility, updates by timer, and respects performance constraints. You will learn how to build the UI with CAppDialog/CLabel, compute metrics via CMatrixDouble, and embed the component into a thin EA for a consistent, real-time overview.


Feature Engineering for ML (Part 4): Implementing Time Features in MQL5
Applying Python session boundaries to MQL5 broker timestamps misclassifies session membership by two to three hours on any non-UTC broker, corrupting session flags across the full backtest history. We implement CTimeFeatures.mqh, containing CRingBuffer and CTimeFeatures, with three EA-facing methods: Initialize (UTC offset capture and frequency gate configuration), Update (log return push to session-conditional ring buffers), and Calculate (cyclical encoding, session flags, and session volatility). The output is a flat double array drop-compatible with Python's get_time_features for sub-hourly, hourly, and daily timeframes.


MQL5 Wizard Techniques you should know (Part 47): Reinforcement Learning with Temporal Difference
Temporal Difference is another algorithm in reinforcement learning that updates Q-Values basing on the difference between predicted and actual rewards during agent training. It specifically dwells on updating Q-Values without minding their state-action pairing. We therefore look to see how to apply this, as we have with previous articles, in a wizard assembled Expert Advisor.

Example of Causality Network Analysis (CNA) and Vector Auto-Regression Model for Market Event Prediction
This article presents a comprehensive guide to implementing a sophisticated trading system using Causality Network Analysis (CNA) and Vector Autoregression (VAR) in MQL5. It covers the theoretical background of these methods, provides detailed explanations of key functions in the trading algorithm, and includes example code for implementation.


Detecting and Classifying Fractal Patterns Using Machine Learning
In this article, we will touch upon the intriguing topic of fractal analysis and market forecasting using machine learning. These are just the first steps towards exploring the diverse fractal structures that form on financial price charts. We will use the correlation to find patterns and the CatBoost algorithm to classify these patterns.