MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Neural Networks in Trading: Enhancing Transformer Efficiency by Reducing Sharpness (Final Part)
SAMformer offers a solution to the key drawbacks of Transformer models in long-term time series forecasting, such as training complexity and poor generalization on small datasets. Its shallow architecture and sharpness-aware optimization help avoid suboptimal local minima. In this article, we will continue to implement approaches using MQL5 and evaluate their practical value.

MetaTrader tick info access from MQL5 services to Python application using sockets
Sometimes everything is not programmable in the MQL5 language. And even if it is possible to convert existing advanced libraries in MQL5, it would be time-consuming. This article tries to show that we can bypass Windows OS dependency by transporting tick information such as bid, ask and time with MetaTrader services to a Python application using sockets.

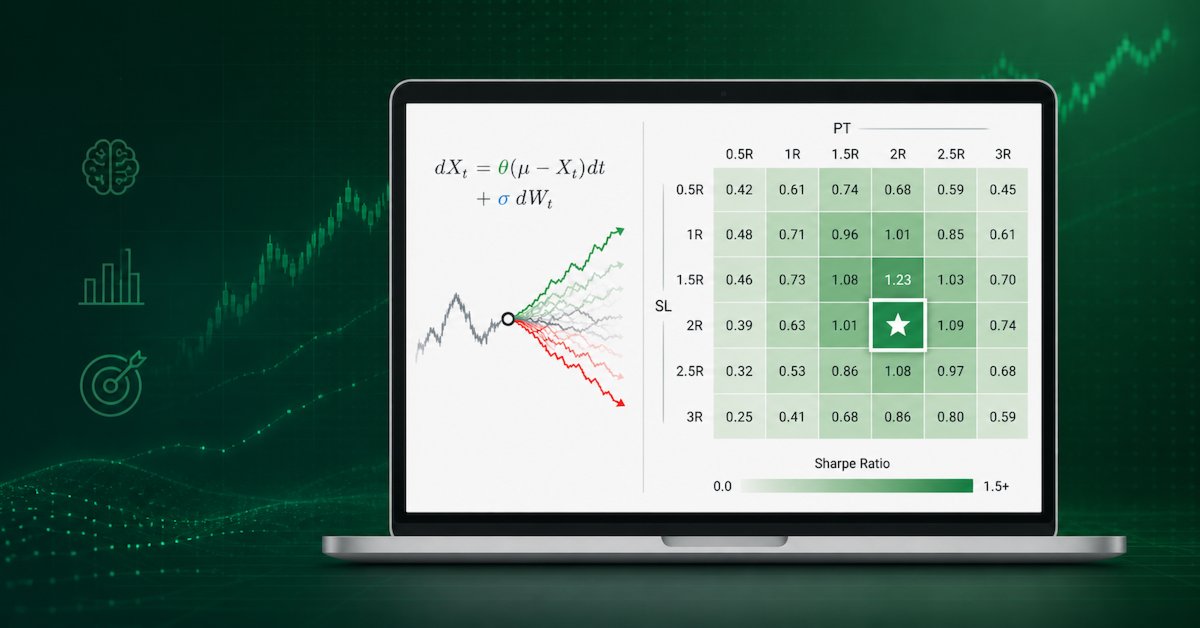
MetaTrader 5 Machine Learning Blueprint (Part 15): How to Calibrate Profit-Taking and Stop-Loss Targets from Synthetic Data
This article applies the Optimal Trading Rule from AFML Chapter 13 to set profit targets and stop-losses without in-sample calibration. We model post-entry P&L with a discrete Ornstein–Uhlenbeck process, run a 100,000-path search, and implement Python, multiprocessing, and a Numba @njit parallel kernel (242× faster). The result is an optimal (PT, SL) under three forecast specifications, constrained by the prop-firm daily loss limit.


Creating a Trading Administrator Panel in MQL5 (Part IX): Code Organization (IV): Trade Management Panel class
This discussion covers the updated TradeManagementPanel in our New_Admin_Panel EA. The update enhances the panel by using built-in classes to offer a user-friendly trade management interface. It includes trading buttons for opening positions and controls for managing existing trades and pending orders. A key feature is the integrated risk management that allows setting stop loss and take profit values directly in the interface. This update improves code organization for large programs and simplifies access to order management tools, which are often complex in the terminal.


Reimagining Classic Strategies (Part III): Forecasting Higher Highs And Lower Lows
In this series article, we will empirically analyze classic trading strategies to see if we can improve them using AI. In today's discussion, we tried to predict higher highs and lower lows using the Linear Discriminant Analysis model.


Mining Central Bank Balance Sheet Data to Get a Picture of Global Liquidity
Mining central bank balance sheet data provides a picture of global liquidity in the Forex market and key currencies. We combine data from the Fed, ECB, BOJ and PBoC into a composite index and use machine learning to uncover hidden patterns. This approach turns raw data into real trading signals by combining fundamental and technical analysis.


Neural Networks in Trading: Disentangling Structured Components (Encoder)
We invite you to explore the next stage in implementing the SCNN framework, which combines flexibility and interpretability, allowing structural components of a time series to be identified precisely. The article provides a detailed explanation of the mechanisms of adaptive normalization and attention, which ensure the model's resilience to changing market conditions.

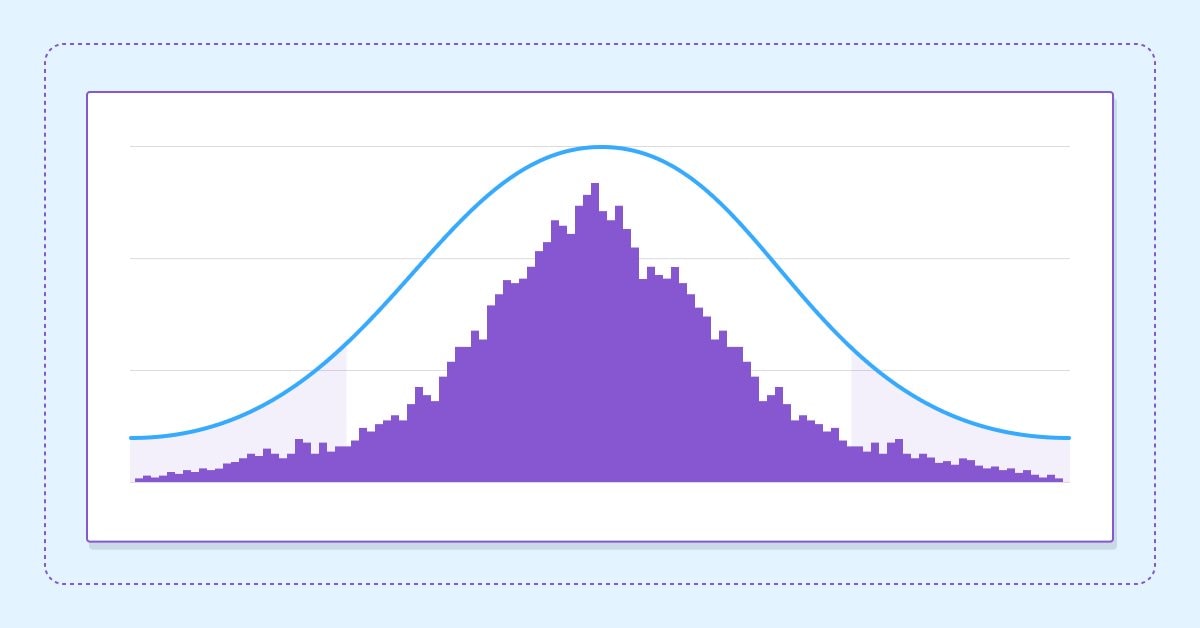
Estimate future performance with confidence intervals
In this article we delve into the application of boostrapping techniques as a means to estimate the future performance of an automated strategy.

Using association rules in Forex data analysis
How to apply predictive rules of supermarket retail analytics to the real Forex market? How are purchases of cookies, milk and bread related to stock exchange transactions? The article discusses an innovative approach to algorithmic trading based on the use of association rules.

Neural Networks in Trading: Using Language Models for Time Series Forecasting
We continue to study time series forecasting models. In this article, we get acquainted with a complex algorithm built on the use of a pre-trained language model.

Data Science and ML (Part 29): Essential Tips for Selecting the Best Forex Data for AI Training Purposes
In this article, we dive deep into the crucial aspects of choosing the most relevant and high-quality Forex data to enhance the performance of AI models.


Self Optimizing Expert Advisor With MQL5 And Python (Part IV): Stacking Models
Today, we will demonstrate how you can build AI-powered trading applications capable of learning from their own mistakes. We will demonstrate a technique known as stacking, whereby we use 2 models to make 1 prediction. The first model is typically a weaker learner, and the second model is typically a more powerful model that learns the residuals of our weaker learner. Our goal is to create an ensemble of models, to hopefully attain higher accuracy.

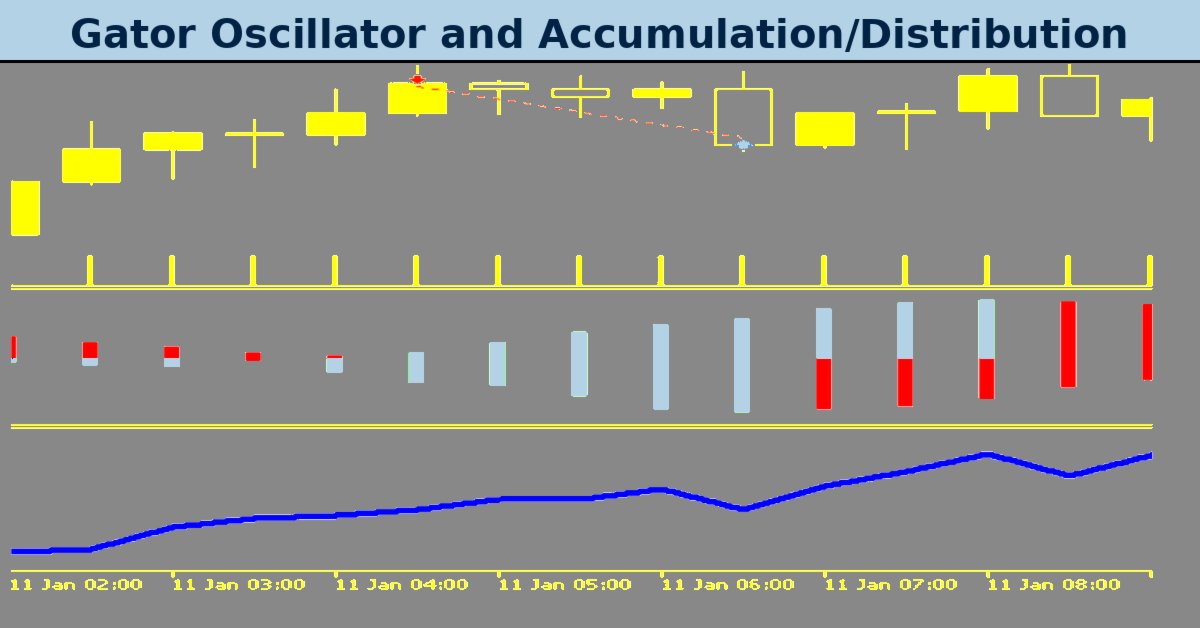
MQL5 Wizard Techniques you should know (Part 77): Using Gator Oscillator and the Accumulation/Distribution Oscillator
The Gator Oscillator by Bill Williams and the Accumulation/Distribution Oscillator are another indicator pairing that could be used harmoniously within an MQL5 Expert Advisor. We use the Gator Oscillator for its ability to affirm trends, while the A/D is used to provide confirmation of the trends via checks on volume. In exploring this indicator pairing, as always, we use the MQL5 wizard to build and test out their potential.


Neural Networks in Trading: Dual Clustering of Multivariate Time Series (Final Part)
We continue to implement approaches proposed vy the authors of the DUET framework, which offers an innovative approach to time series analysis, combining temporal and channel clustering to uncover hidden patterns in the analyzed data.


Gain An Edge Over Any Market (Part II): Forecasting Technical Indicators
Did you know that we can gain more accuracy forecasting certain technical indicators than predicting the underlying price of a traded symbol? Join us to explore how to leverage this insight for better trading strategies.

Trading with the MQL5 Economic Calendar (Part 4): Implementing Real-Time News Updates in the Dashboard
This article enhances our Economic Calendar dashboard by implementing real-time news updates to keep market information current and actionable. We integrate live data fetching techniques in MQL5 to update events on the dashboard continuously, improving the responsiveness of the interface. This update ensures that we can access the latest economic news directly from the dashboard, optimizing trading decisions based on the freshest data.

MQL5 Wizard Techniques you should know (Part 61): Using Patterns of ADX and CCI with Supervised Learning
The ADX Oscillator and CCI oscillator are trend following and momentum indicators that can be paired when developing an Expert Advisor. We look at how this can be systemized by using all the 3 main training modes of Machine Learning. Wizard Assembled Expert Advisors allow us to evaluate the patterns presented by these two indicators, and we start by looking at how Supervised-Learning can be applied with these Patterns.


Exploring Machine Learning in Unidirectional Trend Trading Using Gold as a Case Study
This article discusses an approach to trading only in the chosen direction (buy or sell). For this purpose, the technique of causal inference and machine learning are used.

Neural Networks in Trading: Transformer with Relative Encoding
Self-supervised learning can be an effective way to analyze large amounts of unlabeled data. The efficiency is provided by the adaptation of models to the specific features of financial markets, which helps improve the effectiveness of traditional methods. This article introduces an alternative attention mechanism that takes into account the relative dependencies and relationships between inputs.

DoEasy. Controls (Part 16): TabControl WinForms object — several rows of tab headers, stretching headers to fit the container
In this article, I will continue the development of TabControl and implement the arrangement of tab headers on all four sides of the control for all modes of setting the size of headers: Normal, Fixed and Fill To Right.


Neural Networks Made Easy (Part 93): Adaptive Forecasting in Frequency and Time Domains (Final Part)
In this article, we continue the implementation of the approaches of the ATFNet model, which adaptively combines the results of 2 blocks (frequency and time) within time series forecasting.

Self Optimizing Expert Advisors in MQL5 (Part 10): Matrix Factorization
Factorization is a mathematical process used to gain insights into the attributes of data. When we apply factorization to large sets of market data — organized in rows and columns — we can uncover patterns and characteristics of the market. Factorization is a powerful tool, and this article will show how you can use it within the MetaTrader 5 terminal, through the MQL5 API, to gain more profound insights into your market data.

Interview with Ge Senlin (ATC 2011)
The Expert Advisor by Ge Senlin (yyy999) from China got featured in the top ten of the Automated Trading Championship 2011 in late October and hasn't left it since then. Not often participants from the PRC show good results in the Championship - Forex trading is not allowed in this country. After the poor results in the previous year ATC, Senlin has prepared a new multicurrency Expert Advisor that never closes loss positions and uses position increase instead. Let's see whether this EA will be able to rise even higher with such a risky strategy.


Price Action Analysis Toolkit Development (Part 69): Flag Pattern Detection in MQL5
This article shows how to convert subjective flag recognition into reproducible MQL5 logic for live charts. It combines ATR-normalized pole strength, retracement limits, consolidation structure checks, breakout confirmation, and overlap control. Readers gain a workable approach that renders adaptive channels and zones, updates active setups efficiently, and provides optional alerts for newly confirmed patterns.


From Simple Close Buttons to a Rule-Based Risk Dashboard in MQL5
Build a rule-based on-chart risk management panel in MetaTrader 5 using the MQL5 Standard Library. The guide covers a CAppDialog-based GUI, manual event routing, and an automated update loop. You will bind UI events to CTrade to execute conditional closures, show net floating P/L, and read automated targets directly from the chart.


Statistical Arbitrage Through Cointegrated Stocks (Part 2): Expert Advisor, Backtests, and Optimization
This article presents a sample Expert Advisor implementation for trading a basket of four Nasdaq stocks. The stocks were initially filtered based on Pearson correlation tests. The filtered group was then tested for cointegration with Johansen tests. Finally, the cointegrated spread was tested for stationarity with the ADF and KPSS tests. Here we will see some notes about this process and the results of the backtests after a small optimization.


Indicator of historical positions on the chart as their profit/loss diagram
In this article, I will consider the option of obtaining information about closed positions based on their trading history. Besides, I will create a simple indicator that displays the approximate profit/loss of positions on each bar as a diagram.


Price Action Analysis Toolkit Development (Part 34): Turning Raw Market Data into Predictive Models Using an Advanced Ingestion Pipeline
Have you ever missed a sudden market spike or been caught off‑guard when one occurred? The best way to anticipate live events is to learn from historical patterns. Intending to train an ML model, this article begins by showing you how to create a script in MetaTrader 5 that ingests historical data and sends it to Python for storage—laying the foundation for your spike‑detection system. Read on to see each step in action.


MQL5 Trading Tools (Part 15): Canvas Blur Effects, Shadow Rendering, and Smooth Mouse Wheel Scrolling
In this article, we enhance the MQL5 canvas dashboard with advanced visual effects, including blur gradients for fog overlays, shadow rendering for headers, and antialiased drawing for smoother lines and curves. We add smooth mouse wheel scrolling to the text panel that does not interfere with the chart zoom scale, technically an upgrade.


Developing a multi-currency Expert Advisor (Part 21): Preparing for an important experiment and optimizing the code
For further progress it would be good to see if we can improve the results by periodically re-running the automatic optimization and generating a new EA. The stumbling block in many debates about the use of parameter optimization is the question of how long the obtained parameters can be used for trading in the future period while maintaining the profitability and drawdown at the specified levels. And is it even possible to do this?


Price Action Analysis Toolkit Development (Part 59): Using Geometric Asymmetry to Identify Precision Breakouts from Fractal Consolidation
While studying a wide range of breakout setups, I noticed that failed breakouts were rarely caused by a lack of volatility, but more often by weak internal structure. That observation led to the framework presented in this article. The approach identifies patterns where the final price leg shows superior length, steepness, and speed—clear signs of momentum accumulation ahead of directional expansion. By detecting these subtle geometric imbalances within consolidation, traders can anticipate higher-probability breakouts before price exits the range. Continue reading to see how this fractal-based, geometric framework translates structural imbalance into precise breakout signals.

DoEasy. Controls (Part 17): Cropping invisible object parts, auxiliary arrow buttons WinForms objects
In this article, I will create the functionality for hiding object sections located beyond their containers. Besides, I will create auxiliary arrow button objects to be used as part of other WinForms objects.

Neural Networks in Trading: State Space Models
A large number of the models we have reviewed so far are based on the Transformer architecture. However, they may be inefficient when dealing with long sequences. And in this article, we will get acquainted with an alternative direction of time series forecasting based on state space models.


Developing a Replay System (Part 59): A New Future
Having a proper understanding of different ideas allows us to do more with less effort. In this article, we'll look at why it's necessary to configure a template before the service can interact with the chart. Also, what if we improve the mouse pointer so we can do more things with it?


Data label for time series mining (Part 6):Apply and Test in EA Using ONNX
This series of articles introduces several time series labeling methods, which can create data that meets most artificial intelligence models, and targeted data labeling according to needs can make the trained artificial intelligence model more in line with the expected design, improve the accuracy of our model, and even help the model make a qualitative leap!


Angular Analysis of Price Movements: A Hybrid Model for Predicting Financial Markets
What is angular analysis of financial markets? How to use price action angles and machine learning to make accurate forecasts with 67% accuracy? How to combine a regression and classification model with angular features and obtain a working algorithm? What does Gann have to do with it? Why are price movement angles a good indicator for machine learning?

Neural networks made easy (Part 39): Go-Explore, a different approach to exploration
We continue studying the environment in reinforcement learning models. And in this article we will look at another algorithm – Go-Explore, which allows you to effectively explore the environment at the model training stage.


Integrate Your Own LLM into EA (Part 3): Training Your Own LLM with CPU
With the rapid development of artificial intelligence today, language models (LLMs) are an important part of artificial intelligence, so we should think about how to integrate powerful LLMs into our algorithmic trading. For most people, it is difficult to fine-tune these powerful models according to their needs, deploy them locally, and then apply them to algorithmic trading. This series of articles will take a step-by-step approach to achieve this goal.


Implementation of the Augmented Dickey Fuller test in MQL5
In this article we demonstrate the implementation of the Augmented Dickey-Fuller test, and apply it to conduct cointegration tests using the Engle-Granger method.

Price movement discretization methods in Python
We will look at price discretization methods using Python + MQL5. In this article, I will share my practical experience developing a Python library that implements a wide range of approaches to bar formation — from classic Volume and Range bars to more exotic methods like Renko and Kagi. We will consider three-line breakout candles and range bars analyzing their statistics and trying to define how else the prices can be represented discretely.