MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

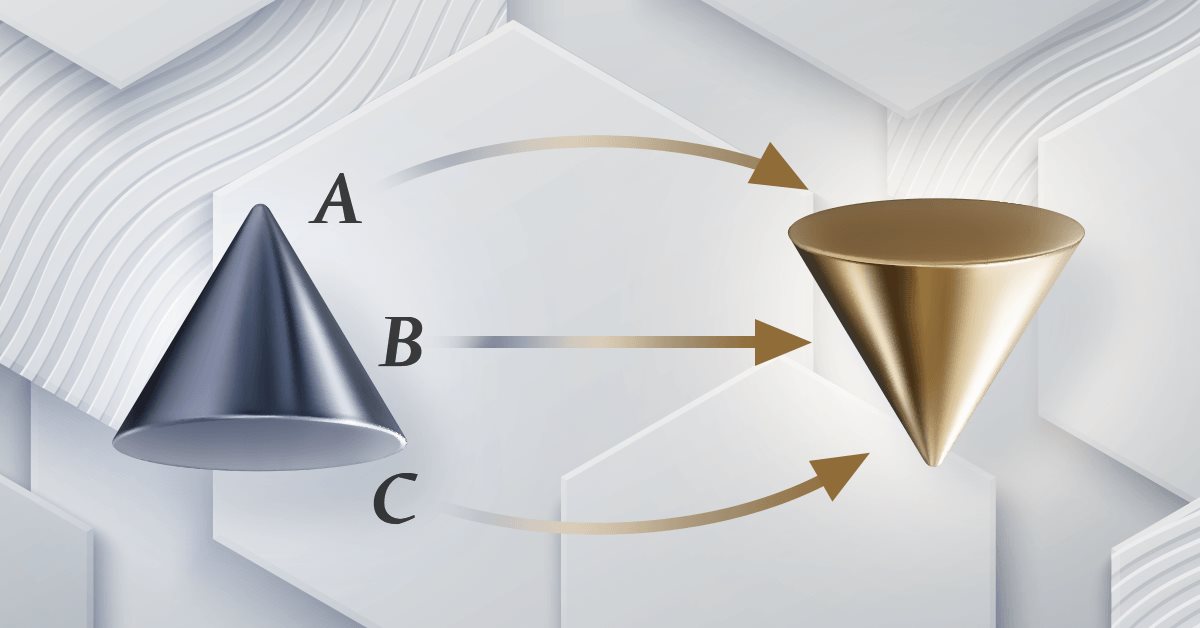
Category Theory in MQL5 (Part 22): A different look at Moving Averages
In this article we attempt to simplify our illustration of concepts covered in these series by dwelling on just one indicator, the most common and probably the easiest to understand. The moving average. In doing so we consider significance and possible applications of vertical natural transformations.


MQL5 Wizard Techniques you should know (Part 49): Reinforcement Learning with Proximal Policy Optimization
Proximal Policy Optimization is another algorithm in reinforcement learning that updates the policy, often in network form, in very small incremental steps to ensure the model stability. We examine how this could be of use, as we have with previous articles, in a wizard assembled Expert Advisor.


Low-Frequency Quantitative Strategies in Metatrader 5: (Part 2) Backtesting a Lead/Lag Analysis in SQL and in Metatrader 5
The article describes a complete pipeline that uses data analysis for finding low-frequency lead/lag trading opportunities. It goes into building a cross-correlation-based Lead/Lag analyser step-by-step, with special attention to the most common errors beginners may commit while developing cross-asset diffusion queries. After screening dozens of cointegrated and correlated pairs, a trading candidate pair is chosen, and its tradeability is evaluated in a pure SQL backtest. Once it is qualified, the strategy is backtested on the MetaTester for parameter optimization. The Expert Advisor with respective backtest settings and optimization inputs is provided, along with Python and SQL scripts.

Developing a Replay System — Market simulation (Part 10): Using only real data for Replay
Here we will look at how we can use more reliable data (traded ticks) in the replay system without worrying about whether it is adjusted or not.


A Generic Optimization Formulation (GOF) to Implement Custom Max with Constraints
In this article we will present a way to implement optimization problems with multiple objectives and constraints when selecting "Custom Max" in the Setting tab of the MetaTrader 5 terminal. As an example, the optimization problem could be: Maximize Profit Factor, Net Profit, and Recovery Factor, such that the Draw Down is less than 10%, the number of consecutive losses is less than 5, and the number of trades per week is more than 5.

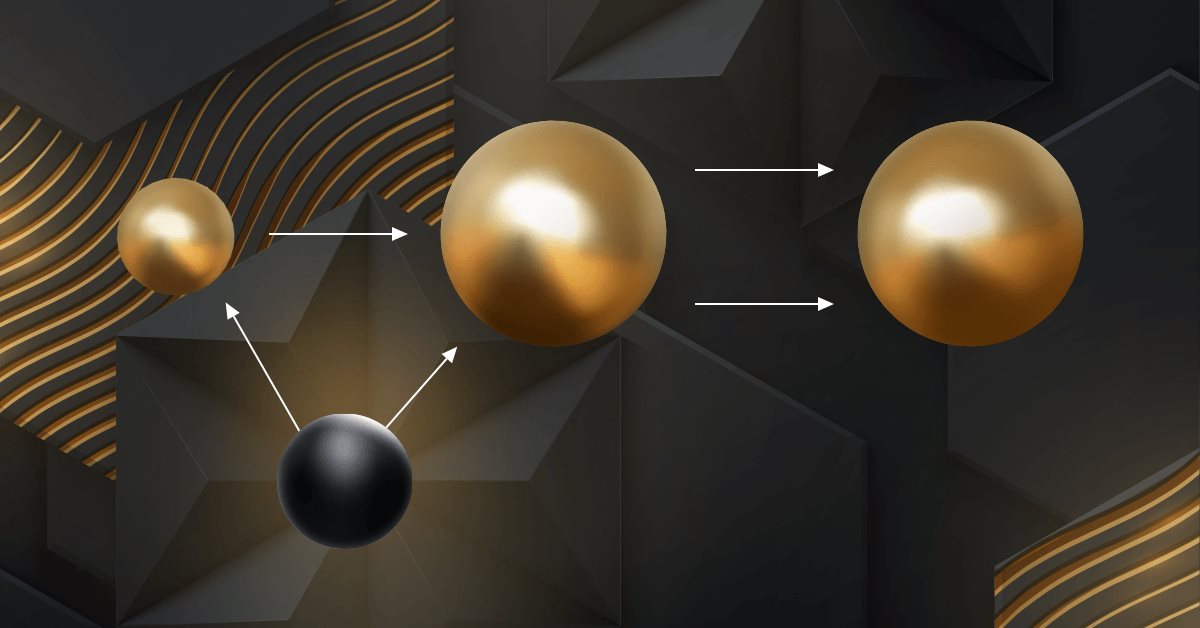
Category Theory in MQL5 (Part 5): Equalizers
Category Theory is a diverse and expanding branch of Mathematics which is only recently getting some coverage in the MQL5 community. These series of articles look to explore and examine some of its concepts & axioms with the overall goal of establishing an open library that provides insight while also hopefully furthering the use of this remarkable field in Traders' strategy development.

Propensity score in causal inference
The article examines the topic of matching in causal inference. Matching is used to compare similar observations in a data set. This is necessary to correctly determine causal effects and get rid of bias. The author explains how this helps in building trading systems based on machine learning, which become more stable on new data they were not trained on. The propensity score plays a central role and is widely used in causal inference.


Neural Networks in Trading: Contrastive Pattern Transformer
The Contrastive Transformer is designed to analyze markets both at the level of individual candlesticks and based on entire patterns. This helps improve the quality of market trend modeling. Moreover, the use of contrastive learning to align representations of candlesticks and patterns fosters self-regulation and improves the accuracy of forecasts.

From Novice to Expert: Animated News Headline Using MQL5 (I)
News accessibility is a critical factor when trading on the MetaTrader 5 terminal. While numerous news APIs are available, many traders face challenges in accessing and integrating them effectively into their trading environment. In this discussion, we aim to develop a streamlined solution that brings news directly onto the chart—where it’s most needed. We'll accomplish this by building a News Headline Expert Advisor that monitors and displays real-time news updates from API sources.


Making Custom Indicators for Beginners (Part 1): SuperTrend Indicator
This article builds a robust SuperTrend indicator in MQL5 using ATR-based bands, a ratchet mechanism, and strict series indexing to avoid silent recursion errors and repainting on closed bars. We walk through buffer binding, ATR handle management, seeding, and arrow confirmation logic. A companion EA demonstrates practical integration


Larry Williams Market Secrets (Part 8): Combining Volatility, Structure and Time Filters
An in-depth walkthrough of building a Larry Williams inspired volatility breakout Expert Advisor in MQL5, combining swing structure, volatility-based entries, trade day of the week filtering, time filters, and flexible risk management, with a complete implementation and reproducible test setup.


Neural Networks in Trading: Controlled Segmentation (Final Part)
We continue the work started in the previous article on building the RefMask3D framework using MQL5. This framework is designed to comprehensively study multimodal interaction and feature analysis in a point cloud, followed by target object identification based on a description provided in natural language.


MQL5 Trading Tools (Part 9): Developing a First Run User Setup Wizard for Expert Advisors with Scrollable Guide
In this article, we develop an MQL5 First Run User Setup Wizard for Expert Advisors, featuring a scrollable guide with an interactive dashboard, dynamic text formatting, and visual controls like buttons and a checkbox allowing users to navigate instructions and configure trading parameters efficiently. Users of the program get to have insight of what the program is all about and what to do on the first run, more like an orientation model.


The MQL5 Standard Library Explorer (Part 4): Custom Signal Library
Today, we use the MQL5 Standard Library to build custom signal classes and let the MQL5 Wizard assemble a professional Expert Advisor for us. This approach simplifies development so that even beginner programmers can create robust EAs without in-depth coding knowledge, focusing instead on tuning inputs and optimizing performance. Join this discussion as we explore the process step by step.


Hidden Markov Models in Machine Learning-Based Trading Systems
Hidden Markov Models (HMMs) are a powerful class of probabilistic models designed to analyze sequential data, where observed events depend on some sequence of unobserved (hidden) states that form a Markov process. The main assumptions of HMM include the Markov property for hidden states, meaning that the probability of transition to the next state depends only on the current state, and the independence of observations given knowledge of the current hidden state.


Creating Custom Indicators in MQL5 (Part 3): Multi-Gauge Enhancements with Sector and Round Styles
In this article, we enhance the gauge-based indicator in MQL5 to support multiple oscillators, allowing user selection through an enumeration for single or combined displays. We introduce sector and round gauge styles via derived classes from a base gauge framework, improving case rendering with arcs, lines, and polygons for a more refined visual appearance.


A Reinforcement Learning System for Algorithmic Trading in MQL5
The article describes the development of a multi-agent machine learning system for algorithmic trading on MetaTrader 5 based on reinforcement learning. The system has a three-tier architecture: memory neurons store experience, agents make independent decisions, and the collective mind combines them through weighted voting. The system is continuously improved through Q-learning, pruning of ineffective neurons, and evolutionary reduction of exploration.


Developing A Swing Entries Monitoring (EA)
As the year approaches its end, long-term traders often reflect on market history to analyze its behavior and trends, aiming to project potential future movements. In this article, we will explore the development of a long-term entry monitoring Expert Advisor (EA) using MQL5. The objective is to address the challenge of missed long-term trading opportunities caused by manual trading and the absence of automated monitoring systems. We'll use one of the most prominently traded pairs as an example to strategize and develop our solution effectively.


Neural networks made easy (Part 51): Behavior-Guided Actor-Critic (BAC)
The last two articles considered the Soft Actor-Critic algorithm, which incorporates entropy regularization into the reward function. This approach balances environmental exploration and model exploitation, but it is only applicable to stochastic models. The current article proposes an alternative approach that is applicable to both stochastic and deterministic models.


Developing a Replay System — Market simulation (Part 14): Birth of the SIMULATOR (IV)
In this article we will continue the simulator development stage. this time we will see how to effectively create a RANDOM WALK type movement. This type of movement is very intriguing because it forms the basis of everything that happens in the capital market. In addition, we will begin to understand some concepts that are fundamental to those conducting market analysis.


Graph Theory: Traversal Depth-First Search (DFS) Applied in Trading
This article applies Depth-First Search to market structure by modeling swing highs and lows as graph nodes and tracking one structural path as deeply as conditions remain valid. When a key swing is broken, the algorithm backtracks and explores an alternative branch. Readers gain a practical framework to formalize structural bias and test whether the current path aligns with targets like liquidity pools or supply and demand zones.

Neural Networks in Trading: Hybrid Graph Sequence Models (Final Part)
We continue exploring hybrid graph sequence models (GSM++), which integrate the advantages of different architectures, providing high analysis accuracy and efficient distribution of computing resources. These models effectively identify hidden patterns, reducing the impact of market noise and improving forecasting quality.


Developing Market Entropy Indicator: Trading System Based on Information Theory
This article explores the development of a Market Entropy Indicator based on principles from Information Theory to measure the uncertainty and information content within financial markets. By applying concepts such as Shannon Entropy to price movements, the indicator quantifies whether the market is structured (trending), transitioning, or chaotic.

MQL5 Wizard Techniques you should know (Part 24): Moving Averages
Moving Averages are a very common indicator that are used and understood by most Traders. We explore possible use cases that may not be so common within MQL5 Wizard assembled Expert Advisors.


The MQL5 Standard Library Explorer (Part 3): Expert Standard Deviation Channel
In this discussion, we will develop an Expert Advisor using the CTrade and CChartObjectStdDevChannel classes, while applying several filters to enhance profitability. This stage puts our previous discussion into practical application. Additionally, I’ll introduce another simple approach to help you better understand the MQL5 Standard Library and its underlying codebase. Join the discussion to explore these concepts in action.


Price Action Analysis Toolkit Development (Part 45): Creating a Dynamic Level-Analysis Panel in MQL5
In this article, we explore a powerful MQL5 tool that let's you test any price level you desire with just one click. Simply enter your chosen level and press analyze, the EA instantly scans historical data, highlights every touch and breakout on the chart, and displays statistics in a clean, organized dashboard. You'll see exactly how often price respected or broke through your level, and whether it behaved more like support or resistance. Continue reading to explore the detailed procedure.


Population optimization algorithms: Differential Evolution (DE)
In this article, we will consider the algorithm that demonstrates the most controversial results of all those discussed previously - the differential evolution (DE) algorithm.

Neural Networks Made Easy (Part 86): U-Shaped Transformer
We continue to study timeseries forecasting algorithms. In this article, we will discuss another method: the U-shaped Transformer.

Alternative risk return metrics in MQL5
In this article we present the implementation of several risk return metrics billed as alternatives to the Sharpe ratio and examine hypothetical equity curves to analyze their characteristics.

Trading with the MQL5 Economic Calendar (Part 3): Adding Currency, Importance, and Time Filters
In this article, we implement filters in the MQL5 Economic Calendar dashboard to refine news event displays by currency, importance, and time. We first establish filter criteria for each category and then integrate these into the dashboard to display only relevant events. Finally, we ensure each filter dynamically updates to provide traders with focused, real-time economic insights.

Elements of correlation analysis in MQL5: Pearson chi-square test of independence and correlation ratio
The article observes classical tools of correlation analysis. An emphasis is made on brief theoretical background, as well as on the practical implementation of the Pearson chi-square test of independence and the correlation ratio.


Time Evolution Travel Algorithm (TETA)
This is my own algorithm. The article presents the Time Evolution Travel Algorithm (TETA) inspired by the concept of parallel universes and time streams. The basic idea of the algorithm is that, although time travel in the conventional sense is impossible, we can choose a sequence of events that lead to different realities.

Multiple Symbol Analysis With Python And MQL5 (Part I): NASDAQ Integrated Circuit Makers
Join us as we discuss how you can use AI to optimize your position sizing and order quantities to maximize the returns of your portfolio. We will showcase how to algorithmically identify an optimal portfolio and tailor your portfolio to your returns expectations or risk tolerance levels. In this discussion, we will use the SciPy library and the MQL5 language to create an optimal and diversified portfolio using all the data we have.


Quantitative Analysis of Trends: Collecting Statistics in Python
What is quantitative trend analysis in the Forex market? We collect statistics on trends, their magnitude and distribution across the EURUSD currency pair. How quantitative trend analysis can help you create a profitable trading expert advisor.


Feature Engineering for ML (Part 1): Fractional Differentiation — Stationarity Without Memory Loss
Integer differentiation forces a binary choice between stationarity and memory: returns (d=1) are stationary but discard all price-level information; raw prices (d=0) preserve memory but violate ML stationarity assumptions. We implement the fixed-width fractional differentiation (FFD) method from AFML Chapter 5, covering get_weights_ffd (iterative recurrence with threshold cutoff), frac_diff_ffd (bounded dot product per bar), and fracdiff_optimal (binary search for minimum stationary d*).

Interview with Sergey Nikitin (ATC 2011)
In the second week of the competition, the Expert Advisor of Sergey Nikitin (VNIK) trading on two currency pairs EURUSD and EURJPY got featured on the very top drawing away from the rest. Multicurrency Expert Advisors always attract attention in the Championship, especially those that show good results. We talked with Sergey about the role of luck in a trader's life and his way of trading.

Data Science and ML (Part 43): Hidden Patterns Detection in Indicators Data Using Latent Gaussian Mixture Models (LGMM)
Have you ever looked at the chart and felt that strange sensation… that there’s a pattern hidden just beneath the surface? A secret code that might reveal where prices are headed if only you could crack it? Meet LGMM, the Market’s Hidden Pattern Detector. A machine learning model that helps identify those hidden patterns in the market.


Integrate Your Own LLM into EA (Part 5): Develop and Test Trading Strategy with LLMs (II)-LoRA-Tuning
With the rapid development of artificial intelligence today, language models (LLMs) are an important part of artificial intelligence, so we should think about how to integrate powerful LLMs into our algorithmic trading. For most people, it is difficult to fine-tune these powerful models according to their needs, deploy them locally, and then apply them to algorithmic trading. This series of articles will take a step-by-step approach to achieve this goal.

Interview with Matúš German (ATC 2011)
On the second day of the Championship the Expert Advisor created by Matúš German (gery18) increased its capital by 2.5 times and took the lead being ahead of all competitors. Matúš himself doubts his Expert Advisor will win, he thinks that luck and high risk were the reasons of such unexpected rise.


Reimagining Classic Strategies (Part 17): Modelling Technical Indicators
In this discussion, we focus on how we can break the glass ceiling imposed by classical machine learning techniques in finance. It appears that the greatest limitation to the value we can extract from statistical models does not lie in the models themselves — neither in the data nor in the complexity of the algorithms — but rather in the methodology we use to apply them. In other words, the true bottleneck may be how we employ the model, not the model’s intrinsic capability.