MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Brain Storm Optimization algorithm (Part II): Multimodality
In the second part of the article, we will move on to the practical implementation of the BSO algorithm, conduct tests on test functions and compare the efficiency of BSO with other optimization methods.


Risk-Based Trade Placement EA with On-Chart UI (Part 2): Adding Interactivity and Logic
Learn how to build an interactive MQL5 Expert Advisor with an on-chart control panel. Know how to compute risk-based lot sizes and place trades directly from the chart.


MQL5 Trading Tools (Part 11): Correlation Matrix Dashboard (Pearson, Spearman, Kendall) with Heatmap and Standard Modes
In this article, we build a correlation matrix dashboard in MQL5 to compute asset relationships using Pearson, Spearman, and Kendall methods over a set timeframe and bars. The system offers standard mode with color thresholds and p-value stars, plus heatmap mode with gradient visuals for correlation strengths. It includes an interactive UI with timeframe selectors, mode toggles, and a dynamic legend for efficient analysis of symbol interdependencies.


Creating an MQL5-Telegram Integrated Expert Advisor (Part 7): Command Analysis for Indicator Automation on Charts
In this article, we explore how to integrate Telegram commands with MQL5 to automate the addition of indicators on trading charts. We cover the process of parsing user commands, executing them in MQL5, and testing the system to ensure smooth indicator-based trading


Polynomial models in trading
This article is about orthogonal polynomials. Their use can become the basis for a more accurate and effective analysis of market information allowing traders to make more informed decisions.

Interview with Valery Mazurenko (ATC 2011)
The task of writing an Expert Advisor trading on multiple currency pairs is complex both in terms of finding suitable strategies and from the technological side. But if the goal is set clear, nothing is impossible then. It was four times already that Vitaly Mazurenko (notused) submitted his multi-currency Expert Advisor. It seems, he has managed to find the right way this time.


Neural networks made easy (Part 60): Online Decision Transformer (ODT)
The last two articles were devoted to the Decision Transformer method, which models action sequences in the context of an autoregressive model of desired rewards. In this article, we will look at another optimization algorithm for this method.


Codex Pipelines, from Python to MQL5, for Indicator Selection: A Multi-Quarter Analysis of the XLF ETF with Machine Learning
We continue our look at how the selection of indicators can be pipelined when facing a ‘none-typical’ MetaTrader asset. MetaTrader 5 is primarily used to trade forex, and that is good given the liquidity on offer, however the case for trading outside of this ‘comfort-zone’, is growing bolder with not just the overnight rise of platforms like Robinhood, but also the relentless pursuit of an edge for most traders. We consider the XLF ETF for this article and also cap our revamped pipeline with a simple MLP.

Andrey Bolkonsky (abolk): "Any programmer knows that there is no software without bugs"
Andrey Bolkonsky (abolk) has been participating in the Jobs service since its opening. He has developed dozens of indicators and Expert Advisors for the MetaTrader 4 and MetaTrader 5 platforms. We will talk with Andrey about what a server is from the perspective of a programmer.

MQL5 Wizard Techniques you should know (Part 13): DBSCAN for Expert Signal Class
Density Based Spatial Clustering for Applications with Noise is an unsupervised form of grouping data that hardly requires any input parameters, save for just 2, which when compared to other approaches like k-means, is a boon. We delve into how this could be constructive for testing and eventually trading with Wizard assembled Expert Advisers


Market Simulation (Part 14): Sockets (VIII)
Many programmers might assume we should abandon using Excel and move directly to Python, using some packages that allow Python to generate an Excel file for later analysis of results. However, as mentioned in the previous article, although this solution is the simplest for many programmers, it will not be accepted by some users. And in this particular case, the user is always right. As programmers, we must find a way to make everything work.

Developing a Replay System (Part 27): Expert Advisor project — C_Mouse class (I)
In this article we will implement the C_Mouse class. It provides the ability to program at the highest level. However, talking about high-level or low-level programming languages is not about including obscene words or jargon in the code. It's the other way around. When we talk about high-level or low-level programming, we mean how easy or difficult the code is for other programmers to understand.


Adaptive Malaysian Engulfing Indicator (Part 2): Optimized Retest Bar Range
The article adds a self-adaptive layer to the Malaysian Engulfing indicator by optimizing the retest bar range with a constrained brute-force search scored by MFE and MAE. It details the data model, helper routines, and an MQL5 implementation that gathers historical setups, computes excursions, and selects the best parameter. Readers learn how to remove manual tuning and run the indicator with context-appropriate settings across symbols and timeframes.


From Novice to Expert: Adaptive Risk Management for Liquidity Strategies
In this article, we explore practical and robust risk management techniques specifically tailored for liquidity-based trading. You will learn how to protect positions during retests, handle false breakouts with confidence, and identify signs of potential level manipulation. By the end, you will have built an adaptive Expert Advisor capable of managing zone flips and executing strategic pending orders with integrated risk control.

Dimitar Manov: "I fear only extraordinary situations in the Championship" (ATC 2010)
In the recent review by Boris Odintsov the Expert Advisor of the Bulgarian Participant Dimitar Manov appeared among the most stable and reliable EAs. We decided to interview this developer and try to find the secret of his success. In this interview Dimitar has told us what situation would be unfavorable for his robot, why he's not using indicators and whether he is expecting to win the competition.


Category Theory in MQL5 (Part 13): Calendar Events with Database Schemas
This article, that follows Category Theory implementation of Orders in MQL5, considers how database schemas can be incorporated for classification in MQL5. We take an introductory look at how database schema concepts could be married with category theory when identifying trade relevant text(string) information. Calendar events are the focus.


Developing a Replay System (Part 74): New Chart Trade (I)
In this article, we will modify the last code shown in this series about Chart Trade. These changes are necessary to adapt the code to the current replay/simulation system model. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


MQL5 Wizard Techniques you should know (Part 37): Gaussian Process Regression with Linear and Matérn Kernels
Linear Kernels are the simplest matrix of its kind used in machine learning for linear regression and support vector machines. The Matérn kernel on the other hand is a more versatile version of the Radial Basis Function we looked at in an earlier article, and it is adept at mapping functions that are not as smooth as the RBF would assume. We build a custom signal class that utilizes both kernels in forecasting long and short conditions.

Mastering Log Records (Part 1): Fundamental Concepts and First Steps in MQL5
Welcome to the beginning of another journey! This article opens a special series where we will create, step by step, a library for log manipulation, tailored for those who develop in the MQL5 language.


MetaTrader 5 Machine Learning Blueprint (Part 14): Transaction Cost Modeling for Triple-Barrier Labels in MQL5
The article replaces hardcoded cost assumptions in triple-barrier labeling with measured inputs. An MQL5 script captures spread distribution, swap rates, and symbol metadata from your broker, and a Python model converts them into a broker-calibrated min ret you can pass to get events. Labels then reflect the actual round-trip friction for your instrument and holding period.


Neural networks made easy (Part 68): Offline Preference-guided Policy Optimization
Since the first articles devoted to reinforcement learning, we have in one way or another touched upon 2 problems: exploring the environment and determining the reward function. Recent articles have been devoted to the problem of exploration in offline learning. In this article, I would like to introduce you to an algorithm whose authors completely eliminated the reward function.


Turtle Shell Evolution Algorithm (TSEA)
This is a unique optimization algorithm inspired by the evolution of the turtle shell. The TSEA algorithm emulates the gradual formation of keratinized skin areas, which represent optimal solutions to a problem. The best solutions become "harder" and are located closer to the outer surface, while the less successful solutions remain "softer" and are located inside. The algorithm uses clustering of solutions by quality and distance, allowing to preserve less successful options and providing flexibility and adaptability.

Price Action Analysis Toolkit Development (Part 8): Metrics Board
As one of the most powerful Price Action analysis toolkits, the Metrics Board is designed to streamline market analysis by instantly providing essential market metrics with just a click of a button. Each button serves a specific function, whether it’s analyzing high/low trends, volume, or other key indicators. This tool delivers accurate, real-time data when you need it most. Let’s dive deeper into its features in this article.


Machine Learning Under Constraint (Part 2): Calibrating Position Size to the Remaining Drawdown Budget
We present a rule-set-aware calibration chain that turns the remaining risk budget into a calibrated sigmoid scale for position sizing. It computes a ceiling from stop loss pct and safety factor, back-solves w at a reference divergence, and flattens size progressively as the budget shrinks. The paper also clarifies where leverage caps must be applied in production: at the lots conversion, since risk-based sizing alone does not enforce max leverage.

MQL5 Wizard Techniques you should know (Part 26): Moving Averages and the Hurst Exponent
The Hurst Exponent is a measure of how much a time series auto-correlates over the long term. It is understood to be capturing the long-term properties of a time series and therefore carries some weight in time series analysis even outside of economic/ financial time series. We however, focus on its potential benefit to traders by examining how this metric could be paired with moving averages to build a potentially robust signal.

Functions for activating neurons during training: The key to fast convergence?
This article presents a study of the interaction of different activation functions with optimization algorithms in the context of neural network training. Particular attention is paid to the comparison of the classical ADAM and its population version when working with a wide range of activation functions, including the oscillating ACON and Snake functions. Using a minimalistic MLP (1-1-1) architecture and a single training example, the influence of activation functions on the optimization is isolated from other factors. The article proposes an approach to manage network weights through the boundaries of activation functions and a weight reflection mechanism, which allows avoiding problems with saturation and stagnation in training.


Building an EquiVolume Indicator in MQL5
We implement an EquiVolume indicator in MQL5 that converts standard candlesticks into volume-weighted boxes. The workflow includes selecting volume type, detecting the maximum volume within a lookback range, normalizing all values against it, and mapping them into proportional box widths. The result is a chart-based structure that visualizes trading activity intensity alongside price movement in MetaTrader 5.


Sigma Score Indicator for MetaTrader 5: A Simple Statistical Anomaly Detector
Build a practical MetaTrader 5 “Sigma Score” indicator from scratch and learn what it really measures: The z-score of log returns (how many standard deviations the latest move is from the recent average). The article walks through every code block in OnInit(), OnCalculate(), and OnDeinit(), then shows how to interpret thresholds (e.g., ±2) and apply the Sigma Score as a simple “market stress meter” for mean-reversion and momentum trading.


Self Optimizing Expert Advisors in MQL5 (Part 16): Supervised Linear System Identification
Linear system identifcation may be coupled to learn to correct the error in a supervised learning algorithm. This allows us to build applications that depend on statistical modelling techniques without necessarily inheriting the fragility of the model's restrictive assumptions. Classical supervised learning algorithms have many needs that may be supplemented by pairing these models with a feedback controller that can correct the model to keep up with current market conditions.


Neural Networks in Trading: Unified Trajectory Generation Model (UniTraj)
Understanding agent behavior is important in many different areas, but most methods focus on just one of the tasks (understanding, noise removal, or prediction), which reduces their effectiveness in real-world scenarios. In this article, we will get acquainted with a model that can adapt to solving various problems.

Interview with Igor Korepin (ATC 2011)
Appearance of the Expert Advisor cs2011 by Igor Korepin (Xupypr) at the very top of the Automated Trading Championship 2011 was really impressive - its balance was almost twice that of the EA featured on the second place. However, despite such a sound breakaway, the Expert Advisor could not stay long on the first line. Igor frankly said that he relied much on a lucky start of his trading robot in the competition. We'll see if luck helps this simple EA to take the lead in the ATC 2011 race again.

Developing a multi-currency Expert Advisor (Part 6): Automating the selection of an instance group
After optimizing the trading strategy, we receive sets of parameters. We can use them to create several instances of trading strategies combined in one EA. Previously, we did this manually. Here we will try to automate this process.


Neural Networks in Trading: Lightweight Models for Time Series Forecasting
Lightweight time series forecasting models achieve high performance using a minimum number of parameters. This, in turn, reduces the consumption of computing resources and speeds up decision-making. Despite being lightweight, such models achieve forecast quality comparable to more complex ones.

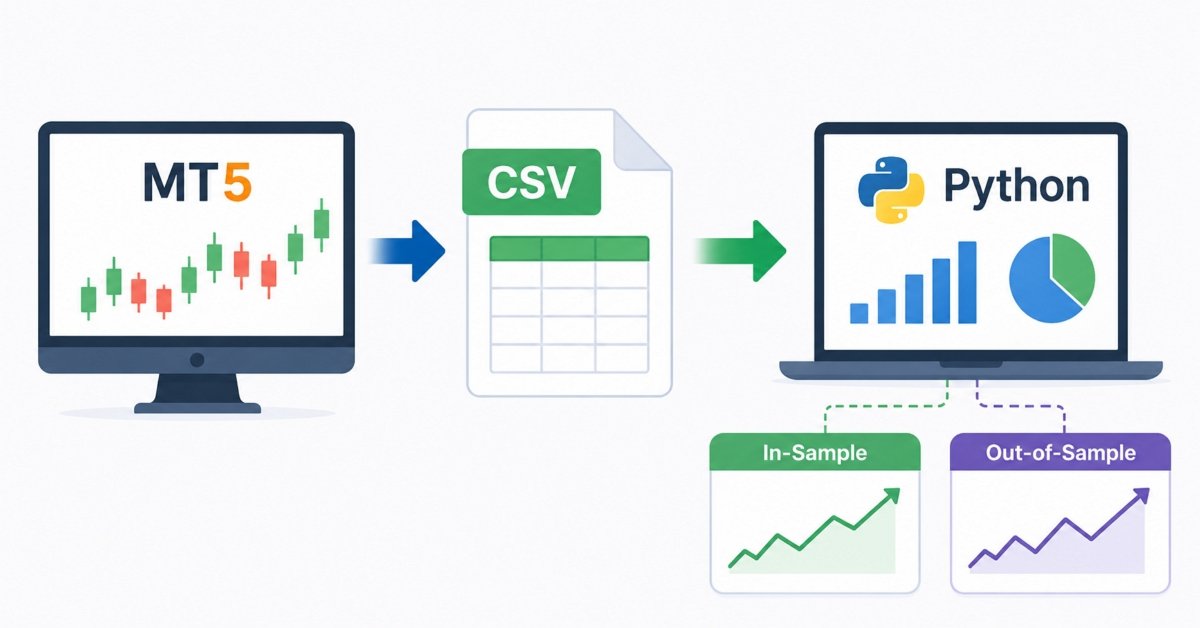
CSV Data Analysis (Part 4): Building an Automated Python-Driven Comparative Analysis Module for MQL5 Strategy Validation
The article presents a reproducible MetaTrader 5 to Python pipeline for large-scale indicator research. An MQL5 export schema captures fixed columns, including custom lag and whipsaw counters. A baseline module performs parameter-matched comparisons across symbols and timeframes, while a walk-forward module locks the InSample optimum and evaluates it on unseen data. Readers gain unbiased robustness measurements and automation that removes manual selection bias.


Building A Candlestick Trend Constraint Model (Part 4): Customizing Display Style For Each Trend Wave
In this article, we will explore the capabilities of the powerful MQL5 language in drawing various indicator styles on Meta Trader 5. We will also look at scripts and how they can be used in our model.

Reimagining Classic Strategies (Part V): Multiple Symbol Analysis on USDZAR
In this series of articles, we revisit classical strategies to see if we can improve the strategy using AI. In today's article, we will examine a popular strategy of multiple symbol analysis using a basket of correlated securities, we will focus on the exotic USDZAR currency pair.


Category Theory in MQL5 (Part 18): Naturality Square
This article continues our series into category theory by introducing natural transformations, a key pillar within the subject. We look at the seemingly complex definition, then delve into examples and applications with this series’ ‘bread and butter’; volatility forecasting.

Archery Algorithm (AA)
The article takes a detailed look at the archery-inspired optimization algorithm, with an emphasis on using the roulette method as a mechanism for selecting promising areas for "arrows". The method allows evaluating the quality of solutions and selecting the most promising positions for further study.


Design Patterns in software development and MQL5 (Part 2): Structural Patterns
In this article, we will continue our articles about Design Patterns after learning how much this topic is more important for us as developers to develop extendable, reliable applications not only by the MQL5 programming language but others as well. We will learn about another type of Design Patterns which is the structural one to learn how to design systems by using what we have as classes to form larger structures.

Interview with Berron Parker (ATC 2010)
During the first week of the Championship Berron's Expert Advisor has been on the top position. He now tells us about his experience of EA development and difficulties of moving to MQL5. Berron says his EA is set up to work in a trend market, but can be weak in other market conditions. However, he is hopeful that his robot will show good results in this competition.