Articles on data analysis and statistics in MQL5

Articles on mathematical models and laws of probability are interesting for many traders. Mathematics is the basis of technical indicators, and statistics is required to analyze trading results and develop strategies.
Read about the fuzzy logic, digital filters, market profile, Kohonen maps, neural gas and many other tools that can be used for trading.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Developing a Neural Network Trading Robot Based on Mamba with Selective State Space Models
The article explores the revolutionary Mamba/SSM neural network architecture for financial time series forecasting. We will consider a complete MQL5 implementation of a modern alternative to Transformer with linear complexity O(N) instead of quadratic O(N²). Selective State Space Models, hardware-aware optimizations, patching techniques, and advanced AdamW training methods are covered in detail. Practical test results showing an increase in accuracy from 62% to 71% while reducing training time from 45 to 8 minutes are included. A ready-made trading EA with auto learning and adaptive risk management for MetaTrader 5 is presented.


Backtracking Search Algorithm (BSA)
What if an optimization algorithm could remember its past journeys and use that memory to find better solutions? BSA does just that – balancing exploration with revisiting the tried and true. In this article, we reveal the secrets of the algorithm. A simple idea, minimum parameters and a stable result.


Covariance Matrix Adaptation Evolution Strategy (CMA-ES)
The article explores one of the most interesting non-gradient optimization algorithms, which learns to understand the geometry of the objective function. We will focus on the classical implementation of CMA-ES with a slight modification - replacing the normal distribution with the power one. We will thoroughly examine the math behind the algorithm, as well as practical implementation, and check where CMA-ES is unbeatable and where it should be avoided.


Non-stationary processes and spurious regression
The article demonstrates spurious regression occurring when attempting to apply regression analysis to non-stationary processes using Monte Carlo simulation.


Quantum Computing and Gradient Boosting in EURUSD Trading
The article describes the practical implementation of a hybrid algorithmic trading system that combines quantum computing (IBM Qiskit) and gradient boosting (CatBoost) to predict movements in the EURUSD pair on the hourly time frame. The system extracts four unique quantum features from a probability distribution across 256 states using eight qubits and, in combination with classical indicators and delta encoding of time categories, achieves 62% accuracy on 15,000 candlesticks.


The Avellaneda-Stoikov Model: Inventory-Aware Quoting for Two-Sided Strategies
This article builds the Avellaneda–Stoikov formulas in MQL5, feeds them with rolling estimates of mid-price volatility and a proxy for order-flow intensity, and plots the reservation price with bid and ask in real time. A bar-by-bar simulation contrasts adaptive and fixed quoting under the same fill rules. The result is a tested class, an indicator, and a backtest to improve inventory control in two‑sided strategies.


Feature Engineering for ML (Part 11): Fractal Features in Python
The article examines a Williams five‑bar fractal feature pipeline and shows how a centered rolling window creates a true look‑ahead leak. It identifies two additional silent bugs—a hardcoded shift tied to the default n and a volatility threshold that ignores its input—and consolidates fixes under a single leak_safe flag. Readers get leak‑free fractal, level, trend, and signal features, plus guidance on when unshifted columns remain valid for labeling.


Market Positioning Codex for VGT with Kendall's Tau and Distance Correlation
In this article, we look to explore how a complimentary indicator pairing can be used to analyze the recent 5-year history of Vanguard Information Technology Index Fund ETF. By considering two options of algorithms, Kendall’s Tau and Distance-Correlation, we look to select not just an ideal indicator pair for trading the VGT, but also suitable signal-pattern pairings of these two indicators.


Population optimization algorithms: Micro Artificial immune system (Micro-AIS)
The article considers an optimization method based on the principles of the body's immune system - Micro Artificial Immune System (Micro-AIS) - a modification of AIS. Micro-AIS uses a simpler model of the immune system and simple immune information processing operations. The article also discusses the advantages and disadvantages of Micro-AIS compared to conventional AIS.

MQL5 Wizard Techniques you should know (Part 18): Neural Architecture Search with Eigen Vectors
Neural Architecture Search, an automated approach at determining the ideal neural network settings can be a plus when facing many options and large test data sets. We examine how when paired Eigen Vectors this process can be made even more efficient.


Development and Forward Testing of an Autonomous LLM Agent for Trading with SEAL
A hybrid architecture based on Llama 3.2 and SEAL is being tested on eight currency pairs (M15), with forward-period data isolation and information leakage control. The methodology combines adversarial self-play, curriculum learning, and class balancing to ensure stable training. The experiments confirm the gap between forecast accuracy and actual returns, providing readers with practical guidelines for testing strategies and accurately assessing their generalizability.


Developing a Replay System (Part 64): Playing the service (V)
In this article, we will look at how to fix two errors in the code. However, I will try to explain them in a way that will help you, beginner programmers, understand that things don't always go as you expect. Anyway, this is an opportunity to learn. The content presented here is intended solely for educational purposes. In no way should this application be considered as a final document with any purpose other than to explore the concepts presented.


Seasonality Indicator by Hours, Days of the Week, and Days of the Month
The article explains how to develop a tool for analyzing recurring price patterns in financial markets — by day of the month (1-31), day of the week (Monday-Sunday), or hour of the day (0-23). The indicator analyzes historical data, calculates the average return for each period, and displays the results as a histogram with a forecast. It includes customizable parameters: seasonality type, number of bars analyzed, display as percentages or absolute values, chart colors.


MQL5 Wizard Techniques you should know (Part 88): Using Blooms Filter with a Custom Trailing Class
Our next focus in these series on ideas that can be rapidly prototyped with the MQL5 Wizard, is a Custom Trailing class that uses the Blooming Filter. Trailing Stop systems are an optional but very resourceful part to any trading system that we want to explore more in these series besides the traditional Entry Signals.


Developing a Replay System (Part 30): Expert Advisor project — C_Mouse class (IV)
Today we will learn a technique that can help us a lot in different stages of our professional life as a programmer. Often it is not the platform itself that is limited, but the knowledge of the person who talks about the limitations. This article will tell you that with common sense and creativity you can make the MetaTrader 5 platform much more interesting and versatile without resorting to creating crazy programs or anything like that, and create simple yet safe and reliable code. We will use our creativity to modify existing code without deleting or adding a single line to the source code.


MQL5 Trading Tools (Part 37): Adding a Per-Object Property-Editing Ribbon to the Canvas Drawing Layer
We add a descriptor-driven property stack and a floating ribbon that binds to the current selection on the drawing layer. The article covers the descriptor list for each tool, the engine get/set API with snapshot-and-restore live preview, and widget renderers for color, opacity, line width, line style, fonts, and level visibility. You get in-place, real-time editing of object appearance via a compact, draggable panel.


Introduction to MQL5 (Part 39): Beginner Guide to File Handling in MQL5 (I)
This article introduces file handling in MQL5 using a practical, project-based workflow. You will use FileSelectDialog to choose or create a CSV file, open it with FileOpen, and write structured account headers such as account name, balance, login, date range, and last update. The result is a clear foundation for a reusable trading journal and safe file operations in MetaTrader 5.


MQL5 Custom Symbols: Creating a 3D Bars Symbol
The article provides a detailed guide to creating the innovative 3DBarCustomSymbol.mq5 indicator, which generates custom symbols in MetaTrader 5 that combine price, time, volume, and volatility into a single three-dimensional representation. The mathematical foundations, system architecture, practical aspects of implementation and application in trading strategies are considered.


Creating an HTML Dashboard for Strategy Tester and Prop Firm Challenge Analysis in MQL5
This article demonstrates how to build a reusable prop‑firm evaluation module for MQL5 Expert Advisors and export results to an HTML dashboard. The module monitors balance and equity during backtests, simulates single or rolling challenges, checks profit target, daily and overall drawdown, and minimum trading days, then outputs both a terminal summary and a browser‑readable report.


Community of Scientists Optimization (CoSO): Theory
Secrets of effective optimization of trading strategies in metaheuristic approaches. Community of Scientists Optimization is a new population-based algorithm inspired by the mechanisms of the scientific community. Unlike traditional nature-inspired metaphors, CoSO models unique aspects of human scientific activity: publishing results in journals, competing for grants, and forming research teams.


From Novice to Expert: Animated News Headline Using MQL5 (V)—Event Reminder System
In this discussion, we’ll explore additional advancements as we integrate refined event‑alerting logic for the economic calendar events displayed by the News Headline EA. This enhancement is critical—it ensures users receive timely notifications a short time before key upcoming events. Join this discussion to discover more.


Forecasting a Conditional Distribution Using MLP
In this article, we will consider an MLP-based regression model that predicts not only the conditional expectation but also the conditional variance. In other words, we will train our network to predict the entire distribution of future prices based on the input feature vector. But for this purpose we will have to implement our own loss function.


MQL5 Trading Tools (Part 38): Adding a Tabbed Settings Window for Editing Object Properties
We add a tabbed settings window opened from the ribbon and bound to the selected object. The tabs — Style, Text, Coordinates, and Visibility — are built from the same descriptor system, with scrolling, per-level rows, and shared color/width/style popovers. The article covers layout, rendering, interaction, and inline price/time and numeric editing. You get one place to edit every property with live preview and commit-or-discard on close.


Execution Cost and Slippage Sensitivity Analyzer
Backtests often understate spread, commission, and slippage. This MQL5 analyzer loads closing deals and simulates rising execution costs to measure robustness. It computes the breakeven cost per deal, the cushion over an assumed cost, the net profit and profit factor at that cost, and how many winners turn into losers, then summarizes the result with an A+ to F grade and targeted guidance.


Market Simulation: Position View (V)
Despite what was shown in the previous article, all of this may seem simple at first. In reality, several problems remain, along with many tasks that still need to be completed. You, dear reader, may imagine that everything is easy and straightforward. Out of inexperience, you may simply accept whatever is presented to you. And that is a mistake you should try to avoid. Even worse is trying to use something without truly understanding what exactly you are using. Beginners often pass through a copy-and-paste stage. If you do not want to remain stuck at that stage forever, you should learn how to use certain tools. One of the tools most often used by programmers is documentation. The second is testing, supported by log files. Here we will see how to do this.


Atmosphere Clouds Model Optimization (ACMO): Theory
The article is devoted to the metaheuristic Atmosphere Clouds Model Optimization (ACMO) algorithm, which simulates the behavior of clouds to solve optimization problems. The algorithm uses the principles of cloud generation, movement and propagation, adapting to the "weather conditions" in the solution space. The article reveals how the algorithm's meteorological simulation finds optimal solutions in a complex possibility space and describes in detail the stages of ACMO operation, including "sky" preparation, cloud birth, cloud movement, and rain concentration.


Building Volatility Models in MQL5 (Part III): Implementing the SLSQP Algorithm for Model Estimation
An SLSQP optimizer is implemented in MQL5 to resolve parameter discrepancies between a volatility library and Python's ARCH module. The article details constraint handling, gradient options, configuration, and convergence controls and shows how to integrate the solver into existing code. Practical examples and comparisons demonstrate matched log‑likelihoods and parameters on shared datasets.


Introduction to MQL5 (Part 41): Beginner Guide to File Handling in MQL5 (III)
Learn how to read a CSV file in MQL5 and organize its trading data into dynamic arrays. This article shows step by step how to count file elements, store all data in a single array, and separate each column into dedicated arrays, laying the foundation for advanced analysis and trading performance visualization.


Bivariate Copulae in MQL5 (Part 3): Implementation and Tuning of Mixed Copula Models in MQL5
The article extends our copula toolkit with mixed copulas implemented natively in MQL5. We construct Clayton–Frank–Gumbel and Clayton–Student–t–Gumbel mixtures, estimate them via EM, and enable sparsity control through SCAD with cross‑validation. Provided scripts tune hyperparameters, compare mixtures using information criteria, and save trained models. Practitioners can apply these components to capture asymmetric tail dependence and embed the selected model in indicators or Expert Advisors.


Building a Future Swing Projection Indicator in MQL5
We implement a Future Swing Projection indicator in MQL5 that analyzes historical swing structure and estimates the next move from recent price behavior. It locates six alternating swing points, measures five completed legs, and uses their average distance to project a target five bars ahead. The indicator draws swing legs, a projection line, ATR‑based support and resistance zones, and a label with the projected price to keep the process rule‑based and reproducible.


MQL5 Trading Tools (Part 25): Expanding to Multiple Distributions with Interactive Switching
In this article, we expand the MQL5 graphing tool to support seventeen statistical distributions with interactive cycling via a header switch icon. We add type-specific data loading, discrete and continuous histogram computation, and theoretical density functions for each model, with dynamic titles, axis labels, and parameter panels that adapt automatically. The result lets you overlay distribution models on the same sample and compare fit across families without reloading the tool.


Symbolic Price Forecasting Equation Using SymPy
The article describes an interesting approach to algorithmic trading based on symbolic mathematical equations instead of traditional machine learning "black boxes". The author demonstrates how to transform opaque neural networks into readable mathematical equations using the SymPy library and polynomial regression, allowing for a full understanding of the logic behind trading decisions. The approach combines the computational power of ML with the transparency of classical methods, giving traders the ability to analyze, adjust, and adapt models in real time.


MQL5 Trading Tools (Part 27): Rendering Parametric Butterfly Curve on Canvas
In this article, we explore the butterfly curve, a parametric mathematical equation, and render it visually on a MQL5 canvas. We build an interactive display with a draggable, resizable canvas window, supersampled curve rendering, gradient backgrounds, and a color-segmented legend. By the end, we have a fully functional visual tool that plots the butterfly curve directly on the MetaTrader 5 chart.


Developing a Multi-Currency Expert Advisor (Part 28): Adding a Position Closing Manager
When running multiple strategies in parallel, you may want to periodically close all open positions and start the strategies over again. The existing code only allows this behavior to be implemented through manual intervention. Let's try to automate this part.


Developing a Replay System (Part 57): Understanding a Test Service
One point to note: although the service code is not included in this article and will only be provided in the next one, I'll explain it since we'll be using that same code as a springboard for what we're actually developing. So, be attentive and patient. Wait for the next article, because every day everything becomes more interesting.


MQL5 Trading Tools (Part 28): Filling Sweep Polygons for Butterfly Curve in MQL5
We expand the capabilities of the MetaTrader 5 butterfly curve canvas by adding multi-layered wing fills, vein lines, scale dots, and a full body (abdomen, thorax, head, eyes, antennae). This article implements polygon fills with vertical and radial gradients, as well as filled circles and ellipses, all using supersampling antialiasing. You will also receive reusable MQL5 helper functions and a rendering order that transforms a simple curve into a customizable, detailed chart illustration.


Quantum Neural Network in MQL5 (Part II): Training a Neural Network with Backpropagation on ALGLIB Markov Matrices
The article presents an innovative quantum neural network architecture for algorithmic trading that combines the principles of quantum mechanics with modern machine learning methods. The system includes quantum effects (resonance, interference, decoherence), multi-level memory of different time scales, Markov chains with the ALGLIB library, and adaptive parameter control. The full implementation is done in MQL5 using the built-in matrix/vector types, which removes implementation barriers in MetaTrader 5.


Real-Time Polynomial Regression: A Causal Savitzky-Golay Implementation for MQL5
We adapt the Savitzky–Golay filter to a strictly causal, real-time form for MQL5 and derive the fixed coefficients for end-point evaluation. The article provides a full indicator and an Expert Advisor, explains the edge-evaluation noise sensitivity, and implements a multi-bar confirmation safeguard. Backtests on several symbols are shown without cherry-picking. You get ready-to-compile code, parameter guidance, and a reduced-lag alternative to moving averages.


Market Microstructure in MQL5 (Part 2): Measuring long memory in MQL5 with Hurst estimators
Part 2 focuses on practical long-memory detection for intraday data. Three complementary Hurst estimators are implemented and combined into a confidence‑weighted composite, with confidence tied to valid regression scales. The final H and confidence populate the shared analysis struct, enabling indicators to act only when H departs from the neutral 0.40–0.60 band and to select trend‑following above 0.60 or mean‑reversion below 0.40.

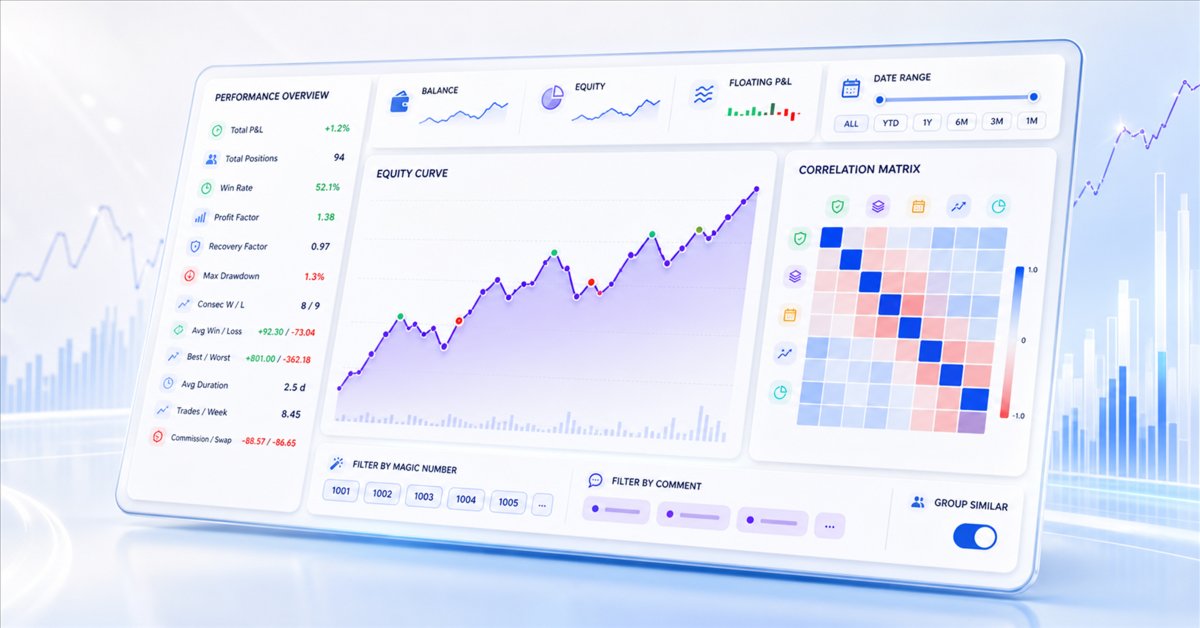
Creating an Interactive Portfolio Analyzer Dashboard with CCanvas in MQL5
This article presents a standalone Portfolio Analyzer dashboard implemented as an Expert Advisor for MetaTrader 5. It reads account deal history, reconstructs closed positions, and attributes results by magic number or normalized comment to deliver clear per-strategy metrics. The interface provides a vector equity curve, date filters, and strategy selectors, plus a Pearson correlation matrix to reveal strategy redundancy. You can attach it to a separate chart without modifying existing trading EAs.