Articles on trading system automation in MQL5

Read articles on the trading systems with a wide variety of ideas at the core. Learn how to use statistical methods and patterns on candlestick charts, how to filter signals and where to use semaphore indicators.
The MQL5 Wizard will help you create robots without programming to quickly check your trading ideas. Use the Wizard to learn about genetic algorithms.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Neural networks made easy (Part 66): Exploration problems in offline learning
Models are trained offline using data from a prepared training dataset. While providing certain advantages, its negative side is that information about the environment is greatly compressed to the size of the training dataset. Which, in turn, limits the possibilities of exploration. In this article, we will consider a method that enables the filling of a training dataset with the most diverse data possible.


Risk Management (Part 5): Integrating the Risk Management System into an Expert Advisor
In this article, we will implement the risk management system developed in previous publications and add the Order Blocks indicator described in other articles. In addition, we will run a backtest so we can compare results with the risk management system enabled and evaluate the impact of dynamic risk.


Price Action Analysis Toolkit Development (Part 57): Developing a Market State Classification Module in MQL5
This article develops a market state classification module for MQL5 that interprets price behavior using completed price data. By examining volatility contraction, expansion, and structural consistency, the tool classifies market conditions as compression, transition, expansion, or trend, providing a clear contextual framework for price action analysis.


Developing a trading Expert Advisor from scratch (Part 25): Providing system robustness (II)
In this article, we will make the final step towards the EA's performance. So, be prepared for a long read. To make our Expert Advisor reliable, we will first remove everything from the code that is not part of the trading system.


Data Science and Machine Learning(Part 14): Finding Your Way in the Markets with Kohonen Maps
Are you looking for a cutting-edge approach to trading that can help you navigate complex and ever-changing markets? Look no further than Kohonen maps, an innovative form of artificial neural networks that can help you uncover hidden patterns and trends in market data. In this article, we'll explore how Kohonen maps work, and how they can be used to develop smarter, more effective trading strategies. Whether you're a seasoned trader or just starting out, you won't want to miss this exciting new approach to trading.

Reimagining Classic Strategies in Python: MA Crossovers
In this article, we revisit the classic moving average crossover strategy to assess its current effectiveness. Given the amount of time since its inception, we explore the potential enhancements that AI can bring to this traditional trading strategy. By incorporating AI techniques, we aim to leverage advanced predictive capabilities to potentially optimize trade entry and exit points, adapt to varying market conditions, and enhance overall performance compared to conventional approaches.


Python-MetaTrader 5 Strategy Tester (Part 04): Tester 101
In this fascinating article, we build our very first trading robot in the simulator and run a strategy testing action that resembles how the MetaTrader 5 strategy tester works, then compare the outcome produced in a custom simulation against our favorite terminal.


Developing a multi-currency Expert Advisor (Part 5): Variable position sizes
In the previous parts, the Expert Advisor (EA) under development was able to use only a fixed position size for trading. This is acceptable for testing, but is not advisable when trading on a real account. Let's make it possible to trade using variable position sizes.

Practicing the development of trading strategies
In this article, we will make an attempt to develop our own trading strategy. Any trading strategy must be based on some kind of statistical advantage. Moreover, this advantage should exist for a long time.


Developing a trading Expert Advisor from scratch (Part 23): New order system (VI)
We will make the order system more flexible. Here we will consider changes to the code that will make it more flexible, which will allow us to change position stop levels much faster.


Multiple Symbol Analysis With Python And MQL5 (Part 3): Triangular Exchange Rates
Traders often face drawdowns from false signals, while waiting for confirmation can lead to missed opportunities. This article introduces a triangular trading strategy using Silver’s pricing in Dollars (XAGUSD) and Euros (XAGEUR), along with the EURUSD exchange rate, to filter out noise. By leveraging cross-market relationships, traders can uncover hidden sentiment and refine their entries in real time.


How to Detect Round-Number Liquidity in MQL5
The article presents an MQL5 method for detecting psychological round numbers by converting prices to strings and counting trailing zeros (ZeroSize). It outlines the theory of institutional liquidity at integers, explains the GetZeroCount logic with tick-size normalization to avoid floating‑point errors, and details hierarchical visualization. Case studies across forex, metals, and crypto, plus timeframe filters and inputs, show how to use confluence and basic risk controls in practice.


MetaTrader 5 Machine Learning Blueprint (Part 10): Bet Sizing for Financial Machine Learning
Fixed fractions and raw probabilities misallocate risk under overlapping labels and induce overtrading. This article delivers four AFML-compliant sizers: probability-based (z-score → CDF, active-bet averaging, discretization), forecast-price (sigmoid/power with w calibration and limit price), budget-constrained (direction-only), and reserve (mixture-CDF via EF3M). You get a signed, bounded position series with documented conditions of use.

Neural Networks in Trading: Scene-Aware Object Detection (HyperDet3D)
We invite you to get acquainted with a new approach to detecting objects using hypernetworks. A hypernetwork generates weights for the main model, which allows taking into account the specifics of the current market situation. This approach allows us to improve forecasting accuracy by adapting the model to different trading conditions.

Neural networks made easy (Part 35): Intrinsic Curiosity Module
We continue to study reinforcement learning algorithms. All the algorithms we have considered so far required the creation of a reward policy to enable the agent to evaluate each of its actions at each transition from one system state to another. However, this approach is rather artificial. In practice, there is some time lag between an action and a reward. In this article, we will get acquainted with a model training algorithm which can work with various time delays from the action to the reward.

Algorithmic Trading Strategies: AI and Its Road to Golden Pinnacles
This article demonstrates an approach to creating trading strategies for gold using machine learning. Considering the proposed approach to the analysis and forecasting of time series from different angles, it is possible to determine its advantages and disadvantages in comparison with other ways of creating trading systems which are based solely on the analysis and forecasting of financial time series.


Automating Market Memory Zones Indicator: Where Price is Likely to Return
This article turns Market Memory Zones from a chart-only concept into a complete MQL5 Expert Advisor. It automates Displacement, Structure Transition (CHoCH), and Liquidity Sweep zones using ATR- and candle-structure filters, applies lower-timeframe confirmation, and enforces risk-based position sizing with dynamic SL and structure-based TP. You will get the code architecture for detection, entries, trade management, and visualization, plus a brief backtest review.

Reimagining Classic Strategies (Part II): Bollinger Bands Breakouts
This article explores a trading strategy that integrates Linear Discriminant Analysis (LDA) with Bollinger Bands, leveraging categorical zone predictions for strategic market entry signals.


MQL5 Wizard Techniques you should know (Part 84): Using Patterns of Stochastic Oscillator and the FrAMA - Conclusion
The Stochastic Oscillator and the Fractal Adaptive Moving Average are an indicator pairing that could be used for their ability to compliment each other within an MQL5 Expert Advisor. We introduced this pairing in the last article, and now look to wrap up by considering its 5 last signal patterns. In exploring this, as always, we use the MQL5 wizard to build and test out their potential.


Building a Candlestick Trend Constraint Model (Part 10): Strategic Golden and Death Cross (EA)
Did you know that the Golden Cross and Death Cross strategies, based on moving average crossovers, are some of the most reliable indicators for identifying long-term market trends? A Golden Cross signals a bullish trend when a shorter moving average crosses above a longer one, while a Death Cross indicates a bearish trend when the shorter average moves below. Despite their simplicity and effectiveness, manually applying these strategies often leads to missed opportunities or delayed trades.


Data Science and Machine Learning (Part 17): Money in the Trees? The Art and Science of Random Forests in Forex Trading
Discover the secrets of algorithmic alchemy as we guide you through the blend of artistry and precision in decoding financial landscapes. Unearth how Random Forests transform data into predictive prowess, offering a unique perspective on navigating the complex terrain of stock markets. Join us on this journey into the heart of financial wizardry, where we demystify the role of Random Forests in shaping market destiny and unlocking the doors to lucrative opportunities


Price Action Analysis Toolkit Development (Part 40): Market DNA Passport
This article explores the unique identity of each currency pair through the lens of its historical price action. Inspired by the concept of genetic DNA, which encodes the distinct blueprint of every living being, we apply a similar framework to the markets, treating price action as the “DNA” of each pair. By breaking down structural behaviors such as volatility, swings, retracements, spikes, and session characteristics, the tool reveals the underlying profile that distinguishes one pair from another. This approach provides more profound insight into market behavior and equips traders with a structured way to align strategies with the natural tendencies of each instrument.

Brute force approach to patterns search (Part V): Fresh angle
In this article, I will show a completely different approach to algorithmic trading I ended up with after quite a long time. Of course, all this has to do with my brute force program, which has undergone a number of changes that allow it to solve several problems simultaneously. Nevertheless, the article has turned out to be more general and as simple as possible, which is why it is also suitable for those who know nothing about brute force.

Neural Networks in Trading: Hierarchical Vector Transformer (HiVT)
We invite you to get acquainted with the Hierarchical Vector Transformer (HiVT) method, which was developed for fast and accurate forecasting of multimodal time series.


Quick Integration of a Large Language Model into MetaTrader 5 (Part I): Building the Model
The article explores the revolutionary integration of large language models (LLMs) with the MetaTrader 5 trading platform, where AI does not simply predict prices but makes autonomous trading decisions by analyzing market context much like an experienced trader. The author highlights a fundamental difference between LLMs and classical machine learning models such as CatBoost — the ability to engage in metacognition and self-reflection, which allows the system to learn from its own mistakes and improve its strategy.


Risk Management (Part 3): Building the Main Class for Risk Management
In this article, we will begin creating a core risk management class that will be key to controlling risks in the system. We will focus on building the foundations, defining the basic structures, variables and functions. In addition, we will implement the necessary methods for setting maximum profit and loss values, thereby laying the foundation for risk management.


Data Science and Machine Learning (Part 19): Supercharge Your AI models with AdaBoost
AdaBoost, a powerful boosting algorithm designed to elevate the performance of your AI models. AdaBoost, short for Adaptive Boosting, is a sophisticated ensemble learning technique that seamlessly integrates weak learners, enhancing their collective predictive strength.

Neural Networks Made Easy (Part 94): Optimizing the Input Sequence
When working with time series, we always use the source data in their historical sequence. But is this the best option? There is an opinion that changing the sequence of the input data will improve the efficiency of the trained models. In this article I invite you to get acquainted with one of the methods for optimizing the input sequence.


Using Deep Reinforcement Learning to Enhance Ilan Expert Advisor
We revisit the Ilan grid Expert Advisor and integrate Q-learning in MQL5 to build an adaptive version for MetaTrader 5. The article shows how to define state features, discretize them for a Q-table, select actions with ε-greedy, and shape rewards for averaging and exits. You will implement saving/loading the Q-table, tune learning parameters, and test on EURUSD/AUDUSD in the Strategy Tester to evaluate stability and drawdown risks.


Building A Candlestick Trend Constraint Model (Part 8): Expert Advisor Development (II)
Think about an independent Expert Advisor. Previously, we discussed an indicator-based Expert Advisor that also partnered with an independent script for drawing risk and reward geometry. Today, we will discuss the architecture of an MQL5 Expert Advisor, that integrates, all the features in one program.


Dingo Optimization Algorithm Modification (DOAm)
The custom modification of the Dingo algorithm presented in the article has raised the bar for finding the best optimization algorithm. Are even better results possible?

MQL5 Wizard Techniques you should know (Part 75): Using Awesome Oscillator and the Envelopes
The Awesome Oscillator by Bill Williams and the Envelopes Channel are a pairing that could be used complimentarily within an MQL5 Expert Advisor. We use the Awesome Oscillator for its ability to spot trends, while the envelopes channel is incorporated to define our support/resistance levels. In exploring this indicator pairing, we use the MQL5 wizard to build and test any potential these two may possess.

Building A Candlestick Trend Constraint Model (Part 7): Refining our model for EA development
In this article, we will delve into the detailed preparation of our indicator for Expert Advisor (EA) development. Our discussion will encompass further refinements to the current version of the indicator to enhance its accuracy and functionality. Additionally, we will introduce new features that mark exit points, addressing a limitation of the previous version, which only identified entry points.

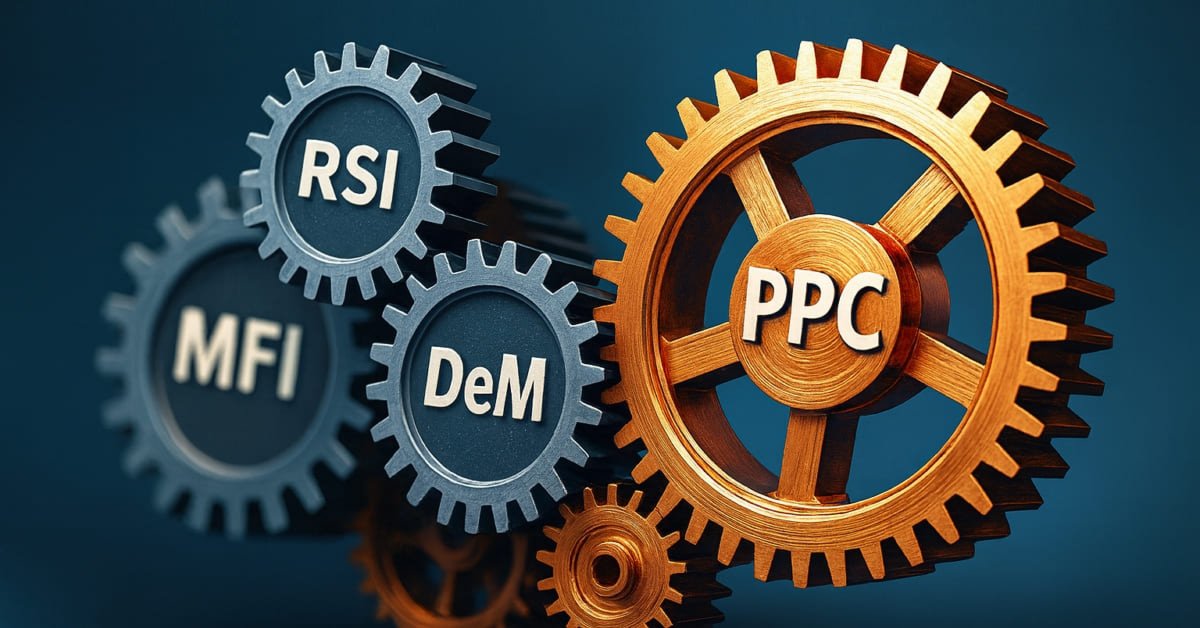
Developing Trading Strategy: Pseudo Pearson Correlation Approach
Generating new indicators from existing ones offers a powerful way to enhance trading analysis. By defining a mathematical function that integrates the outputs of existing indicators, traders can create hybrid indicators that consolidate multiple signals into a single, efficient tool. This article introduces a new indicator built from three oscillators using a modified version of the Pearson correlation function, which we call the Pseudo Pearson Correlation (PPC). The PPC indicator aims to quantify the dynamic relationship between oscillators and apply it within a practical trading strategy.


Automating Market Entropy Indicator: Trading System Based on Information Theory
This article presents an EA that automates the previously introduced Market Entropy methodology. It computes fast and slow entropy, momentum, and compression states, validates signals, and executes orders with SL/TP and optional position reversal. The result is a practical, configurable tool that applies information-theoretic signals without manual interpretation.


MetaTrader 5 Machine Learning Blueprint (Part 11): Kelly Criterion, Prop Firm Integration, and CPCV Dynamic Backtesting
The bet-sizing signal from Part 10 is concurrency-corrected but carries no payoff-ratio adjustment, no response to a hard drawdown budget, and no validation across combinatorial paths. This article covers three additions: a two-stage architecture in which a Kelly payoff multiplier is applied on top of get_signal, preserving the concurrency correction while incorporating win/loss asymmetry; a prop firm integration layer that calibrates the sigmoid w parameter continuously from the remaining drawdown budget under FundedNext Stellar 2-Step rules; and a CPCV backtest framework that simulates a fresh account state across all φ[N, k] paths, producing a Sharpe distribution and a PBO audit.


Application of Nash's Game Theory with HMM Filtering in Trading
This article delves into the application of John Nash's game theory, specifically the Nash Equilibrium, in trading. It discusses how traders can utilize Python scripts and MetaTrader 5 to identify and exploit market inefficiencies using Nash's principles. The article provides a step-by-step guide on implementing these strategies, including the use of Hidden Markov Models (HMM) and statistical analysis, to enhance trading performance.

Creation of an Automated Trading System
You must admit that it sounds alluringly - you become a fortunate possessor of a program that can develop for you a profitable automated trading system (ATC) within a few minutes. All you need is to enter desirable inputs and press Enter. And - here you are, take your ATC tested and having positive expected payoff. Where thousands of people spend thousands of hours on developing that very unique ATC, which will "wine and dine", these statements soundб to put it mildly, very hollow. On the one hand, this really looks a little larger than life... However, to my mind, this problem can be solved.


Developing a Replay System (Part 78): New Chart Trade (V)
In this article, we will look at how to implement part of the receiver code. Here we will implement an Expert Advisor to test and learn how the protocol interaction works. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


From Novice to Expert: Implementation of Fibonacci Strategies in Post-NFP Market Trading
In financial markets, the laws of retracement remain among the most undeniable forces. It is a rule of thumb that price will always retrace—whether in large moves or even within the smallest tick patterns, which often appear as a zigzag. However, the retracement pattern itself is never fixed; it remains uncertain and subject to anticipation. This uncertainty explains why traders rely on multiple Fibonacci levels, each carrying a certain probability of influence. In this discussion, we introduce a refined strategy that applies Fibonacci techniques to address the challenges of trading shortly after major economic event announcements. By combining retracement principles with event-driven market behavior, we aim to uncover more reliable entry and exit opportunities. Join to explore the full discussion and see how Fibonacci can be adapted to post-event trading.