Articles on the MQL5 programming and use of trading robots

Expert Advisors created for the MetaTrader platform perform a variety of functions implemented by their developers. Trading robots can track financial symbols 24 hours a day, copy deals, create and send reports, analyze news and even provide specific custom graphical interface.
The articles describe programming techniques, mathematical ideas for data processing, tips on creating and ordering of trading robots.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Building AI-Powered Trading Systems in MQL5 (Part 8): UI Polish with Animations, Timing Metrics, and Response Management Tools
In this article, we enhance the AI-powered trading system in MQL5 with user interface improvements, including loading animations for request preparation and thinking phases, as well as timing metrics displayed in responses for better feedback. We add response management tools like regenerate buttons to re-query the AI and export options to save the last response to a file, streamlining interaction.


Automating Classic Market Methods in MQL5 (Part 1): Wyckoff Accumulation and Distribution
The article describes an MQL5 EA that automates Wyckoff accumulation and distribution via a finite state machine. It confirms spring to SOS and upthrust to SOW before placing LPS or LPSY entries, using relative tick volume as the confirmation metric. Readers get the state model, detection criteria, code organization, and MetaTrader 5 testing procedure.

MQL5 Wizard Techniques you should know (Part 17): Multicurrency Trading
Trading across multiple currencies is not available by default when an expert advisor is assembled via the wizard. We examine 2 possible hacks traders can make when looking to test their ideas off more than one symbol at a time.


Where should your stop-loss really sit? An MAE/MFE excursion analyzer in MQL5
Stop-loss and take-profit placement is usually the least-measured decision in a trading system. This Expert Advisor reads your closed history, replays M1 price between each entry and exit to measure Maximum Adverse and Favorable Excursion per trade, and splits winners from losers. From the distributions and trade efficiency it derives data-driven stop and target levels - measured from your own account, not a rule of thumb. Analysis only; it does not trade.


Neural networks made easy (Part 48): Methods for reducing overestimation of Q-function values
In the previous article, we introduced the DDPG method, which allows training models in a continuous action space. However, like other Q-learning methods, DDPG is prone to overestimating Q-function values. This problem often results in training an agent with a suboptimal strategy. In this article, we will look at some approaches to overcome the mentioned issue.


Neural Networks in Trading: Enhancing Transformer Efficiency by Reducing Sharpness (Final Part)
SAMformer offers a solution to the key drawbacks of Transformer models in long-term time series forecasting, such as training complexity and poor generalization on small datasets. Its shallow architecture and sharpness-aware optimization help avoid suboptimal local minima. In this article, we will continue to implement approaches using MQL5 and evaluate their practical value.


Developing a multi-currency Expert Advisor (Part 3): Architecture revision
We have already made some progress in developing a multi-currency EA with several strategies working in parallel. Considering the accumulated experience, let's review the architecture of our solution and try to improve it before we go too far ahead.


Applying L1 Trend Filtering in MetaTrader 5
This article explores the practical application of L1 trend filtering in MetaTrader 5, covering both its mathematical foundations and usage in MQL5 programs. The L1 filter enables extraction of piecewise-linear trends that preserve essential market structure while reducing price noise. The study analyzes parameter scaling, trend estimation behavior, and integration of the method into algorithmic trading strategies. Experimental results demonstrate how L1 trend filtering can enhance signal stability, trade timing, and overall robustness of trading systems.


Building A Candlestick Trend Constraint Model (Part 9): Multiple Strategies Expert Advisor (II)
The number of strategies that can be integrated into an Expert Advisor is virtually limitless. However, each additional strategy increases the complexity of the algorithm. By incorporating multiple strategies, an Expert Advisor can better adapt to varying market conditions, potentially enhancing its profitability. Today, we will explore how to implement MQL5 for one of the prominent strategies developed by Richard Donchian, as we continue to enhance the functionality of our Trend Constraint Expert.


Position Management: Safe Pyramiding with a Unified Stop in MQL5
This article presents CPyramidEngine, a reusable MQL5 class that adds disciplined pyramiding to any Expert Advisor with about six lines of integration. The engine enforces three constraints: strictly decreasing lot sizes, a single unified stop that advances after each add-on, and broker-level validation of every modification. It explains common failure modes in naive implementations and shows how to keep total account risk quantifiable and controlled as positions are added.

Neural Networks in Trading: Using Language Models for Time Series Forecasting
We continue to study time series forecasting models. In this article, we get acquainted with a complex algorithm built on the use of a pre-trained language model.

MQL5 Wizard Techniques you should know (Part 77): Using Gator Oscillator and the Accumulation/Distribution Oscillator
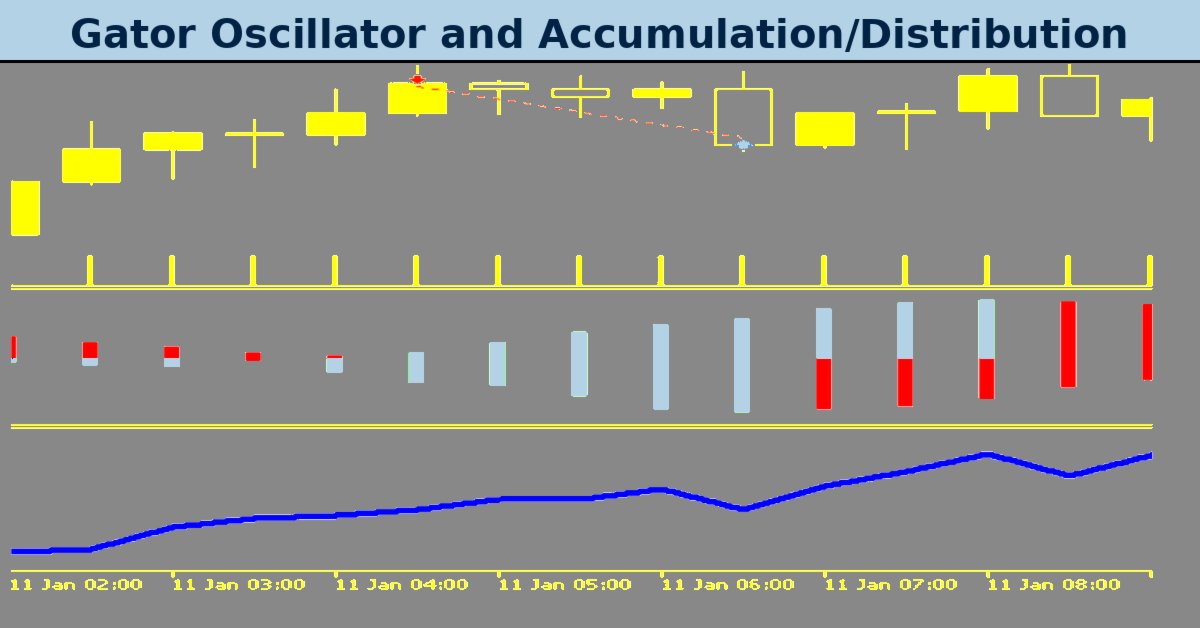
The Gator Oscillator by Bill Williams and the Accumulation/Distribution Oscillator are another indicator pairing that could be used harmoniously within an MQL5 Expert Advisor. We use the Gator Oscillator for its ability to affirm trends, while the A/D is used to provide confirmation of the trends via checks on volume. In exploring this indicator pairing, as always, we use the MQL5 wizard to build and test out their potential.


Neural Networks in Trading: Dual Clustering of Multivariate Time Series (Final Part)
We continue to implement approaches proposed vy the authors of the DUET framework, which offers an innovative approach to time series analysis, combining temporal and channel clustering to uncover hidden patterns in the analyzed data.


Neural Networks Made Easy (Part 93): Adaptive Forecasting in Frequency and Time Domains (Final Part)
In this article, we continue the implementation of the approaches of the ATFNet model, which adaptively combines the results of 2 blocks (frequency and time) within time series forecasting.


Gain An Edge Over Any Market (Part II): Forecasting Technical Indicators
Did you know that we can gain more accuracy forecasting certain technical indicators than predicting the underlying price of a traded symbol? Join us to explore how to leverage this insight for better trading strategies.

Trading with the MQL5 Economic Calendar (Part 4): Implementing Real-Time News Updates in the Dashboard
This article enhances our Economic Calendar dashboard by implementing real-time news updates to keep market information current and actionable. We integrate live data fetching techniques in MQL5 to update events on the dashboard continuously, improving the responsiveness of the interface. This update ensures that we can access the latest economic news directly from the dashboard, optimizing trading decisions based on the freshest data.

Neural Networks in Trading: Transformer with Relative Encoding
Self-supervised learning can be an effective way to analyze large amounts of unlabeled data. The efficiency is provided by the adaptation of models to the specific features of financial markets, which helps improve the effectiveness of traditional methods. This article introduces an alternative attention mechanism that takes into account the relative dependencies and relationships between inputs.

Self Optimizing Expert Advisors in MQL5 (Part 10): Matrix Factorization
Factorization is a mathematical process used to gain insights into the attributes of data. When we apply factorization to large sets of market data — organized in rows and columns — we can uncover patterns and characteristics of the market. Factorization is a powerful tool, and this article will show how you can use it within the MetaTrader 5 terminal, through the MQL5 API, to gain more profound insights into your market data.

MQL5 Wizard Techniques you should know (Part 61): Using Patterns of ADX and CCI with Supervised Learning
The ADX Oscillator and CCI oscillator are trend following and momentum indicators that can be paired when developing an Expert Advisor. We look at how this can be systemized by using all the 3 main training modes of Machine Learning. Wizard Assembled Expert Advisors allow us to evaluate the patterns presented by these two indicators, and we start by looking at how Supervised-Learning can be applied with these Patterns.


Neural Networks in Trading: Disentangling Structured Components (Encoder)
We invite you to explore the next stage in implementing the SCNN framework, which combines flexibility and interpretability, allowing structural components of a time series to be identified precisely. The article provides a detailed explanation of the mechanisms of adaptive normalization and attention, which ensure the model's resilience to changing market conditions.


From Simple Close Buttons to a Rule-Based Risk Dashboard in MQL5
Build a rule-based on-chart risk management panel in MetaTrader 5 using the MQL5 Standard Library. The guide covers a CAppDialog-based GUI, manual event routing, and an automated update loop. You will bind UI events to CTrade to execute conditional closures, show net floating P/L, and read automated targets directly from the chart.


MQL5 Trading Tools (Part 15): Canvas Blur Effects, Shadow Rendering, and Smooth Mouse Wheel Scrolling
In this article, we enhance the MQL5 canvas dashboard with advanced visual effects, including blur gradients for fog overlays, shadow rendering for headers, and antialiased drawing for smoother lines and curves. We add smooth mouse wheel scrolling to the text panel that does not interfere with the chart zoom scale, technically an upgrade.


Developing a multi-currency Expert Advisor (Part 21): Preparing for an important experiment and optimizing the code
For further progress it would be good to see if we can improve the results by periodically re-running the automatic optimization and generating a new EA. The stumbling block in many debates about the use of parameter optimization is the question of how long the obtained parameters can be used for trading in the future period while maintaining the profitability and drawdown at the specified levels. And is it even possible to do this?

Neural Networks in Trading: State Space Models
A large number of the models we have reviewed so far are based on the Transformer architecture. However, they may be inefficient when dealing with long sequences. And in this article, we will get acquainted with an alternative direction of time series forecasting based on state space models.

Neural networks made easy (Part 39): Go-Explore, a different approach to exploration
We continue studying the environment in reinforcement learning models. And in this article we will look at another algorithm – Go-Explore, which allows you to effectively explore the environment at the model training stage.


Price Action Analysis Toolkit Development (Part 59): Using Geometric Asymmetry to Identify Precision Breakouts from Fractal Consolidation
While studying a wide range of breakout setups, I noticed that failed breakouts were rarely caused by a lack of volatility, but more often by weak internal structure. That observation led to the framework presented in this article. The approach identifies patterns where the final price leg shows superior length, steepness, and speed—clear signs of momentum accumulation ahead of directional expansion. By detecting these subtle geometric imbalances within consolidation, traders can anticipate higher-probability breakouts before price exits the range. Continue reading to see how this fractal-based, geometric framework translates structural imbalance into precise breakout signals.


Data label for time series mining (Part 6):Apply and Test in EA Using ONNX
This series of articles introduces several time series labeling methods, which can create data that meets most artificial intelligence models, and targeted data labeling according to needs can make the trained artificial intelligence model more in line with the expected design, improve the accuracy of our model, and even help the model make a qualitative leap!


Integrate Your Own LLM into EA (Part 3): Training Your Own LLM with CPU
With the rapid development of artificial intelligence today, language models (LLMs) are an important part of artificial intelligence, so we should think about how to integrate powerful LLMs into our algorithmic trading. For most people, it is difficult to fine-tune these powerful models according to their needs, deploy them locally, and then apply them to algorithmic trading. This series of articles will take a step-by-step approach to achieve this goal.

Neural Networks Made Easy (Part 92): Adaptive Forecasting in Frequency and Time Domains
The authors of the FreDF method experimentally confirmed the advantage of combined forecasting in the frequency and time domains. However, the use of the weight hyperparameter is not optimal for non-stationary time series. In this article, we will get acquainted with the method of adaptive combination of forecasts in frequency and time domains.


Neural Networks Made Easy (Part 84): Reversible Normalization (RevIN)
We already know that pre-processing of the input data plays a major role in the stability of model training. To process "raw" input data online, we often use a batch normalization layer. But sometimes we need a reverse procedure. In this article, we discuss one of the possible approaches to solving this problem.

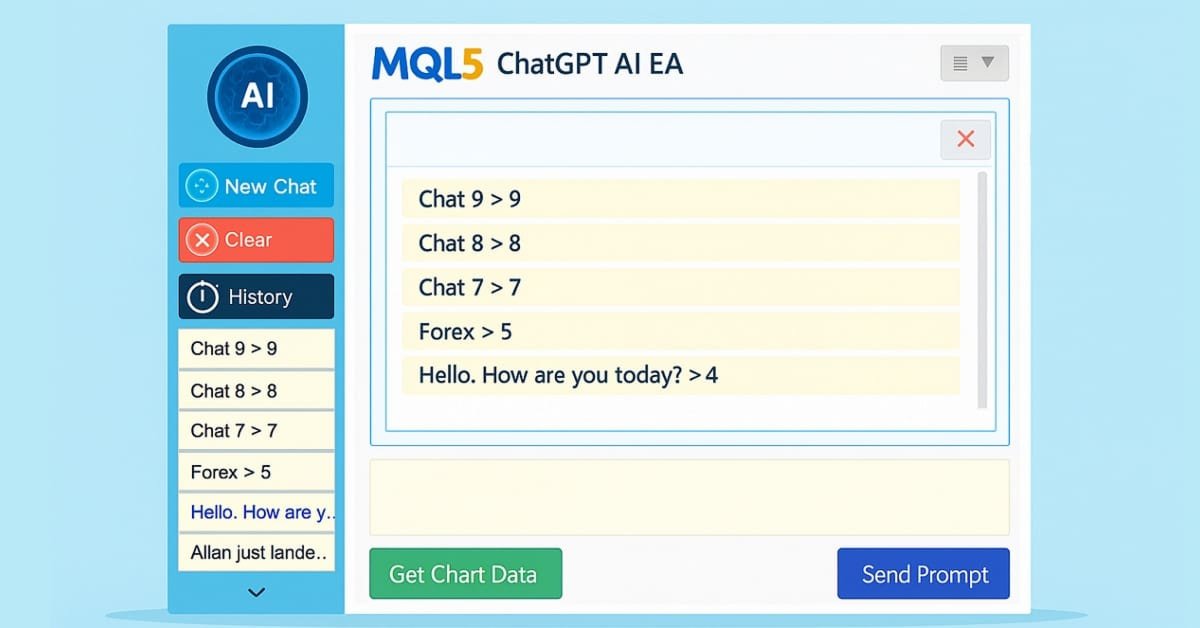
Building AI-Powered Trading Systems in MQL5 (Part 5): Adding a Collapsible Sidebar with Chat Popups
In Part 5 of our MQL5 AI trading system series, we enhance the ChatGPT-integrated Expert Advisor by introducing a collapsible sidebar, improving navigation with small and large history popups for seamless chat selection, while maintaining multiline input handling, persistent encrypted chat storage, and AI-driven trade signal generation from chart data.


Category Theory in MQL5 (Part 20): A detour to Self-Attention and the Transformer
We digress in our series by pondering at part of the algorithm to chatGPT. Are there any similarities or concepts borrowed from natural transformations? We attempt to answer these and other questions in a fun piece, with our code in a signal class format.


Building a Volume Bubble Indicator in MQL5 Using Standard Deviation
The article demonstrates how to build a Volume Bubble Indicator in MQL5 that visualizes market activity using statistical normalization. It covers how to work with tick and real volume, compute the mean and standard deviation over a rolling window, and normalize volume values to identify relative strength. You will implement chart objects to display bubbles with dynamic size and color, providing a clear representation of volume intensity directly on the chart.


Developing a trading Expert Advisor from scratch (Part 26): Towards the future (I)
Today we will take our order system to the next level. But before that, we need to solve a few problems. Now we have some questions that are related to how we want to work and what things we do during the trading day.


Neural Networks in Trading: Multi-Task Learning Based on the ResNeXt Model
A multi-task learning framework based on ResNeXt optimizes the analysis of financial data, taking into account its high dimensionality, nonlinearity, and time dependencies. The use of group convolution and specialized heads allows the model to effectively extract key features from the input data.


Neural Networks in Trading: Two-Dimensional Connection Space Models (Final Part)
We continue to explore the innovative Chimera framework – a two-dimensional state-space model that uses neural network technologies to analyze multidimensional time series. This method provides high forecasting accuracy with low computational cost.


Neural Networks in Trading: Memory Augmented Context-Aware Learning (MacroHFT) for Cryptocurrency Markets
I invite you to explore the MacroHFT framework, which applies context-aware reinforcement learning and memory to improve high-frequency cryptocurrency trading decisions using macroeconomic data and adaptive agents.

Neural Networks in Trading: Practical Results of the TEMPO Method
We continue our acquaintance with the TEMPO method. In this article we will evaluate the actual effectiveness of the proposed approaches on real historical data.


Data Science and ML (Part 38): AI Transfer Learning in Forex Markets
The AI breakthroughs dominating headlines, from ChatGPT to self-driving cars, aren’t built from isolated models but through cumulative knowledge transferred from various models or common fields. Now, this same "learn once, apply everywhere" approach can be applied to help us transform our AI models in algorithmic trading. In this article, we are going to learn how we can leverage the information gained across various instruments to help in improving predictions on others using transfer learning.

Neural networks made easy (Part 34): Fully Parameterized Quantile Function
We continue studying distributed Q-learning algorithms. In previous articles, we have considered distributed and quantile Q-learning algorithms. In the first algorithm, we trained the probabilities of given ranges of values. In the second algorithm, we trained ranges with a given probability. In both of them, we used a priori knowledge of one distribution and trained another one. In this article, we will consider an algorithm which allows the model to train for both distributions.