Articles with examples of trading robots developed in MQL5

An Expert Advisor is the 'pinnacle' of programming and the desired goal of every automated trading developer. Read the articles in this section to create your own trading robot. By following the described steps you will learn how to create, debug and test automated trading systems.
The articles not only teach MQL5 programming, but also show how to implement trading ideas and techniques. You will learn how to program a trailing stop, how to apply money management, how to get the indicator values, and much more.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Neural networks made easy (Part 38): Self-Supervised Exploration via Disagreement
One of the key problems within reinforcement learning is environmental exploration. Previously, we have already seen the research method based on Intrinsic Curiosity. Today I propose to look at another algorithm: Exploration via Disagreement.

Neural Networks in Trading: A Multi-Agent Self-Adaptive Model (Final Part)
In the previous article, we introduced the multi-agent self-adaptive framework MASA, which combines reinforcement learning approaches and self-adaptive strategies, providing a harmonious balance between profitability and risk in turbulent market conditions. We have built the functionality of individual agents within this framework. In this article, we will continue the work we started, bringing it to its logical conclusion.

Seasonality Filtering and time period for Deep Learning ONNX models with python for EA
Can we benefit from seasonality when creating models for Deep Learning with Python? Does filtering data for the ONNX models help to get better results? What time period should we use? We will cover all of this over this article.

Reimagining Classic Strategies (Part VI): Multiple Time-Frame Analysis
In this series of articles, we revisit classic strategies to see if we can improve them using AI. In today's article, we will examine the popular strategy of multiple time-frame analysis to judge if the strategy would be enhanced with AI.


ARIMA Forecasting Indicator in MQL5
In this article we are implementing ARIMA forecasting indicator in MQL5. It examines how the ARIMA model generates forecasts, its applicability to the Forex market and the stock market in general. It also explains what AR autoregression is, how autoregressive models are used for forecasting, and how the autoregression mechanism works.


Trading Options Without Options (Part 1): Basic Theory and Emulation Through Underlying Assets
The article describes a variant of options emulation through an underlying asset implemented in the MQL5 programming language. The pros and cons of the chosen approach are compared with real exchange options using the example of the FORTS futures market of the MOEX Moscow exchange and the Bybit crypto exchange.

Neural Networks in Trading: Hyperbolic Latent Diffusion Model (Final Part)
The use of anisotropic diffusion processes for encoding the initial data in a hyperbolic latent space, as proposed in the HypDIff framework, assists in preserving the topological features of the current market situation and improves the quality of its analysis. In the previous article, we started implementing the proposed approaches using MQL5. Today we will continue the work we started and will bring it to its logical conclusion.

Neural networks made easy (Part 43): Mastering skills without the reward function
The problem of reinforcement learning lies in the need to define a reward function. It can be complex or difficult to formalize. To address this problem, activity-based and environment-based approaches are being explored to learn skills without an explicit reward function.

Neural networks made easy (Part 47): Continuous action space
In this article, we expand the range of tasks of our agent. The training process will include some aspects of money and risk management, which are an integral part of any trading strategy.


Portfolio optimization in Forex: Synthesis of VaR and Markowitz theory
How does portfolio trading work on Forex? How can Markowitz portfolio theory for portfolio proportion optimization and VaR model for portfolio risk optimization be synthesized? We create a code based on portfolio theory, where, on the one hand, we will get low risk, and on the other, acceptable long-term profitability.

Trading with the MQL5 Economic Calendar (Part 7): Preparing for Strategy Testing with Resource-Based News Event Analysis
In this article, we prepare our MQL5 trading system for strategy testing by embedding economic calendar data as a resource for non-live analysis. We implement event loading and filtering for time, currency, and impact, then validate it in the Strategy Tester. This enables effective backtesting of news-driven strategies.


Neural networks made easy (Part 50): Soft Actor-Critic (model optimization)
In the previous article, we implemented the Soft Actor-Critic algorithm, but were unable to train a profitable model. Here we will optimize the previously created model to obtain the desired results.


Swing Extremes and Pullbacks (Part 4): Dynamic Pullback Depth Using Volatility Models
This article replaces binary swing validation with a volatility‑normalized pullback model. Retracement depth is measured as a ratio of the prior impulse and calibrated to a rolling ATR regime, while entries require a minimum quality score and confirmation by structure or liquidity signals. The five‑layer design integrates detection, validation, liquidity mapping, regime‑aware scoring, and execution, helping you filter weak corrections and size stops dynamically to current conditions.


Neural networks made easy (Part 48): Methods for reducing overestimation of Q-function values
In the previous article, we introduced the DDPG method, which allows training models in a continuous action space. However, like other Q-learning methods, DDPG is prone to overestimating Q-function values. This problem often results in training an agent with a suboptimal strategy. In this article, we will look at some approaches to overcome the mentioned issue.


Neural Networks in Trading: Enhancing Transformer Efficiency by Reducing Sharpness (Final Part)
SAMformer offers a solution to the key drawbacks of Transformer models in long-term time series forecasting, such as training complexity and poor generalization on small datasets. Its shallow architecture and sharpness-aware optimization help avoid suboptimal local minima. In this article, we will continue to implement approaches using MQL5 and evaluate their practical value.


Developing a multi-currency Expert Advisor (Part 14): Adaptive volume change in risk manager
The previously developed risk manager contained only basic functionality. Let's try to consider possible ways of its development, allowing us to improve trading results without interfering with the logic of trading strategies.

MQL5 Wizard Techniques you should know (Part 17): Multicurrency Trading
Trading across multiple currencies is not available by default when an expert advisor is assembled via the wizard. We examine 2 possible hacks traders can make when looking to test their ideas off more than one symbol at a time.

Estimate future performance with confidence intervals
In this article we delve into the application of boostrapping techniques as a means to estimate the future performance of an automated strategy.

Neural Networks in Trading: Using Language Models for Time Series Forecasting
We continue to study time series forecasting models. In this article, we get acquainted with a complex algorithm built on the use of a pre-trained language model.


Reusing Invalidated Orderblocks As Mitigation Blocks (SMC)
In this article, we explore how previously invalidated orderblocks can be reused as mitigation blocks within Smart Money Concepts (SMC). These zones reveal where institutional traders re-enter the market after a failed orderblock, providing high-probability areas for trade continuation in the dominant trend.


Building AI-Powered Trading Systems in MQL5 (Part 8): UI Polish with Animations, Timing Metrics, and Response Management Tools
In this article, we enhance the AI-powered trading system in MQL5 with user interface improvements, including loading animations for request preparation and thinking phases, as well as timing metrics displayed in responses for better feedback. We add response management tools like regenerate buttons to re-query the AI and export options to save the last response to a file, streamlining interaction.


Creating a Trading Administrator Panel in MQL5 (Part IX): Code Organization (IV): Trade Management Panel class
This discussion covers the updated TradeManagementPanel in our New_Admin_Panel EA. The update enhances the panel by using built-in classes to offer a user-friendly trade management interface. It includes trading buttons for opening positions and controls for managing existing trades and pending orders. A key feature is the integrated risk management that allows setting stop loss and take profit values directly in the interface. This update improves code organization for large programs and simplifies access to order management tools, which are often complex in the terminal.


Developing a multi-currency Expert Advisor (Part 3): Architecture revision
We have already made some progress in developing a multi-currency EA with several strategies working in parallel. Considering the accumulated experience, let's review the architecture of our solution and try to improve it before we go too far ahead.


Reimagining Classic Strategies (Part III): Forecasting Higher Highs And Lower Lows
In this series article, we will empirically analyze classic trading strategies to see if we can improve them using AI. In today's discussion, we tried to predict higher highs and lower lows using the Linear Discriminant Analysis model.


Neural Networks Made Easy (Part 93): Adaptive Forecasting in Frequency and Time Domains (Final Part)
In this article, we continue the implementation of the approaches of the ATFNet model, which adaptively combines the results of 2 blocks (frequency and time) within time series forecasting.


Neural Networks in Trading: Dual Clustering of Multivariate Time Series (Final Part)
We continue to implement approaches proposed vy the authors of the DUET framework, which offers an innovative approach to time series analysis, combining temporal and channel clustering to uncover hidden patterns in the analyzed data.

Neural Networks in Trading: Transformer with Relative Encoding
Self-supervised learning can be an effective way to analyze large amounts of unlabeled data. The efficiency is provided by the adaptation of models to the specific features of financial markets, which helps improve the effectiveness of traditional methods. This article introduces an alternative attention mechanism that takes into account the relative dependencies and relationships between inputs.

Trading with the MQL5 Economic Calendar (Part 4): Implementing Real-Time News Updates in the Dashboard
This article enhances our Economic Calendar dashboard by implementing real-time news updates to keep market information current and actionable. We integrate live data fetching techniques in MQL5 to update events on the dashboard continuously, improving the responsiveness of the interface. This update ensures that we can access the latest economic news directly from the dashboard, optimizing trading decisions based on the freshest data.

Self Optimizing Expert Advisors in MQL5 (Part 10): Matrix Factorization
Factorization is a mathematical process used to gain insights into the attributes of data. When we apply factorization to large sets of market data — organized in rows and columns — we can uncover patterns and characteristics of the market. Factorization is a powerful tool, and this article will show how you can use it within the MetaTrader 5 terminal, through the MQL5 API, to gain more profound insights into your market data.

From Matrices to Models: How to Build an ML Pipeline in MQL5 and Export It to ONNX
The article describes the arrangement of a coordinated ML pipeline in MetaTrader 5 with separation of roles: Python trains and exports the model to ONNX, MQL5 reproduces normalization and PCA via matrix/vector and performs inference. This approach makes the model's inputs stable and verifiable, and the MetaTrader 5 strategy tester provides metrics for analyzing the system behavior.


Algorithmic Arbitrage Trading Using Graph Theory
In this article, triangular arbitrage is presented as a problem of finding cycles in a directed graph, where the vertices are currencies and the edges are currency pairs with weight rates. Profitable cycle: product of weights >1. Our Floyd-Warshall and DFS algorithms find optimal currency exchange paths that return to the starting point with a profit.


MQL5 Trading Tools (Part 15): Canvas Blur Effects, Shadow Rendering, and Smooth Mouse Wheel Scrolling
In this article, we enhance the MQL5 canvas dashboard with advanced visual effects, including blur gradients for fog overlays, shadow rendering for headers, and antialiased drawing for smoother lines and curves. We add smooth mouse wheel scrolling to the text panel that does not interfere with the chart zoom scale, technically an upgrade.

Neural networks made easy (Part 39): Go-Explore, a different approach to exploration
We continue studying the environment in reinforcement learning models. And in this article we will look at another algorithm – Go-Explore, which allows you to effectively explore the environment at the model training stage.


Applying L1 Trend Filtering in MetaTrader 5
This article explores the practical application of L1 trend filtering in MetaTrader 5, covering both its mathematical foundations and usage in MQL5 programs. The L1 filter enables extraction of piecewise-linear trends that preserve essential market structure while reducing price noise. The study analyzes parameter scaling, trend estimation behavior, and integration of the method into algorithmic trading strategies. Experimental results demonstrate how L1 trend filtering can enhance signal stability, trade timing, and overall robustness of trading systems.

Neural Networks Made Easy (Part 92): Adaptive Forecasting in Frequency and Time Domains
The authors of the FreDF method experimentally confirmed the advantage of combined forecasting in the frequency and time domains. However, the use of the weight hyperparameter is not optimal for non-stationary time series. In this article, we will get acquainted with the method of adaptive combination of forecasts in frequency and time domains.

Neural Networks in Trading: State Space Models
A large number of the models we have reviewed so far are based on the Transformer architecture. However, they may be inefficient when dealing with long sequences. And in this article, we will get acquainted with an alternative direction of time series forecasting based on state space models.


Neural Networks Made Easy (Part 84): Reversible Normalization (RevIN)
We already know that pre-processing of the input data plays a major role in the stability of model training. To process "raw" input data online, we often use a batch normalization layer. But sometimes we need a reverse procedure. In this article, we discuss one of the possible approaches to solving this problem.

Creating a Trading Administrator Panel in MQL5 (Part VIII): Analytics Panel
Today, we delve into incorporating useful trading metrics within a specialized window integrated into the Admin Panel EA. This discussion focuses on the implementation of MQL5 to develop an Analytics Panel and highlights the value of the data it provides to trading administrators. The impact is largely educational, as valuable lessons are drawn from the development process, benefiting both upcoming and experienced developers. This feature demonstrates the limitless opportunities this development series offers in equipping trade managers with advanced software tools. Additionally, we'll explore the implementation of the PieChart and ChartCanvas classes as part of the continued expansion of the Trading Administrator panel’s capabilities.

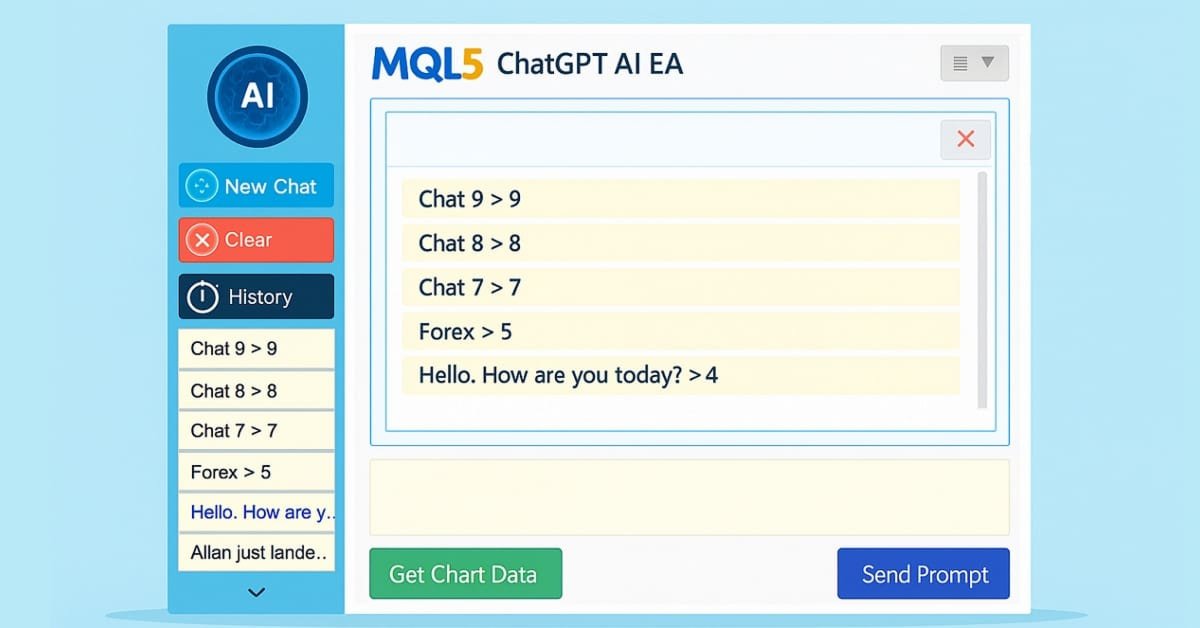
Building AI-Powered Trading Systems in MQL5 (Part 5): Adding a Collapsible Sidebar with Chat Popups
In Part 5 of our MQL5 AI trading system series, we enhance the ChatGPT-integrated Expert Advisor by introducing a collapsible sidebar, improving navigation with small and large history popups for seamless chat selection, while maintaining multiline input handling, persistent encrypted chat storage, and AI-driven trade signal generation from chart data.


Neural Networks in Trading: Multi-Task Learning Based on the ResNeXt Model
A multi-task learning framework based on ResNeXt optimizes the analysis of financial data, taking into account its high dimensionality, nonlinearity, and time dependencies. The use of group convolution and specialized heads allows the model to effectively extract key features from the input data.