MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Quantum Computing and Gradient Boosting in EURUSD Trading
The article describes the practical implementation of a hybrid algorithmic trading system that combines quantum computing (IBM Qiskit) and gradient boosting (CatBoost) to predict movements in the EURUSD pair on the hourly time frame. The system extracts four unique quantum features from a probability distribution across 256 states using eight qubits and, in combination with classical indicators and delta encoding of time categories, achieves 62% accuracy on 15,000 candlesticks.

Neural networks made easy (Part 77): Cross-Covariance Transformer (XCiT)
In our models, we often use various attention algorithms. And, probably, most often we use Transformers. Their main disadvantage is the resource requirement. In this article, we will consider a new algorithm that can help reduce computing costs without losing quality.


Engineering a Self-Healing Expert Advisor in MQL5 (Part 5): Real-Time Recovery Dashboard (Final Part)
This article implements a real-time monitoring dashboard for a self-healing MetaTrader 5 Expert Advisor. The dashboard displays the current EA state, virtual stop-loss and take-profit levels, breakeven and trailing status, recovery state, synchronization status, and heartbeat information directly on the chart. By exposing the internal recovery state visually, the Expert Advisor becomes easier to monitor, verify, and troubleshoot while managing active trades.


MQL5 Wizard Techniques you should know (Part 10). The Unconventional RBM
Restrictive Boltzmann Machines are at the basic level, a two-layer neural network that is proficient at unsupervised classification through dimensionality reduction. We take its basic principles and examine if we were to re-design and train it unorthodoxly, we could get a useful signal filter.


Interactive Supply and Demand Zone Manager in MQL5 (Part III): Zone Analysis, Stateful Interaction, and Pending Event Management
We extend the stateful supply and demand framework for MetaTrader 5 with a quantitative admission model and a dedicated interaction engine. Candidate zones are scored by structural symmetry, volume participation, and ATR‑normalized displacement, then classified into objective tiers. Admitted zones follow a deterministic lifecycle that tracks first touch, validates bounces, or confirms breakouts, with full telemetry for analysis and reproducibility.


A Practical Kalman Filter Price Smoother in MQL5: Adaptive Noise Estimation Without External Libraries
Fixed-weight moving averages introduce regime-insensitive lag. This work presents an adaptive scalar Kalman filter indicator in native MQL5 that estimates process noise Q from rolling return variance and measurement noise R from rolling price variance, with floor clamps for stability, and recomputes the Kalman Gain on every bar. The chart-overlay output is benchmarked against a 20-period EMA using MAE, RMSE, lag, and smoothness metrics to quantify tracking and noise suppression.


Developing a Replay System (Part 57): Understanding a Test Service
One point to note: although the service code is not included in this article and will only be provided in the next one, I'll explain it since we'll be using that same code as a springboard for what we're actually developing. So, be attentive and patient. Wait for the next article, because every day everything becomes more interesting.


Symbolic Price Forecasting Equation Using SymPy
The article describes an interesting approach to algorithmic trading based on symbolic mathematical equations instead of traditional machine learning "black boxes". The author demonstrates how to transform opaque neural networks into readable mathematical equations using the SymPy library and polynomial regression, allowing for a full understanding of the logic behind trading decisions. The approach combines the computational power of ML with the transparency of classical methods, giving traders the ability to analyze, adjust, and adapt models in real time.


Neural Networks in Trading: Hyperbolic Latent Diffusion Model (HypDiff)
The article considers methods of encoding initial data in hyperbolic latent space through anisotropic diffusion processes. This helps to more accurately preserve the topological characteristics of the current market situation and improves the quality of its analysis.

MQL5 Trading Toolkit (Part 6): Expanding the History Management EX5 Library with the Last Filled Pending Order Functions
Learn how to create an EX5 module of exportable functions that seamlessly query and save data for the most recently filled pending order. In this comprehensive step-by-step guide, we will enhance the History Management EX5 library by developing dedicated and compartmentalized functions to retrieve essential properties of the last filled pending order. These properties include the order type, setup time, execution time, filling type, and other critical details necessary for effective pending orders trade history management and analysis.


Building Volatility Models in MQL5 (Part III): Implementing the SLSQP Algorithm for Model Estimation
An SLSQP optimizer is implemented in MQL5 to resolve parameter discrepancies between a volatility library and Python's ARCH module. The article details constraint handling, gradient options, configuration, and convergence controls and shows how to integrate the solver into existing code. Practical examples and comparisons demonstrate matched log‑likelihoods and parameters on shared datasets.


Atmosphere Clouds Model Optimization (ACMO): Theory
The article is devoted to the metaheuristic Atmosphere Clouds Model Optimization (ACMO) algorithm, which simulates the behavior of clouds to solve optimization problems. The algorithm uses the principles of cloud generation, movement and propagation, adapting to the "weather conditions" in the solution space. The article reveals how the algorithm's meteorological simulation finds optimal solutions in a complex possibility space and describes in detail the stages of ACMO operation, including "sky" preparation, cloud birth, cloud movement, and rain concentration.


Bivariate Copulae in MQL5 (Part 3): Implementation and Tuning of Mixed Copula Models in MQL5
The article extends our copula toolkit with mixed copulas implemented natively in MQL5. We construct Clayton–Frank–Gumbel and Clayton–Student–t–Gumbel mixtures, estimate them via EM, and enable sparsity control through SCAD with cross‑validation. Provided scripts tune hyperparameters, compare mixtures using information criteria, and save trained models. Practitioners can apply these components to capture asymmetric tail dependence and embed the selected model in indicators or Expert Advisors.


From Basic to Intermediate: Struct (IV)
In this article, we will explore how to create so-called structural code, where the entire context and methods for manipulating variables and information are placed within a structure to create a suitable context for implementing any code. Therefore, we will examine the necessity of using a private section of the code to separate what is public from what is not, thereby adhering to the rule of encapsulation and preserving the context for which the data structure was created.


Implementing Practical Modules from Other Languages in MQL5 (Part 05): The Logging module from Python, Log Like a Pro
Integrating Python's logging module with MQL5 empowers traders with a systematic logging approach, simplifying the process of monitoring, debugging, and documenting trading activities. This article explains the adaptation process, offering traders a powerful tool for maintaining clarity and organization in trading software development.


Automating Chart Patterns in MQL5 (Part 2): The Double Top and Double Bottom
We build a robust MQL5 detector for double tops and double bottoms that first confirms the H4 trend, then validates six conditions (point equality, neckline placement, ordering, width, height, and ATR‑based tolerances). The neckline break is timed on the chart's timeframe, and a three-state machine ensures each pattern trades once. The measured‑move target translates structure into clear exits.


MQL5 Trading Tools (Part 27): Rendering Parametric Butterfly Curve on Canvas
In this article, we explore the butterfly curve, a parametric mathematical equation, and render it visually on a MQL5 canvas. We build an interactive display with a draggable, resizable canvas window, supersampled curve rendering, gradient backgrounds, and a color-segmented legend. By the end, we have a fully functional visual tool that plots the butterfly curve directly on the MetaTrader 5 chart.


MQL5 Trading Tools (Part 38): Adding a Tabbed Settings Window for Editing Object Properties
We add a tabbed settings window opened from the ribbon and bound to the selected object. The tabs — Style, Text, Coordinates, and Visibility — are built from the same descriptor system, with scrolling, per-level rows, and shared color/width/style popovers. The article covers layout, rendering, interaction, and inline price/time and numeric editing. You get one place to edit every property with live preview and commit-or-discard on close.


Seasonality Indicator by Hours, Days of the Week, and Days of the Month
The article explains how to develop a tool for analyzing recurring price patterns in financial markets — by day of the month (1-31), day of the week (Monday-Sunday), or hour of the day (0-23). The indicator analyzes historical data, calculates the average return for each period, and displays the results as a histogram with a forecast. It includes customizable parameters: seasonality type, number of bars analyzed, display as percentages or absolute values, chart colors.


Biogeography-Based Optimization (BBO)
Biogeography-Based Optimization (BBO) is an elegant global optimization method inspired by natural processes of species migration between islands within archipelagos. The algorithm is based on a simple yet powerful idea: high-quality solutions actively share their characteristics, while low-quality ones actively adopt new features, creating a natural flow of information from the best solutions to the worst. A unique adaptive mutation operator provides an excellent balance between exploration and exploitation. BBO demonstrates high efficiency on a variety of tasks.


Building an Object-Oriented Order Block Engine in MQL5
The article presents a production-oriented Order Block engine for MQL5 packaged as an include class, it validates zones via displacement and market structure break, maintains mitigation state only on closed bars, and avoids heavy copies by passing data by reference. A diagnostic indicator plots zones, and an EA gates logic to new bars for stable performance and reproducible tests.


Quantum Neural Network in MQL5 (Part II): Training a Neural Network with Backpropagation on ALGLIB Markov Matrices
The article presents an innovative quantum neural network architecture for algorithmic trading that combines the principles of quantum mechanics with modern machine learning methods. The system includes quantum effects (resonance, interference, decoherence), multi-level memory of different time scales, Markov chains with the ALGLIB library, and adaptive parameter control. The full implementation is done in MQL5 using the built-in matrix/vector types, which removes implementation barriers in MetaTrader 5.


Developing a Replay System (Part 60): Playing the Service (I)
We have been working on just the indicators for a long time now, but now it's time to get the service working again and see how the chart is built based on the data provided. However, since the whole thing is not that simple, we will have to be attentive to understand what awaits us ahead.


MQL5 Trading Tools (Part 28): Filling Sweep Polygons for Butterfly Curve in MQL5
We expand the capabilities of the MetaTrader 5 butterfly curve canvas by adding multi-layered wing fills, vein lines, scale dots, and a full body (abdomen, thorax, head, eyes, antennae). This article implements polygon fills with vertical and radial gradients, as well as filled circles and ellipses, all using supersampling antialiasing. You will also receive reusable MQL5 helper functions and a rendering order that transforms a simple curve into a customizable, detailed chart illustration.


Position Management: A Reusable Trade Journal with Live Maximum Adverse Excursion, Maximum Favorable Excursion, and R-Multiple Tracking in MQL5
This article presents CTradeJournal, a self-contained MQL5 class for live tracking of open positions at tick frequency. It maintains MAE, MFE, and initial risk in money, calculates the R-multiple when a position closes, and writes a complete CSV record. The text explains the design choices, provides the implementation, and shows simple EA integration so you can analyze entries, stop placement, and outcome distribution.


Execution Cost and Slippage Sensitivity Analyzer
Backtests often understate spread, commission, and slippage. This MQL5 analyzer loads closing deals and simulates rising execution costs to measure robustness. It computes the breakeven cost per deal, the cushion over an assumed cost, the net profit and profit factor at that cost, and how many winners turn into losers, then summarizes the result with an A+ to F grade and targeted guidance.


Community of Scientists Optimization (CoSO): Practice
We resume the topic of optimization by the scientific community. CoSO should not be viewed as a ready-made solution, but as a promising research platform. With proper development, CoSO can find its niche in tasks where adaptability and resilience to change are important, and computation time is not critical.


Building a Modular Fair Value Gap (FVG) Detection Engine in MQL5
This article introduces a modular Fair Value Gap (FVG) detection engine for MQL5 packaged as a reusable include class, it evaluates imbalance zones on closed bars, applies a Simple True Range average filter to eliminate low-volatility noise, and supports wick-touch and close-through mitigation. A companion diagnostic indicator plots active gaps, and an Expert Advisor template demonstrates automated pullback entries with new-bar execution controls.


Gaussian Processes in Machine Learning (Part 1): Classification Model in MQL5
The article considers the classification model of Gaussian processes. We will start by studying its theoretical principles moving on to the practical development of the GP library in MQL5.


Introduction to MQL5 (Part 38): Mastering API and WebRequest Function in MQL5 (XII)
Create a practical bridge between MetaTrader 5 and Binance: fetch 30‑minute klines with WebRequest, extract OHLC/time values from JSON, and confirm a bullish engulfing pattern using only completed candles. Then assemble the query string, compute the HMAC‑SHA256 signature, add X‑MBX‑APIKEY, and submit authenticated orders. You get a clear, end‑to‑end EA workflow from data acquisition to order execution.

Reimagining Classic Strategies in MQL5 (Part II): FTSE100 and UK Gilts
In this series of articles, we explore popular trading strategies and try to improve them using AI. In today's article, we revisit the classical trading strategy built on the relationship between the stock market and the bond market.


Developing a Multi-Currency Expert Advisor (Part 28): Adding a Position Closing Manager
When running multiple strategies in parallel, you may want to periodically close all open positions and start the strategies over again. The existing code only allows this behavior to be implemented through manual intervention. Let's try to automate this part.


Graph Theory: Traversal Breadth-First Search (BFS) Applied in Trading
Breadth First Search (BFS) uses level-order traversal to model market structure as a directed graph of price swings evolving through time. By analyzing historical bars or sessions layer by layer, BFS prioritizes recent price behavior while still respecting deeper market memory.


Population optimization algorithms: Bacterial Foraging Optimization - Genetic Algorithm (BFO-GA)
The article presents a new approach to solving optimization problems by combining ideas from bacterial foraging optimization (BFO) algorithms and techniques used in the genetic algorithm (GA) into a hybrid BFO-GA algorithm. It uses bacterial swarming to globally search for an optimal solution and genetic operators to refine local optima. Unlike the original BFO, bacteria can now mutate and inherit genes.


Feature Engineering for ML (Part 7): Entropy Features in Python
The article provides production-ready entropy estimators (Shannon, plug-in, Lempel–Ziv, Kontoyiannis) operating on tick-rule–encoded sequences. It resolves three correctness and performance issues in the original code, verifies outputs against chapter references, and extends encoding with quantile and sigma options. Users gain reproducible results and markedly improved computation speed for large bar sets.

Neural networks made easy (Part 69): Density-based support constraint for the behavioral policy (SPOT)
In offline learning, we use a fixed dataset, which limits the coverage of environmental diversity. During the learning process, our Agent can generate actions beyond this dataset. If there is no feedback from the environment, how can we be sure that the assessments of such actions are correct? Maintaining the Agent's policy within the training dataset becomes an important aspect to ensure the reliability of training. This is what we will talk about in this article.


Online Machine Learning for Trade Signal Filtering in MQL5 (Part 1)
This article implements an online logistic‑regression trade filter in native MQL5 and integrates it into an EMA‑crossover EA with a closed‑trade feedback loop. It details the shared class, features, SGD update, persistence, and a read‑only probability view. Synthetic experiments cover multi‑seed separation, calibration, feature ablation, regime‑shift baselines, and hyperparameter sweeps. You get reproducible scripts and a walk‑forward protocol to validate the filter on your own instrument.

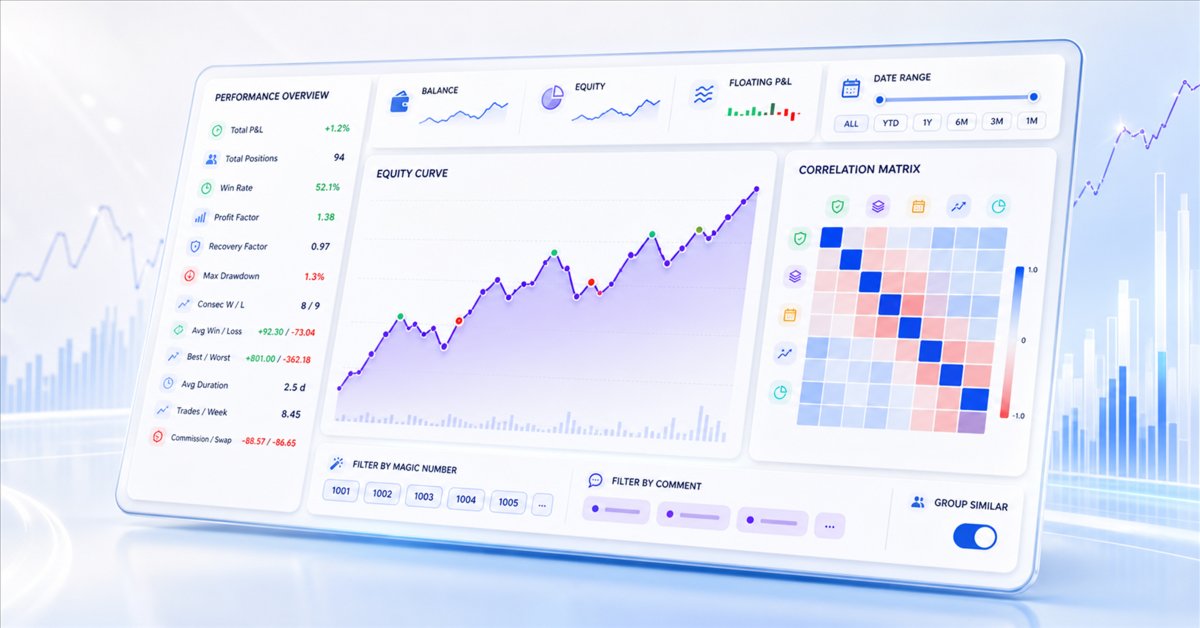
Creating an Interactive Portfolio Analyzer Dashboard with CCanvas in MQL5
This article presents a standalone Portfolio Analyzer dashboard implemented as an Expert Advisor for MetaTrader 5. It reads account deal history, reconstructs closed positions, and attributes results by magic number or normalized comment to deliver clear per-strategy metrics. The interface provides a vector equity curve, date filters, and strategy selectors, plus a Pearson correlation matrix to reveal strategy redundancy. You can attach it to a separate chart without modifying existing trading EAs.


Market Simulation (Part 12): Sockets (VI)
In this article, we will look at how to solve certain problems and issues that arise when using Python code within other programs. More specifically, we will demonstrate a common issue encountered when using Excel in conjunction with MetaTrader 5, although we will be using Python to facilitate this interaction. However, this implementation has a minor drawback. It does not occur in all cases, but only in certain specific situations. When it does happen, it is necessary to understand the cause. In today’s article, we will begin explaining how to resolve this issue.

Custom Debugging and Profiling Tools for MQL5 Development (Part II): Profiling EAs and Testing Trading Logic
We build a compact profiler that records calls, min/max/average times, and slow-call counts to CSV, and a simple test runner that writes deterministic pass/fail reports. The article explains where to place measurements in an EA, how to sample ticks, and how to keep pure calculations testable. Running the script first and the profiling EA second provides repeatable evidence for regression analysis.