Articles on MetaTrader 5 integration using MQL5

Traders meet interesting challenges which often require an innovative approach. This category features articles that offer the most unexpected solutions for evaluating, analyzing and processing price data and trading results. The articles describe various integration solutions, including connection of databases and ICQ, use of OpenCL and social networks, use of Delphi and C#.
Read on to learn how to use specialized mathematical and neural packages, and much more. Become an author and share unique ideas with the MQL5.community members.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Adaptive Social Behavior Optimization (ASBO): Two-phase evolution
We continue dwelling on the topic of social behavior of living organisms and its impact on the development of a new mathematical model - ASBO (Adaptive Social Behavior Optimization). We will dive into the two-phase evolution, test the algorithm and draw conclusions. Just as in nature a group of living organisms join their efforts to survive, ASBO uses principles of collective behavior to solve complex optimization problems.


Determining Fair Exchange Rates Using PPP and IMF Data
Building a purchasing power parity (PPP)-based exchange rate analysis system using Python. The author developed an algorithm with 5 methods for calculating fair exchange rates using IMF data. A practical guide to fundamental currency analysis, economic data processing, and integration with trading systems. Full code in open source.


The case for using Hospital-Performance Data with Perceptrons, this Q4, in weighing SPDR XLV's next Performance
XLV is SPDR healthcare ETF and in an age where it is common to be bombarded by a wide array of traditional news items plus social media feeds, it can be pressing to select a data set for use with a model. We try to tackle this problem for this ETF by sizing up some of its critical data sets in MQL5.


Exchange Market Algorithm (EMA)
The article presents a detailed analysis of the Exchange Market Algorithm (EMA) inspired by the behavior of stock market traders. The algorithm simulates stock trading, where market participants with varying levels of success employ different strategies to maximize profits.


Integrating MQL5 with Data Processing Packages (Part 9): Entropy-Based Adaptive Volatility
This work presents an end-to-end pipeline: collect MetaTrader 5 data, engineer entropy/volatility/trend features, train a PyTorch classifier, and expose predictions through a Flask API. An MQL5 EA posts rolling prices each tick, receives probability and regime, and applies adaptive position sizing and stop distances. The result is a clear recipe for integrating ML inference with MetaTrader 5.


Market Simulation (Part 24): Position View (II)
In this article, I will show how to use an indicator to track open positions on the trading server in the simplest and most practical way possible. I am doing this step by step to show that you do not necessarily have to move all of this into an Expert Advisor. Many of you have probably become used to doing that for one reason or another. In fact, that is not really justified, because as this implementation evolves, it will become clear that you can create or implement different types of indicators for this purpose.


The MQL5 Standard Library Explorer (Part 14): Building a Dynamic Hedge EA with the ALGLIB Port (ap.mqh)
This article introduces ap.mqh, the ALGLIB port for MQL5, and demonstrates its use in multi‑asset workflows that require robust linear algebra. It covers why built-in indicators fall short, then implements polynomial regression, a rolling correlation matrix indicator, and an adaptive hedge ratio estimator using ridge regression with Cholesky. Practical code shows how to compute spread z‑scores and execute coordinated pairs trades entirely within MetaTrader 5.


Market Simulation (Part 22): Getting Started with SQL (V)
Before you give up and decide to abandon learning SQL, allow me to remind you, dear readers, that here we are still using only the most basic elements. We have not yet looked at some of SQL's capabilities. Once you understand them, you will see that SQL is far more practical than it seems. Although, most likely, we will eventually change the direction of what we are building, because the creation process is dynamic. We will show a little more about creating different things in SQL, because this is truly important and useful for you. Simply thinking that you are more capable than an entire community of programmers and developers will only lead to wasted time and opportunities. Do not worry, because what comes next will be even more interesting.


Bison Algorithm (BIA)
A new optimization method, the Bison Algorithm (BIA), uses two strategies, inspired by the behavior of bison, for solving continuous problems with a single objective function. The key features of BIA are two fundamental principles borrowed from the behavior of bison: the ability to move dynamically and a defensive strategy.


Market Simulation (Part 24): Getting Started with SQL (VII)
In the previous article, we completed the necessary introduction to SQL. And, in my opinion, we properly clarified what we wanted to show and explain about SQL. This was done so that anyone who comes to look at the market replay/simulation system being built can at least get an idea of what may be happening there. The point is that there is no sense in programming things that SQL handles perfectly.


Building an Object-Oriented ONNX Inference Engine in MQL5
This article shows how to run Python-trained models natively in MetaTrader 5 via the terminal's ONNX functions. We build an MQL5 class that encapsulates session creation, fixes input/output tensor shapes, applies min-max feature normalization to mirror training, and executes OnnxRun once per bar to protect the CPU, the result is a reliable, maintainable inference path for live charts and the Strategy Tester without sockets or DLLs.

MQL5 Trading Toolkit (Part 7): Expanding the History Management EX5 Library with the Last Canceled Pending Order Functions
Learn how to complete the creation of the final module in the History Manager EX5 library, focusing on the functions responsible for handling the most recently canceled pending order. This will provide you with the tools to efficiently retrieve and store key details related to canceled pending orders with MQL5.


Building a Broker-Agnostic Symbol Resolution Layer in MQL5
We implement a symbol resolution framework that abstracts broker naming differences in MetaTrader 5. Using a persistent mapping store, layered resolution with validation, a hash-indexed registry, and a cache, it returns selectable symbols with live market data and logs unresolved cases. Practically, you can deploy the same EA across brokers and keep symbol access consistent at low runtime cost.


Duelist Algorithm
What if your trading strategies could learn from each other, like real fighters? Duelist Algorithm is a new optimization method where trading system parameters literally duel for the right to be called the best.


Elite Crystal Evolution Algorithm (CEO-inspired): Theory
A new original population-based algorithm, ECEA, is presented. Inspired by the process of water freezing, it adapts ideas from the Crystal Energy Optimizer (CEO) algorithm, which uses graph-based search, for general optimization problems. The algorithm uses a dynamic elite group, three search strategies, and a periodic diversification mechanism.

Developing an MQTT client for Metatrader 5: a TDD approach — Part 5
This article is the fifth part of a series describing our development steps of a native MQL5 client for the MQTT 5.0 protocol. In this part we describe the structure of PUBLISH packets, how we are setting their Publish Flags, encoding Topic Name(s) strings, and setting Packet Identifier(s) when required.

Population optimization algorithms: Resistance to getting stuck in local extrema (Part I)
This article presents a unique experiment that aims to examine the behavior of population optimization algorithms in the context of their ability to efficiently escape local minima when population diversity is low and reach global maxima. Working in this direction will provide further insight into which specific algorithms can successfully continue their search using coordinates set by the user as a starting point, and what factors influence their success.

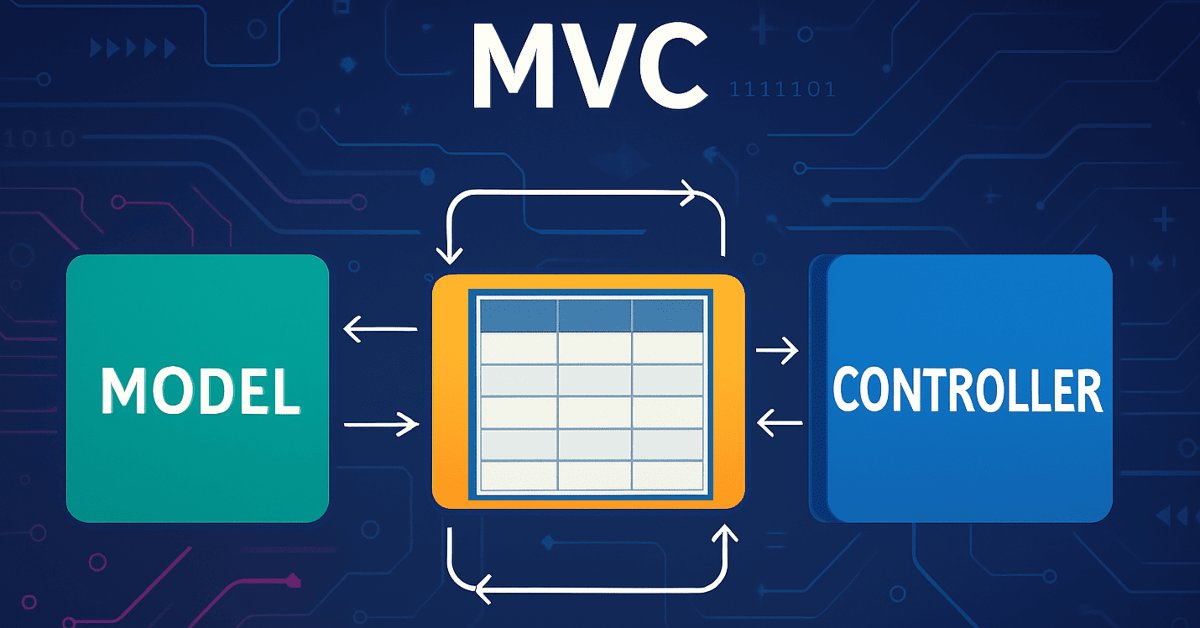
Implementation of a table model in MQL5: Applying the MVC concept
In this article, we look at the process of developing a table model in MQL5 using the MVC (Model-View-Controller) architectural pattern to separate data logic, presentation, and control, enabling structured, flexible, and scalable code. We consider implementation of classes for building a table model, including the use of linked lists for storing data.


Introduction to MQL5 (Part 37): Mastering API and WebRequest Function in MQL5 (XI)
In this article, we show how to send authenticated requests to the Binance API using MQL5 to retrieve your account balance for all assets. Learn how to use your API key, server time, and signature to securely access account data, and how to save the response to a file for future use.

Header in the Connexus (Part 3): Mastering the Use of HTTP Headers for Requests
We continue developing the Connexus library. In this chapter, we explore the concept of headers in the HTTP protocol, explaining what they are, what they are for, and how to use them in requests. We cover the main headers used in communications with APIs, and show practical examples of how to configure them in the library.


Competitive Learning Algorithm (CLA)
The article presents the Competitive Learning Algorithm (CLA), a new metaheuristic optimization method based on simulating the educational process. The algorithm organizes the population of solutions into classes with students and teachers, where agents learn through three mechanisms: following the best in the class, using personal experience, and sharing knowledge between classes.


Custom Debugging and Profiling Tools for MQL5 Development (Part III): Regression Gates for Performance and Trading Rules
This article adds a regression gate to the MQL5 debugging and profiling workflow. It keeps the Part II profiler, TestLite runner, and trading math helper as contracts, then compares current profiler evidence with an accepted baseline. The workflow also adds symbol-aware assertions, compact status files, and report tables so performance drift, missing tests, and broker-assumption problems are visible before a build is accepted.


Overcoming Accessibility Problems in MQL5 Trading Tools (Part VII): MetaTrader 5 Model Context Protocol (MCP) the Grand Solution
Many traders know what they want to analyze or automate but cannot navigate MetaTrader 5, use MetaEditor, or translate an idea into working MQL5 code. This article shows how the AI Assistant and MCP turn one natural-language prompt into a complete workflow: strategy development, editing, debugging, chart interaction, testing, and permission-controlled trading. We apply the process by building MCP_Accessibility_Assistant.mq5, leaving you with a working, accessible EA and a reusable prompt-driven development method.


Body in Connexus (Part 4): Adding HTTP body support
In this article, we explored the concept of body in HTTP requests, which is essential for sending data such as JSON and plain text. We discussed and explained how to use it correctly with the appropriate headers. We also introduced the ChttpBody class, part of the Connexus library, which will simplify working with the body of requests.


Introduction to MQL5 (Part 34): Mastering API and WebRequest Function in MQL5 (VIII)
In this article, you will learn how to create an interactive control panel in MetaTrader 5. We cover the basics of adding input fields, action buttons, and labels to display text. Using a project-based approach, you will see how to set up a panel where users can type messages and eventually display server responses from an API.


How to Implement Competition Among LLM Agents in MetaTrader 5
The article describes a competitive architecture for MetaTrader 5 in which ten LLM agents, each with different trading rules, manage their own capital and open independent positions using unique magic numbers. The system prompt and the agent's trading aggressiveness are adjusted based on PnL results and the trade streak. A reproducible framework with operating modes and monitored metrics is presented, suitable for testing and further optimization.

Connexus Observer (Part 8): Adding a Request Observer
In this final installment of our Connexus library series, we explored the implementation of the Observer pattern, as well as essential refactorings to file paths and method names. This series covered the entire development of Connexus, designed to simplify HTTP communication in complex applications.


Developing an MQTT client for Metatrader 5: a TDD approach — Part 6
This article is the sixth part of a series describing our development steps of a native MQL5 client for the MQTT 5.0 protocol. In this part we comment on the main changes in our first refactoring, how we arrived at a viable blueprint for our packet-building classes, how we are building PUBLISH and PUBACK packets, and the semantics behind the PUBACK Reason Codes.


Market Simulation: (Part 11): Sockets (V)
We are beginning to implement the connection between Excel and MetaTrader 5, but first we need to understand some key points. This way, you won't have to rack your brains trying to figure out why something works or doesn't. And before you frown at the prospect of integrating Python and Excel, let's see how we can (to some extent) control MetaTrader 5 through Excel using xlwings. What we demonstrate here will primarily focus on educational objectives. However, don't think that we can only do what will be covered here.


Downloading International Monetary Fund Data Using Python
Downloading international monetary fund data in Python: Mining IMF data for use in macroeconomic currency strategies. How can macroeconomics help an ordinary and an algorithmic trader?


Developing a Multi-Currency Expert Advisor (Part 30): From Trading Strategy to Launching a Multi-Currency Expert Advisor
The article outlines the complete process of creating a multi-currency Expert Advisor using the Adwizard library for MetaTrader 5: from setting up the environment for creating optimization projects to obtaining the final multi-currency Expert Advisors, which combine multiple instances of a simple trading strategy. We will walk through setting up the necessary input parameters, conventions for convenient file names, and launching three instances of the final Expert Advisors on different trading accounts with different parameters.


Trading with the MQL5 Economic Calendar (Part 12): SQLite Storage and Deduplication
In this article, we replace the embedded CSV snapshot with a SQLite layer that persists calendar events and triggered trade IDs across restarts. The database lives in the common terminal folder and is shared by live charts and the strategy tester, so both modes read the same data without recompiling. An on-demand downloader with a canvas progress bar fetches history from the calendar API and stores it for offline reuse.


Developing a Terminal Manager (Part 1): Problem Statement
How can we conveniently monitor multiple terminals running Expert Advisors, especially when they are on different computers? Let's try to create a web interface for managing the launch of MetaTrader 5 trading terminals and viewing detailed information about the operation of each instance.


Beyond GARCH (Part III): Building the MMAR and the Verdict
With the multifractal parameters from Part 2 in hand, this article builds the full MMAR process. We construct the multiplicative cascade for trading time, generate Fractional Brownian Motion via Davies-Harte FFT, and combine both into X(t) = B_H[theta(t)]. A 1000-path Monte Carlo simulation produces the volatility forecast, which we then pit against GARCH on the same EURUSD M5 data. Does Mandelbrot's fractal architecture outforecast Engle's conditional variance framework? Part 3 of a eight-part series leading to a native MQL5 library and Expert Advisor.


Integrating MQL5 with Data Processing Packages (Part 10): Deploying Python AutoML Pipelines for Strategy Testing
This article presents a reproducible MetaTrader 5 workflow: collect history, engineer nine context features, label simulated EMA crossover trades, train with FLAML, and export to ONNX with fixed opset and plain probabilities. The Expert Advisor loads the model natively, mirrors the Python feature contract, and uses a tunable confidence threshold as a trade filter. Readers can swap signals and features to reuse the same pipeline.


Building Your Personal Expert Advisor (Part 4): Risk Management III—Risk Models and Order Execution
The EA now defines risk by percentage, fixed cash, or fixed lot and can measure percentage against balance or equity. It supports market, limit, and stop orders, sizes from the planned entry, and enforces spread‑aware stop minima. Additional safeguards include downward volume rounding, explicit handling when the minimum lot exceeds target risk, and pending‑order distance/expiry checks, organized under a Plan–Validate–Execute structure.


How to Replace a WebSocket EA with TradeMux REST in MetaTrader 5
The article continues the series on AI Hedge Fund and addresses three limitations of v4: analysts' reputation scores are now stored persistently in SQLite, the EA has been removed from the critical execution path, and signals from the council of fifteen are distributed to multiple brokers via the TradeMux REST API. The logic behind the council and risk management has remained the same: Python retrieves data via the MetaTrader 5 SDK and executes orders directly. The result is resilience to restarts and scalability across multiple terminals.


Eco-inspired Evolutionary Algorithm (ECO)
The article discusses the ECO optimization algorithm, which is based on ecological concepts: populations are grouped into habitats based on territorial proximity, exchange genetic material within habitats, and migrate between them. Despite its wide range of operators and elegant biological metaphor, the algorithm produced a certain result discussed below.


Market Simulation: Position View (III)
In previous articles, we mentioned that sometimes we need to set a value for the ZOrder property. But why? The reason is that many pieces of code that add objects to a chart simply do not use, or more precisely do not define, a value for this property. The point is that I am not here to say what every programmer should or should not do, or how they should or should not write their code. I am here to show you, dear reader, and everyone who truly wants to understand how these processes work internally, what actually happens behind the scenes.


Dendritic Cell Algorithm (DCA)
The Dendritic Cell Algorithm (DCA) is a metaheuristic inspired by the mechanisms of the innate immune system. Dendritic cells patrol the search space, accumulate signals about the quality of positions, and reach a collective decision: whether to exploit what they have found or to continue exploration. Let's take a look at how a biological model for detecting pathogens is transformed into an optimization algorithm.