MQL4 and MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Neural networks made easy (Part 60): Online Decision Transformer (ODT)
The last two articles were devoted to the Decision Transformer method, which models action sequences in the context of an autoregressive model of desired rewards. In this article, we will look at another optimization algorithm for this method.


Interview with Valery Mazurenko (ATC 2011)
The task of writing an Expert Advisor trading on multiple currency pairs is complex both in terms of finding suitable strategies and from the technological side. But if the goal is set clear, nothing is impossible then. It was four times already that Vitaly Mazurenko (notused) submitted his multi-currency Expert Advisor. It seems, he has managed to find the right way this time.


Formulating Dynamic Multi-Pair EA (Part 6): Adaptive Spread Sensitivity for High-Frequency Symbol Switching
In this part, we will focus on designing an intelligent execution layer that continuously monitors and evaluates real-time spread conditions across multiple symbols. The EA dynamically adapts its symbol selection by enabling or disabling trading based on spread efficiency rather than fixed rules. This approach allows high-frequency multi-pair systems to prioritize cost-effective symbols.


Market Simulation (Part 14): Sockets (VIII)
Many programmers might assume we should abandon using Excel and move directly to Python, using some packages that allow Python to generate an Excel file for later analysis of results. However, as mentioned in the previous article, although this solution is the simplest for many programmers, it will not be accepted by some users. And in this particular case, the user is always right. As programmers, we must find a way to make everything work.


Polynomial models in trading
This article is about orthogonal polynomials. Their use can become the basis for a more accurate and effective analysis of market information allowing traders to make more informed decisions.

Dimitar Manov: "I fear only extraordinary situations in the Championship" (ATC 2010)
In the recent review by Boris Odintsov the Expert Advisor of the Bulgarian Participant Dimitar Manov appeared among the most stable and reliable EAs. We decided to interview this developer and try to find the secret of his success. In this interview Dimitar has told us what situation would be unfavorable for his robot, why he's not using indicators and whether he is expecting to win the competition.


Category Theory in MQL5 (Part 13): Calendar Events with Database Schemas
This article, that follows Category Theory implementation of Orders in MQL5, considers how database schemas can be incorporated for classification in MQL5. We take an introductory look at how database schema concepts could be married with category theory when identifying trade relevant text(string) information. Calendar events are the focus.

MQL5 Wizard Techniques you should know (Part 13): DBSCAN for Expert Signal Class
Density Based Spatial Clustering for Applications with Noise is an unsupervised form of grouping data that hardly requires any input parameters, save for just 2, which when compared to other approaches like k-means, is a boon. We delve into how this could be constructive for testing and eventually trading with Wizard assembled Expert Advisers


Feature Engineering for ML (Part 14): Trend-Scanning Features in MQL5
A naive MQL5 port of trend-scanning features recomputes each candidate window per bar at O(H·L) cost. This article introduces CTrendScanningFeatures.mqh, which maintains three running sums per horizon and updates them in O(1) per bar, verified against a Python reference. The indicator exposes four causal buffers - window, slope, t_value, rsquared - at the confirmation bar and corrects a sign inversion present in the original backward labeling mode.


Developing a Multi-Currency Expert Advisor (Part 29): Improving the Conveyor
We are going to improve the usability of the automated optimization conveyor: we will explore the process from creating an optimization project to testing the final EA. For clarity, let us walk through the entire process step by step creating the final EA, while stopping to make any desired corrections.


Developing a Replay System (Part 74): New Chart Trade (I)
In this article, we will modify the last code shown in this series about Chart Trade. These changes are necessary to adapt the code to the current replay/simulation system model. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


Risk-Based Trade Placement EA with On-Chart UI (Part 1): Designing the User Interface
Learn how to build a clean and professional on-chart control panel in MQL5 for a Risk-Based Trade Placement Expert Advisor. This step-by-step guide explains how to design a functional GUI that allows traders to input trade parameters, calculate lot size, and prepare for automated order placement.


MQL5 Wizard Techniques you should know (Part 37): Gaussian Process Regression with Linear and Matérn Kernels
Linear Kernels are the simplest matrix of its kind used in machine learning for linear regression and support vector machines. The Matérn kernel on the other hand is a more versatile version of the Radial Basis Function we looked at in an earlier article, and it is adept at mapping functions that are not as smooth as the RBF would assume. We build a custom signal class that utilizes both kernels in forecasting long and short conditions.


Creating an MQL5-Telegram Integrated Expert Advisor (Part 7): Command Analysis for Indicator Automation on Charts
In this article, we explore how to integrate Telegram commands with MQL5 to automate the addition of indicators on trading charts. We cover the process of parsing user commands, executing them in MQL5, and testing the system to ensure smooth indicator-based trading

Trading with the MQL5 Economic Calendar (Part 10): Draggable Dashboard and Interactive Hover Effects for Seamless News Navigation
In this article, we enhance the MQL5 Economic Calendar by introducing a draggable dashboard that allows us to reposition the interface for better chart visibility. We implement hover effects for buttons to improve interactivity and ensure seamless navigation with a dynamically positioned scrollbar.


MQL5 Trading Tools (Part 32): Crosshair, Magnifier, and Measure Mode
In this article, we extend the Tools Palette with a precision crosshair for MQL5 charts: reticle tick marks, full-width and full-height lines with axis labels, and a circular magnifier that renders zoomed candles. A double-click measure mode adds anchor markers, a diagonal connector, and a floating label with bars, pips, and price difference. Implementation details include a crosshair manager, eleven canvas layers, Bresenham line drawing, and theme-aware behavior that hides near the sidebar and fly out.

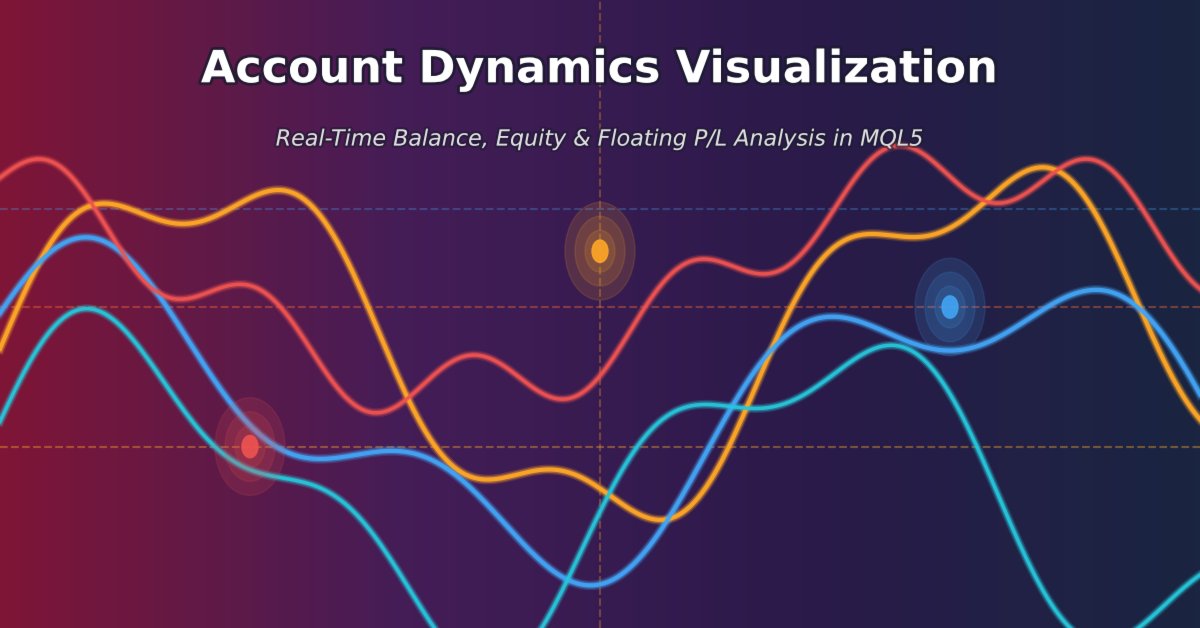
Tracking Account Dynamics: Balance, Equity, and Floating P/L Visualization in MQL5
Create a custom MT5 indicator that processes the entire deal history and plots starting balance, balance, equity, and floating P/L as continuous curves. It updates per bar, aggregates positions across symbols, and avoids external dependencies through local caching. Use it to inspect equity–balance divergence, realized vs. unrealized results, and the timing of risk deployment.


MQL5 Trading Tools (Part 11): Correlation Matrix Dashboard (Pearson, Spearman, Kendall) with Heatmap and Standard Modes
In this article, we build a correlation matrix dashboard in MQL5 to compute asset relationships using Pearson, Spearman, and Kendall methods over a set timeframe and bars. The system offers standard mode with color thresholds and p-value stars, plus heatmap mode with gradient visuals for correlation strengths. It includes an interactive UI with timeframe selectors, mode toggles, and a dynamic legend for efficient analysis of symbol interdependencies.


Turtle Shell Evolution Algorithm (TSEA)
This is a unique optimization algorithm inspired by the evolution of the turtle shell. The TSEA algorithm emulates the gradual formation of keratinized skin areas, which represent optimal solutions to a problem. The best solutions become "harder" and are located closer to the outer surface, while the less successful solutions remain "softer" and are located inside. The algorithm uses clustering of solutions by quality and distance, allowing to preserve less successful options and providing flexibility and adaptability.


Codex Pipelines, from Python to MQL5, for Indicator Selection: A Multi-Quarter Analysis of the XLF ETF with Machine Learning
We continue our look at how the selection of indicators can be pipelined when facing a ‘none-typical’ MetaTrader asset. MetaTrader 5 is primarily used to trade forex, and that is good given the liquidity on offer, however the case for trading outside of this ‘comfort-zone’, is growing bolder with not just the overnight rise of platforms like Robinhood, but also the relentless pursuit of an edge for most traders. We consider the XLF ETF for this article and also cap our revamped pipeline with a simple MLP.


Neural networks made easy (Part 68): Offline Preference-guided Policy Optimization
Since the first articles devoted to reinforcement learning, we have in one way or another touched upon 2 problems: exploring the environment and determining the reward function. Recent articles have been devoted to the problem of exploration in offline learning. In this article, I would like to introduce you to an algorithm whose authors completely eliminated the reward function.

Mastering Log Records (Part 1): Fundamental Concepts and First Steps in MQL5
Welcome to the beginning of another journey! This article opens a special series where we will create, step by step, a library for log manipulation, tailored for those who develop in the MQL5 language.


Risk-Based Trade Placement EA with On-Chart UI (Part 2): Adding Interactivity and Logic
Learn how to build an interactive MQL5 Expert Advisor with an on-chart control panel. Know how to compute risk-based lot sizes and place trades directly from the chart.


Building a Correlation-Aware Multi-EA Portfolio Scorer in MQL5
Most algo traders optimize Expert Advisors individually but never measure how they behave together on a single account. Correlated strategies amplify drawdowns instead of reducing them, and coverage gaps leave portfolios blind during entire trading sessions. This article builds a complete portfolio scorer in MQL5 that reads daily P&L from backtest CSV files, computes a full Pearson correlation matrix, maps trading activity by hour and weekday, evaluates asset class diversity, and outputs a composite grade from A+ to F. All source code is included; no external libraries are required.

Functions for activating neurons during training: The key to fast convergence?
This article presents a study of the interaction of different activation functions with optimization algorithms in the context of neural network training. Particular attention is paid to the comparison of the classical ADAM and its population version when working with a wide range of activation functions, including the oscillating ACON and Snake functions. Using a minimalistic MLP (1-1-1) architecture and a single training example, the influence of activation functions on the optimization is isolated from other factors. The article proposes an approach to manage network weights through the boundaries of activation functions and a weight reflection mechanism, which allows avoiding problems with saturation and stagnation in training.


MetaTrader 5 Machine Learning Blueprint (Part 12): Probability Calibration for Financial Machine Learning
Tree-based classifiers are typically overconfident: true win rates near 0.55 appear as 0.65–0.80 and inflate position sizes and Kelly fractions. This article presents afml.calibration and CalibratorCV, which generate out-of-fold predictions via PurgedKFold and fit isotonic regression or Platt scaling. We define Brier score, ECE, and MCE, and show diagnostics that trace miscalibration into position sizes, realized P&L, and CPCV path Sharpe distributions to support leakage-free, correctly sized trading.


Stress Testing Trade Sequences with Monte Carlo in MQL5
A backtest shows only one path among many possible outcomes. This MQL5 script performs 1000 bootstrap Monte Carlo resamples of a trade P&L series, draws a percentile fan chart on the chart via CCanvas, and reports probability of ruin, value at risk, and 95th‑percentile worst drawdown. The result is a practical view of path risk and drawdown exposure beyond a single equity curve.

Simultaneous Displaying of the Signals of Several Indicators from the Four Timeframes
While manual trading you have to keep an eye on the values of several indicators. It is a little bit different from mechanical trading. If you have two or three indicators and you have chosen a one timeframe for trading, it is not a complicated task. But what will you do if you have five or six indicators and your trading strategy requires considering the signals on the several timeframes?

Interview with Igor Korepin (ATC 2011)
Appearance of the Expert Advisor cs2011 by Igor Korepin (Xupypr) at the very top of the Automated Trading Championship 2011 was really impressive - its balance was almost twice that of the EA featured on the second place. However, despite such a sound breakaway, the Expert Advisor could not stay long on the first line. Igor frankly said that he relied much on a lucky start of his trading robot in the competition. We'll see if luck helps this simple EA to take the lead in the ATC 2011 race again.


Python-MetaTrader 5 Strategy Tester (Part 05): Multi-Symbols and Timeframes Strategy Tester
This article presents a MetaTrader 5–compatible backtesting workflow that scales across symbols and timeframes. We use HistoryManager to parallelize data collection, synchronize bars and ticks from all timeframes, and run symbol‑isolated OnTick handlers in threads. You will learn how modelling modes affect speed/accuracy, when to rely on terminal data, how to reduce I/O with event‑driven updates, and how to assemble a complete multicurrency trading robot.


Category Theory in MQL5 (Part 18): Naturality Square
This article continues our series into category theory by introducing natural transformations, a key pillar within the subject. We look at the seemingly complex definition, then delve into examples and applications with this series’ ‘bread and butter’; volatility forecasting.

Interview with Berron Parker (ATC 2010)
During the first week of the Championship Berron's Expert Advisor has been on the top position. He now tells us about his experience of EA development and difficulties of moving to MQL5. Berron says his EA is set up to work in a trend market, but can be weak in other market conditions. However, he is hopeful that his robot will show good results in this competition.

Price Action Analysis Toolkit Development (Part 8): Metrics Board
As one of the most powerful Price Action analysis toolkits, the Metrics Board is designed to streamline market analysis by instantly providing essential market metrics with just a click of a button. Each button serves a specific function, whether it’s analyzing high/low trends, volume, or other key indicators. This tool delivers accurate, real-time data when you need it most. Let’s dive deeper into its features in this article.


Design Patterns in software development and MQL5 (Part 2): Structural Patterns
In this article, we will continue our articles about Design Patterns after learning how much this topic is more important for us as developers to develop extendable, reliable applications not only by the MQL5 programming language but others as well. We will learn about another type of Design Patterns which is the structural one to learn how to design systems by using what we have as classes to form larger structures.

Across Neighbourhood Search (ANS)
The article reveals the potential of the ANS algorithm as an important step in the development of flexible and intelligent optimization methods that can take into account the specifics of the problem and the dynamics of the environment in the search space.


Neural Networks in Trading: Unified Trajectory Generation Model (UniTraj)
Understanding agent behavior is important in many different areas, but most methods focus on just one of the tasks (understanding, noise removal, or prediction), which reduces their effectiveness in real-world scenarios. In this article, we will get acquainted with a model that can adapt to solving various problems.

Idleness is the Stimulus to Progress. Semiautomatic Marking a Template
Among the dozens of examples of how to work with charts, there is a method of manual marking a template. Trend lines, channels, support/resistance levels, etc. are imposed in a chart. Surely, there are some special programs for this kind of work. Everyone decides on his/her own which method to use. In this article, I offer you for your consideration the methods of manual marking with subsequent automating some elements of the repeated routine actions.


Artificial Atom Algorithm (A3)
The article describes implementation of the A3 algorithm - a metaheuristic optimization method inspired by chemical processes - in MQL5. Only two adjustable parameters, compactness and a small population, ensure high operating speed with sufficient quality of solutions.


Neural Networks in Trading: Lightweight Models for Time Series Forecasting
Lightweight time series forecasting models achieve high performance using a minimum number of parameters. This, in turn, reduces the consumption of computing resources and speeds up decision-making. Despite being lightweight, such models achieve forecast quality comparable to more complex ones.

Archery Algorithm (AA)
The article takes a detailed look at the archery-inspired optimization algorithm, with an emphasis on using the roulette method as a mechanism for selecting promising areas for "arrows". The method allows evaluating the quality of solutions and selecting the most promising positions for further study.