MQL4 and MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

Price movement discretization methods in Python
We will look at price discretization methods using Python + MQL5. In this article, I will share my practical experience developing a Python library that implements a wide range of approaches to bar formation — from classic Volume and Range bars to more exotic methods like Renko and Kagi. We will consider three-line breakout candles and range bars analyzing their statistics and trying to define how else the prices can be represented discretely.

Neural Networks Made Easy (Part 92): Adaptive Forecasting in Frequency and Time Domains
The authors of the FreDF method experimentally confirmed the advantage of combined forecasting in the frequency and time domains. However, the use of the weight hyperparameter is not optimal for non-stationary time series. In this article, we will get acquainted with the method of adaptive combination of forecasts in frequency and time domains.


Fractal-Based Algorithm (FBA)
The article presents a new metaheuristic method based on a fractal approach to partitioning the search space for solving optimization problems. The algorithm sequentially identifies and separates promising areas, creating a self-similar fractal structure that concentrates computing resources on the most promising areas. A unique mutation mechanism aimed at better solutions ensures an optimal balance between exploration and exploitation of the search space, significantly increasing the efficiency of the algorithm.

Neural Networks in Trading: State Space Models
A large number of the models we have reviewed so far are based on the Transformer architecture. However, they may be inefficient when dealing with long sequences. And in this article, we will get acquainted with an alternative direction of time series forecasting based on state space models.


Implementation of the Augmented Dickey Fuller test in MQL5
In this article we demonstrate the implementation of the Augmented Dickey-Fuller test, and apply it to conduct cointegration tests using the Engle-Granger method.


Category Theory in MQL5 (Part 20): A detour to Self-Attention and the Transformer
We digress in our series by pondering at part of the algorithm to chatGPT. Are there any similarities or concepts borrowed from natural transformations? We attempt to answer these and other questions in a fun piece, with our code in a signal class format.


Price Action Analysis Toolkit Development (Part 59): Using Geometric Asymmetry to Identify Precision Breakouts from Fractal Consolidation
While studying a wide range of breakout setups, I noticed that failed breakouts were rarely caused by a lack of volatility, but more often by weak internal structure. That observation led to the framework presented in this article. The approach identifies patterns where the final price leg shows superior length, steepness, and speed—clear signs of momentum accumulation ahead of directional expansion. By detecting these subtle geometric imbalances within consolidation, traders can anticipate higher-probability breakouts before price exits the range. Continue reading to see how this fractal-based, geometric framework translates structural imbalance into precise breakout signals.


Angular Analysis of Price Movements: A Hybrid Model for Predicting Financial Markets
What is angular analysis of financial markets? How to use price action angles and machine learning to make accurate forecasts with 67% accuracy? How to combine a regression and classification model with angular features and obtain a working algorithm? What does Gann have to do with it? Why are price movement angles a good indicator for machine learning?

MetaTrader 5 Machine Learning Blueprint (Part 15): How to Calibrate Profit-Taking and Stop-Loss Targets from Synthetic Data
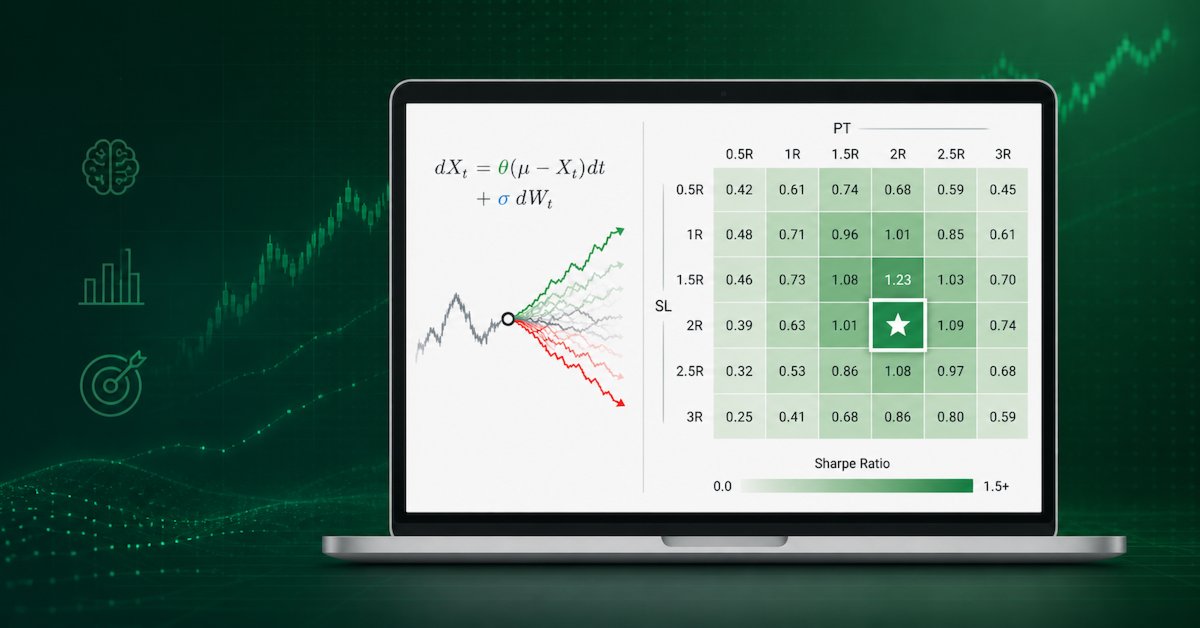
This article applies the Optimal Trading Rule from AFML Chapter 13 to set profit targets and stop-losses without in-sample calibration. We model post-entry P&L with a discrete Ornstein–Uhlenbeck process, run a 100,000-path search, and implement Python, multiprocessing, and a Numba @njit parallel kernel (242× faster). The result is an optimal (PT, SL) under three forecast specifications, constrained by the prop-firm daily loss limit.


Neural Networks Made Easy (Part 84): Reversible Normalization (RevIN)
We already know that pre-processing of the input data plays a major role in the stability of model training. To process "raw" input data online, we often use a batch normalization layer. But sometimes we need a reverse procedure. In this article, we discuss one of the possible approaches to solving this problem.


Vladimir Tsyrulnik: The Essense of my program is improvisation! (ATC 2010)
Vladimir Tsyrulnik is the holder of one of the brightest highs of the current Championship. By the end of the third trading week Vladimir's Expert Advisor was on the sixth position. The IMEX algorithm the Expert Advisor is based on was developed by Vladimir. To learn more about this algorithm, we had an interview with Vladimir.

Creating a Trading Administrator Panel in MQL5 (Part VIII): Analytics Panel
Today, we delve into incorporating useful trading metrics within a specialized window integrated into the Admin Panel EA. This discussion focuses on the implementation of MQL5 to develop an Analytics Panel and highlights the value of the data it provides to trading administrators. The impact is largely educational, as valuable lessons are drawn from the development process, benefiting both upcoming and experienced developers. This feature demonstrates the limitless opportunities this development series offers in equipping trade managers with advanced software tools. Additionally, we'll explore the implementation of the PieChart and ChartCanvas classes as part of the continued expansion of the Trading Administrator panel’s capabilities.


Data label for time series mining (Part 6):Apply and Test in EA Using ONNX
This series of articles introduces several time series labeling methods, which can create data that meets most artificial intelligence models, and targeted data labeling according to needs can make the trained artificial intelligence model more in line with the expected design, improve the accuracy of our model, and even help the model make a qualitative leap!

DoEasy. Controls (Part 27): Working on ProgressBar WinForms object
In this article, I will continue the development of the ProgressBar control. In particular, I will create the functionality for managing the progress bar and visual effects.


Population optimization algorithms: Saplings Sowing and Growing up (SSG)
Saplings Sowing and Growing up (SSG) algorithm is inspired by one of the most resilient organisms on the planet demonstrating outstanding capability for survival in a wide variety of conditions.

Quantization in machine learning (Part 1): Theory, sample code, analysis of implementation in CatBoost
The article considers the theoretical application of quantization in the construction of tree models and showcases the implemented quantization methods in CatBoost. No complex mathematical equations are used.

Interview with Tim Fass (ATC 2011)
A student from Germany Tim Fass (Tim) is participating in the Automated Trading Championship for the first time. Nevertheless, his Expert Advisor The_Wild_13 already got featured at the very top of the Championship rating and seems to be holding his position in the top ten. Tim told us about his Expert Advisor, his faith in the success of simple strategies and his wildest dreams.


Visualizing deals on a chart (Part 2): Data graphical display
Here we are going to develop a script from scratch that simplifies unloading print screens of deals for analyzing trading entries. All the necessary information on a single deal is to be conveniently displayed on one chart with the ability to draw different timeframes.


Implementing the Truncated Newton Conjugate-Gradient Algorithm in MQL5
This article implements a box‑constrained Truncated Newton Conjugate‑Gradient (TNC) optimizer in MQL5 and details its core components: scaling, projection to bounds, line search, and Hessian‑vector products via finite differences. It provides an objective wrapper supporting analytic or numerical derivatives and validates the solver on the Rosenbrock benchmark. A logistic regression example shows how to use TNC as a drop‑in alternative to LBFGS.


Where should your stop-loss really sit? An MAE/MFE excursion analyzer in MQL5
Stop-loss and take-profit placement is usually the least-measured decision in a trading system. This Expert Advisor reads your closed history, replays M1 price between each entry and exit to measure Maximum Adverse and Favorable Excursion per trade, and splits winners from losers. From the distributions and trade efficiency it derives data-driven stop and target levels - measured from your own account, not a rule of thumb. Analysis only; it does not trade.

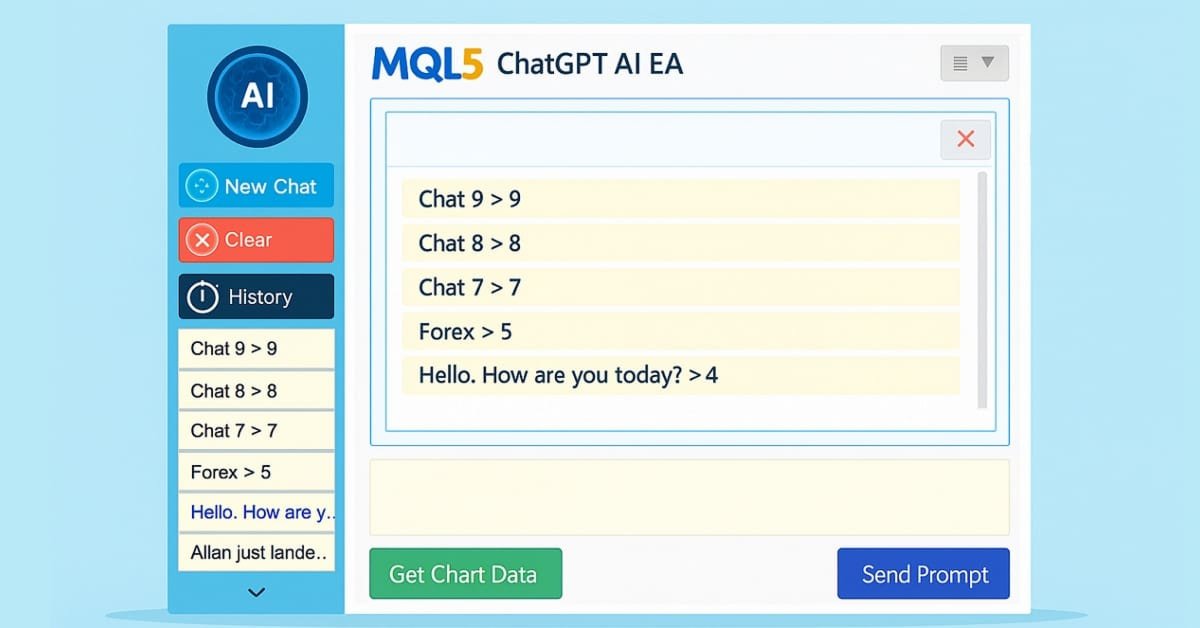
Building AI-Powered Trading Systems in MQL5 (Part 5): Adding a Collapsible Sidebar with Chat Popups
In Part 5 of our MQL5 AI trading system series, we enhance the ChatGPT-integrated Expert Advisor by introducing a collapsible sidebar, improving navigation with small and large history popups for seamless chat selection, while maintaining multiline input handling, persistent encrypted chat storage, and AI-driven trade signal generation from chart data.


Developing a trading Expert Advisor from scratch (Part 26): Towards the future (I)
Today we will take our order system to the next level. But before that, we need to solve a few problems. Now we have some questions that are related to how we want to work and what things we do during the trading day.


Statistical Arbitrage Through Cointegrated Stocks (Part 2): Expert Advisor, Backtests, and Optimization
This article presents a sample Expert Advisor implementation for trading a basket of four Nasdaq stocks. The stocks were initially filtered based on Pearson correlation tests. The filtered group was then tested for cointegration with Johansen tests. Finally, the cointegrated spread was tested for stationarity with the ADF and KPSS tests. Here we will see some notes about this process and the results of the backtests after a small optimization.


Price Action Analysis Toolkit Development (Part 69): Flag Pattern Detection in MQL5
This article shows how to convert subjective flag recognition into reproducible MQL5 logic for live charts. It combines ATR-normalized pole strength, retracement limits, consolidation structure checks, breakout confirmation, and overlap control. Readers gain a workable approach that renders adaptive channels and zones, updates active setups efficiently, and provides optional alerts for newly confirmed patterns.

Population optimization algorithms: Binary Genetic Algorithm (BGA). Part II
In this article, we will look at the binary genetic algorithm (BGA), which models the natural processes that occur in the genetic material of living things in nature.

Black Hole Algorithm (BHA)
The Black Hole Algorithm (BHA) uses the principles of black hole gravity to optimize solutions. In this article, we will look at how BHA attracts the best solutions while avoiding local extremes, and why this algorithm has become a powerful tool for solving complex problems. Learn how simple ideas can lead to impressive results in the world of optimization.


Neural Networks in Trading: Multi-Task Learning Based on the ResNeXt Model
A multi-task learning framework based on ResNeXt optimizes the analysis of financial data, taking into account its high dimensionality, nonlinearity, and time dependencies. The use of group convolution and specialized heads allows the model to effectively extract key features from the input data.


Position Management: Safe Pyramiding with a Unified Stop in MQL5
This article presents CPyramidEngine, a reusable MQL5 class that adds disciplined pyramiding to any Expert Advisor with about six lines of integration. The engine enforces three constraints: strictly decreasing lot sizes, a single unified stop that advances after each add-on, and broker-level validation of every modification. It explains common failure modes in naive implementations and shows how to keep total account risk quantifiable and controlled as positions are added.


Integrating Computer Vision into Trading in MQL5 (Part 1): Creating Basic Functions
The EURUSD forecasting system with the use of computer vision and deep learning. Learn how convolutional neural networks can recognize complex price patterns in the foreign exchange market and predict exchange rate movements with up to 54% accuracy. The article shares the methodology for creating an algorithm that uses artificial intelligence technologies for visual analysis of charts instead of traditional technical indicators. The author demonstrates the process of transforming price data into "images", their processing by a neural network, and a unique opportunity to peer into the "consciousness" of AI through activation maps and attention heatmaps. Practical Python code using the MetaTrader 5 library allows readers to reproduce the system and apply it in their own trading.

Data Science and ML (Part 32): Keeping your AI models updated, Online Learning
In the ever-changing world of trading, adapting to market shifts is not just a choice—it's a necessity. New patterns and trends emerge everyday, making it harder even the most advanced machine learning models to stay effective in the face of evolving conditions. In this article, we’ll explore how to keep your models relevant and responsive to new market data by automatically retraining.

Category Theory in MQL5 (Part 2)
Category Theory is a diverse and expanding branch of Mathematics which as of yet is relatively uncovered in the MQL5 community. These series of articles look to introduce and examine some of its concepts with the overall goal of establishing an open library that attracts comments and discussion while hopefully furthering the use of this remarkable field in Traders' strategy development.


Low-Frequency Quantitative Strategies in MetaTrader 5 (Part 4): A Volatility-Adjusted Momentum-Based Intraday System
We present a timer-based MQL5 EA for Opening Range Breakout aligned to NYSE hours. It screens “Stocks in Play” via opening-range relative volume, enforces price/volume/ATR minimums, sizes positions by risk, and exits at 16:00 ET. A Sharpe-ranked optimization across 30 liquid Nasdaq stocks and a single-symbol test are provided, together with backtest settings and an Excel report for verification.


Neural Networks in Trading: Two-Dimensional Connection Space Models (Final Part)
We continue to explore the innovative Chimera framework – a two-dimensional state-space model that uses neural network technologies to analyze multidimensional time series. This method provides high forecasting accuracy with low computational cost.

Neural networks made easy (Part 34): Fully Parameterized Quantile Function
We continue studying distributed Q-learning algorithms. In previous articles, we have considered distributed and quantile Q-learning algorithms. In the first algorithm, we trained the probabilities of given ranges of values. In the second algorithm, we trained ranges with a given probability. In both of them, we used a priori knowledge of one distribution and trained another one. In this article, we will consider an algorithm which allows the model to train for both distributions.


DoEasy. Controls (Part 28): Bar styles in the ProgressBar control
In this article, I will develop display styles and description text for the progress bar of the ProgressBar control.


Neural Networks in Trading: Disentangling Structured Components (Encoder)
We invite you to explore the next stage in implementing the SCNN framework, which combines flexibility and interpretability, allowing structural components of a time series to be identified precisely. The article provides a detailed explanation of the mechanisms of adaptive normalization and attention, which ensure the model's resilience to changing market conditions.

Atomic Orbital Search (AOS) algorithm: Modification
In the second part of the article, we will continue developing a modified version of the AOS (Atomic Orbital Search) algorithm focusing on specific operators to improve its efficiency and adaptability. After analyzing the fundamentals and mechanics of the algorithm, we will discuss ideas for improving its performance and the ability to analyze complex solution spaces, proposing new approaches to extend its functionality as an optimization tool.


Neural Networks in Trading: Memory Augmented Context-Aware Learning (MacroHFT) for Cryptocurrency Markets
I invite you to explore the MacroHFT framework, which applies context-aware reinforcement learning and memory to improve high-frequency cryptocurrency trading decisions using macroeconomic data and adaptive agents.


Chaos theory in trading (Part 2): Diving deeper
We continue our dive into chaos theory in financial markets. This time I will consider its applicability to the analysis of currencies and other assets.

DoEasy. Service functions (Part 1): Price patterns
In this article, we will start developing methods for searching for price patterns using timeseries data. A pattern has a certain set of parameters, common to any type of patterns. All data of this kind will be concentrated in the object class of the base abstract pattern. In the current article, we will create an abstract pattern class and a Pin Bar pattern class.