Articles on MetaTrader 5 integration using MQL5

Traders meet interesting challenges which often require an innovative approach. This category features articles that offer the most unexpected solutions for evaluating, analyzing and processing price data and trading results. The articles describe various integration solutions, including connection of databases and ICQ, use of OpenCL and social networks, use of Delphi and C#.
Read on to learn how to use specialized mathematical and neural packages, and much more. Become an author and share unique ideas with the MQL5.community members.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

Client in Connexus (Part 7): Adding the Client Layer
In this article we continue the development of the connexus library. In this chapter we build the CHttpClient class responsible for sending a request and receiving an order. We also cover the concept of mocks, leaving the library decoupled from the WebRequest function, which allows greater flexibility for users.


Trust Your Backtest Data First: Building a Reproducible Historical Data Audit in Python for MetaTrader 5
A reproducible, read-only Python audit for MetaTrader 5 that verifies history quality before any backtest. It exports M5 data from multiple terminals, detects gaps and synthetic bars by timestamp spacing, and reports coverage per year. The same deterministic strategy then runs on three broker feeds over a common window to quantify result drift and decompose it into spread, data/price, and trade effects.


File-Based Versioning of EA Parameters in MQL5
This article explains how to implement parameter versioning in MQL5 using binary files and packed structures. It shows how to write and read fixed-size records with FileWriteStruct and FileReadStruct in FILE_BIN mode, including version numbers, timestamps, and a checksum. You will also see how to detect changes via checksums, append records safely, and load the latest configuration without overwriting prior settings.


Community of Scientists Optimization (CoSO): Theory
Secrets of effective optimization of trading strategies in metaheuristic approaches. Community of Scientists Optimization is a new population-based algorithm inspired by the mechanisms of the scientific community. Unlike traditional nature-inspired metaphors, CoSO models unique aspects of human scientific activity: publishing results in journals, competing for grants, and forming research teams.


From Novice to Expert: Animated News Headline Using MQL5 (V)—Event Reminder System
In this discussion, we’ll explore additional advancements as we integrate refined event‑alerting logic for the economic calendar events displayed by the News Headline EA. This enhancement is critical—it ensures users receive timely notifications a short time before key upcoming events. Join this discussion to discover more.


Market Simulation: Position View (V)
Despite what was shown in the previous article, all of this may seem simple at first. In reality, several problems remain, along with many tasks that still need to be completed. You, dear reader, may imagine that everything is easy and straightforward. Out of inexperience, you may simply accept whatever is presented to you. And that is a mistake you should try to avoid. Even worse is trying to use something without truly understanding what exactly you are using. Beginners often pass through a copy-and-paste stage. If you do not want to remain stuck at that stage forever, you should learn how to use certain tools. One of the tools most often used by programmers is documentation. The second is testing, supported by log files. Here we will see how to do this.


Quantum Computing and Gradient Boosting in EURUSD Trading
The article describes the practical implementation of a hybrid algorithmic trading system that combines quantum computing (IBM Qiskit) and gradient boosting (CatBoost) to predict movements in the EURUSD pair on the hourly time frame. The system extracts four unique quantum features from a probability distribution across 256 states using eight qubits and, in combination with classical indicators and delta encoding of time categories, achieves 62% accuracy on 15,000 candlesticks.


Interactive Supply and Demand Zone Manager in MQL5 (Part III): Zone Analysis, Stateful Interaction, and Pending Event Management
We extend the stateful supply and demand framework for MetaTrader 5 with a quantitative admission model and a dedicated interaction engine. Candidate zones are scored by structural symmetry, volume participation, and ATR‑normalized displacement, then classified into objective tiers. Admitted zones follow a deterministic lifecycle that tracks first touch, validates bounces, or confirms breakouts, with full telemetry for analysis and reproducibility.


Symbolic Price Forecasting Equation Using SymPy
The article describes an interesting approach to algorithmic trading based on symbolic mathematical equations instead of traditional machine learning "black boxes". The author demonstrates how to transform opaque neural networks into readable mathematical equations using the SymPy library and polynomial regression, allowing for a full understanding of the logic behind trading decisions. The approach combines the computational power of ML with the transparency of classical methods, giving traders the ability to analyze, adjust, and adapt models in real time.

MQL5 Trading Toolkit (Part 6): Expanding the History Management EX5 Library with the Last Filled Pending Order Functions
Learn how to create an EX5 module of exportable functions that seamlessly query and save data for the most recently filled pending order. In this comprehensive step-by-step guide, we will enhance the History Management EX5 library by developing dedicated and compartmentalized functions to retrieve essential properties of the last filled pending order. These properties include the order type, setup time, execution time, filling type, and other critical details necessary for effective pending orders trade history management and analysis.


Building Volatility Models in MQL5 (Part III): Implementing the SLSQP Algorithm for Model Estimation
An SLSQP optimizer is implemented in MQL5 to resolve parameter discrepancies between a volatility library and Python's ARCH module. The article details constraint handling, gradient options, configuration, and convergence controls and shows how to integrate the solver into existing code. Practical examples and comparisons demonstrate matched log‑likelihoods and parameters on shared datasets.


Biogeography-Based Optimization (BBO)
Biogeography-Based Optimization (BBO) is an elegant global optimization method inspired by natural processes of species migration between islands within archipelagos. The algorithm is based on a simple yet powerful idea: high-quality solutions actively share their characteristics, while low-quality ones actively adopt new features, creating a natural flow of information from the best solutions to the worst. A unique adaptive mutation operator provides an excellent balance between exploration and exploitation. BBO demonstrates high efficiency on a variety of tasks.


Community of Scientists Optimization (CoSO): Practice
We resume the topic of optimization by the scientific community. CoSO should not be viewed as a ready-made solution, but as a promising research platform. With proper development, CoSO can find its niche in tasks where adaptability and resilience to change are important, and computation time is not critical.


Introduction to MQL5 (Part 38): Mastering API and WebRequest Function in MQL5 (XII)
Create a practical bridge between MetaTrader 5 and Binance: fetch 30‑minute klines with WebRequest, extract OHLC/time values from JSON, and confirm a bullish engulfing pattern using only completed candles. Then assemble the query string, compute the HMAC‑SHA256 signature, add X‑MBX‑APIKEY, and submit authenticated orders. You get a clear, end‑to‑end EA workflow from data acquisition to order execution.


Developing a Multi-Currency Expert Advisor (Part 28): Adding a Position Closing Manager
When running multiple strategies in parallel, you may want to periodically close all open positions and start the strategies over again. The existing code only allows this behavior to be implemented through manual intervention. Let's try to automate this part.


Graph Theory: Traversal Breadth-First Search (BFS) Applied in Trading
Breadth First Search (BFS) uses level-order traversal to model market structure as a directed graph of price swings evolving through time. By analyzing historical bars or sessions layer by layer, BFS prioritizes recent price behavior while still respecting deeper market memory.


Market Simulation (Part 12): Sockets (VI)
In this article, we will look at how to solve certain problems and issues that arise when using Python code within other programs. More specifically, we will demonstrate a common issue encountered when using Excel in conjunction with MetaTrader 5, although we will be using Python to facilitate this interaction. However, this implementation has a minor drawback. It does not occur in all cases, but only in certain specific situations. When it does happen, it is necessary to understand the cause. In today’s article, we will begin explaining how to resolve this issue.

Custom Debugging and Profiling Tools for MQL5 Development (Part II): Profiling EAs and Testing Trading Logic
We build a compact profiler that records calls, min/max/average times, and slow-call counts to CSV, and a simple test runner that writes deterministic pass/fail reports. The article explains where to place measurements in an EA, how to sample ticks, and how to keep pure calculations testable. Running the script first and the profiling EA second provides repeatable evidence for regression analysis.


Adaptive Social Behavior Optimization (ASBO): Two-phase evolution
We continue dwelling on the topic of social behavior of living organisms and its impact on the development of a new mathematical model - ASBO (Adaptive Social Behavior Optimization). We will dive into the two-phase evolution, test the algorithm and draw conclusions. Just as in nature a group of living organisms join their efforts to survive, ASBO uses principles of collective behavior to solve complex optimization problems.


Modular Indicator Architecture in MQL5 (Part 1): Stop Copy-Pasting and Start Writing Scalable, Reusable Code
This article develops an object-oriented framework for MQL5 indicators by evolving a primitive example into reusable modules. It formalizes partial buffer recalculation in OnCalculate, moves logic into header-based classes (CAppliedPrice, CSma), and introduces CSubIndiBase, CIndicatorBase, and a registry to centralize requirements. You get portable components, isolated inputs, and clean buffers with minimal boilerplate, making new indicators faster to assemble and easier to maintain.


Exploring Regression Models for Causal Inference and Trading
The article explores the possibility of using regression models in algorithmic trading. Regression models, unlike binary classification, allow for the creation of more flexible trading strategies by quantifying predicted price changes.


Training Neural Networks on Oscillators Without Look-Ahead Bias
The article describes an approach to trade labeling using oscillators for machine learning models. This eliminates look-ahead bias. It has been shown that this type of labeling does not lead to model overfitting, and the strategies continue to perform well over the long term.


Determining Fair Exchange Rates Using PPP and IMF Data
Building a purchasing power parity (PPP)-based exchange rate analysis system using Python. The author developed an algorithm with 5 methods for calculating fair exchange rates using IMF data. A practical guide to fundamental currency analysis, economic data processing, and integration with trading systems. Full code in open source.


The case for using Hospital-Performance Data with Perceptrons, this Q4, in weighing SPDR XLV's next Performance
XLV is SPDR healthcare ETF and in an age where it is common to be bombarded by a wide array of traditional news items plus social media feeds, it can be pressing to select a data set for use with a model. We try to tackle this problem for this ETF by sizing up some of its critical data sets in MQL5.


Dingo Optimization Algorithm (DOA)
The article presents a new metaheuristic method based on the hunting strategies of Australian dingoes: group attack, chase, and scavenging. Let's see how the Dingo Optimization Algorithm (DOA) performs algorithmically.


Beyond GARCH (Part II): Measuring the Fractal Dimension of Markets
Building on the partition function analysis from Part 1, this article deepens the theoretical foundation before completing the analytical pipeline. We first give a full treatment of the Hurst exponent: what it measures, what it implies about market memory, and why it matters for the MMAR. This is followed by an intuitive exploration of multifractal spectra and what f(α) reveals about volatility heterogeneity. We then move to implementation: extracting the scaling function τ(q), estimating H via R/S analysis, and fitting the multifractal spectrum across four candidate distributions. By the end, we have the complete parameter set needed to construct the MMAR process in Part 3. Part 2 of an eight-part series.


Market Simulation (Part 24): Getting Started with SQL (VII)
In the previous article, we completed the necessary introduction to SQL. And, in my opinion, we properly clarified what we wanted to show and explain about SQL. This was done so that anyone who comes to look at the market replay/simulation system being built can at least get an idea of what may be happening there. The point is that there is no sense in programming things that SQL handles perfectly.


Beyond GARCH (Part I): Mandelbrot's MMAR versus Engle's GARCH
This article starts the MMAR pipeline on EURUSD M5 data. We load market data via the MetaTrader5 Python API and run partition-function analysis with non-overlapping intervals to test for multifractal scaling. The result is an evidence-based decision on fractality, a prerequisite for building MMAR and for choosing whether to proceed beyond GARCH.

Developing an MQTT client for Metatrader 5: a TDD approach — Part 5
This article is the fifth part of a series describing our development steps of a native MQL5 client for the MQTT 5.0 protocol. In this part we describe the structure of PUBLISH packets, how we are setting their Publish Flags, encoding Topic Name(s) strings, and setting Packet Identifier(s) when required.


Market Simulation (Part 22): Getting Started with SQL (V)
Before you give up and decide to abandon learning SQL, allow me to remind you, dear readers, that here we are still using only the most basic elements. We have not yet looked at some of SQL's capabilities. Once you understand them, you will see that SQL is far more practical than it seems. Although, most likely, we will eventually change the direction of what we are building, because the creation process is dynamic. We will show a little more about creating different things in SQL, because this is truly important and useful for you. Simply thinking that you are more capable than an entire community of programmers and developers will only lead to wasted time and opportunities. Do not worry, because what comes next will be even more interesting.


Developing a Terminal Manager (Part 3): Getting Account Information and Adding Configuration
We are adding to our web application the ability to retrieve and display information about the terminal instances’ trading accounts, including balance, profit, connection status, and other important details. We will also implement a flexible configuration system that lets you manage application settings via an external JSON file, and improve the user interface of the main page.

MQL5 Trading Toolkit (Part 7): Expanding the History Management EX5 Library with the Last Canceled Pending Order Functions
Learn how to complete the creation of the final module in the History Manager EX5 library, focusing on the functions responsible for handling the most recently canceled pending order. This will provide you with the tools to efficiently retrieve and store key details related to canceled pending orders with MQL5.


Market Simulation (Part 24): Position View (II)
In this article, I will show how to use an indicator to track open positions on the trading server in the simplest and most practical way possible. I am doing this step by step to show that you do not necessarily have to move all of this into an Expert Advisor. Many of you have probably become used to doing that for one reason or another. In fact, that is not really justified, because as this implementation evolves, it will become clear that you can create or implement different types of indicators for this purpose.


Bison Algorithm (BIA)
A new optimization method, the Bison Algorithm (BIA), uses two strategies, inspired by the behavior of bison, for solving continuous problems with a single objective function. The key features of BIA are two fundamental principles borrowed from the behavior of bison: the ability to move dynamically and a defensive strategy.


Exchange Market Algorithm (EMA)
The article presents a detailed analysis of the Exchange Market Algorithm (EMA) inspired by the behavior of stock market traders. The algorithm simulates stock trading, where market participants with varying levels of success employ different strategies to maximize profits.

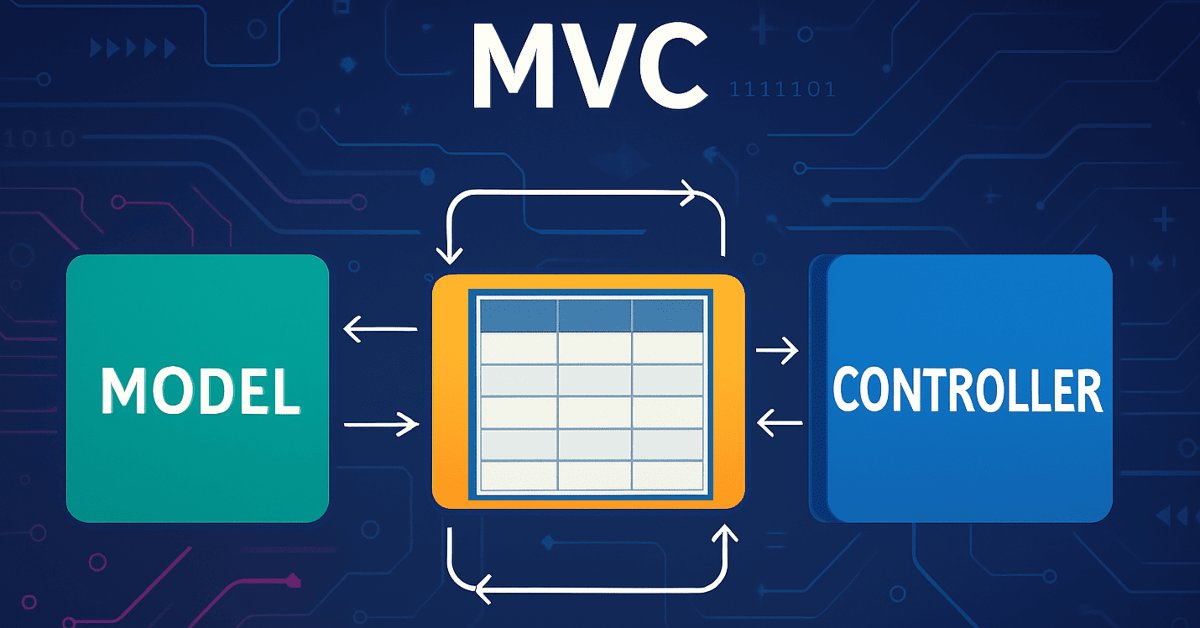
Implementation of a table model in MQL5: Applying the MVC concept
In this article, we look at the process of developing a table model in MQL5 using the MVC (Model-View-Controller) architectural pattern to separate data logic, presentation, and control, enabling structured, flexible, and scalable code. We consider implementation of classes for building a table model, including the use of linked lists for storing data.

Population optimization algorithms: Resistance to getting stuck in local extrema (Part I)
This article presents a unique experiment that aims to examine the behavior of population optimization algorithms in the context of their ability to efficiently escape local minima when population diversity is low and reach global maxima. Working in this direction will provide further insight into which specific algorithms can successfully continue their search using coordinates set by the user as a starting point, and what factors influence their success.

Header in the Connexus (Part 3): Mastering the Use of HTTP Headers for Requests
We continue developing the Connexus library. In this chapter, we explore the concept of headers in the HTTP protocol, explaining what they are, what they are for, and how to use them in requests. We cover the main headers used in communications with APIs, and show practical examples of how to configure them in the library.


Trading with the MQL5 Economic Calendar (Part 11): Modular Canvas News Dashboard
We rebuild the MQL5 Economic Calendar dashboard from a monolithic object-based panel into a modular canvas-based system split across four files. The update adds a dual light and dark theme, collapsible day groups, a resizable layout with pixel-based scrolling, revised value markers, and a live countdown with toast notifications. A candidate event cache and a fast-path timer that repaints only changed cells improve responsiveness and make the codebase easier to extend.


Duelist Algorithm
What if your trading strategies could learn from each other, like real fighters? Duelist Algorithm is a new optimization method where trading system parameters literally duel for the right to be called the best.