MQL4 and MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Forecasting a Conditional Distribution Using MLP
In this article, we will consider an MLP-based regression model that predicts not only the conditional expectation but also the conditional variance. In other words, we will train our network to predict the entire distribution of future prices based on the input feature vector. But for this purpose we will have to implement our own loss function.


Building a Future Swing Projection Indicator in MQL5
We implement a Future Swing Projection indicator in MQL5 that analyzes historical swing structure and estimates the next move from recent price behavior. It locates six alternating swing points, measures five completed legs, and uses their average distance to project a target five bars ahead. The indicator draws swing legs, a projection line, ATR‑based support and resistance zones, and a label with the projected price to keep the process rule‑based and reproducible.


From Novice to Expert: Animated News Headline Using MQL5 (V)—Event Reminder System
In this discussion, we’ll explore additional advancements as we integrate refined event‑alerting logic for the economic calendar events displayed by the News Headline EA. This enhancement is critical—it ensures users receive timely notifications a short time before key upcoming events. Join this discussion to discover more.


Engineering a Self-Healing Expert Advisor in MQL5 (Part 5): Real-Time Recovery Dashboard (Final Part)
This article implements a real-time monitoring dashboard for a self-healing MetaTrader 5 Expert Advisor. The dashboard displays the current EA state, virtual stop-loss and take-profit levels, breakeven and trailing status, recovery state, synchronization status, and heartbeat information directly on the chart. By exposing the internal recovery state visually, the Expert Advisor becomes easier to monitor, verify, and troubleshoot while managing active trades.


Developing a Terminal Manager (Part 3): Getting Account Information and Adding Configuration
We are adding to our web application the ability to retrieve and display information about the terminal instances’ trading accounts, including balance, profit, connection status, and other important details. We will also implement a flexible configuration system that lets you manage application settings via an external JSON file, and improve the user interface of the main page.


MQL5 Trading Tools (Part 38): Adding a Tabbed Settings Window for Editing Object Properties
We add a tabbed settings window opened from the ribbon and bound to the selected object. The tabs — Style, Text, Coordinates, and Visibility — are built from the same descriptor system, with scrolling, per-level rows, and shared color/width/style popovers. The article covers layout, rendering, interaction, and inline price/time and numeric editing. You get one place to edit every property with live preview and commit-or-discard on close.


Neural Networks in Trading: A Spiking-Semantic Approach to Spatiotemporal Identification (Key Components)
In this article, we took a detailed look at the integration of the SSAM module into the SEW-ResNeXt block, demonstrating how the S3CE-Net framework enables the effective combination of spiking attention with residual blocks. This architecture ensures accurate processing of temporal and spatial data streams and high training stability. The modularity and flexibility of the components make it easier to extend the model and reuse proven methods.


Market Simulation: Position View (V)
Despite what was shown in the previous article, all of this may seem simple at first. In reality, several problems remain, along with many tasks that still need to be completed. You, dear reader, may imagine that everything is easy and straightforward. Out of inexperience, you may simply accept whatever is presented to you. And that is a mistake you should try to avoid. Even worse is trying to use something without truly understanding what exactly you are using. Beginners often pass through a copy-and-paste stage. If you do not want to remain stuck at that stage forever, you should learn how to use certain tools. One of the tools most often used by programmers is documentation. The second is testing, supported by log files. Here we will see how to do this.


Building Volatility Models in MQL5 (Part III): Implementing the SLSQP Algorithm for Model Estimation
An SLSQP optimizer is implemented in MQL5 to resolve parameter discrepancies between a volatility library and Python's ARCH module. The article details constraint handling, gradient options, configuration, and convergence controls and shows how to integrate the solver into existing code. Practical examples and comparisons demonstrate matched log‑likelihoods and parameters on shared datasets.

MQL5 Wizard Techniques you should know (Part 23): CNNs
Convolutional Neural Networks are another machine learning algorithm that tend to specialize in decomposing multi-dimensioned data sets into key constituent parts. We look at how this is typically achieved and explore a possible application for traders in another MQL5 wizard signal class.

Neural networks made easy (Part 77): Cross-Covariance Transformer (XCiT)
In our models, we often use various attention algorithms. And, probably, most often we use Transformers. Their main disadvantage is the resource requirement. In this article, we will consider a new algorithm that can help reduce computing costs without losing quality.


Training Neural Networks on Oscillators Without Look-Ahead Bias
The article describes an approach to trade labeling using oscillators for machine learning models. This eliminates look-ahead bias. It has been shown that this type of labeling does not lead to model overfitting, and the strategies continue to perform well over the long term.


Neural networks made easy (Part 70): Closed-Form Policy Improvement Operators (CFPI)
In this article, we will get acquainted with an algorithm that uses closed-form policy improvement operators to optimize Agent actions in offline mode.


Atmosphere Clouds Model Optimization (ACMO): Theory
The article is devoted to the metaheuristic Atmosphere Clouds Model Optimization (ACMO) algorithm, which simulates the behavior of clouds to solve optimization problems. The algorithm uses the principles of cloud generation, movement and propagation, adapting to the "weather conditions" in the solution space. The article reveals how the algorithm's meteorological simulation finds optimal solutions in a complex possibility space and describes in detail the stages of ACMO operation, including "sky" preparation, cloud birth, cloud movement, and rain concentration.


Symbolic Price Forecasting Equation Using SymPy
The article describes an interesting approach to algorithmic trading based on symbolic mathematical equations instead of traditional machine learning "black boxes". The author demonstrates how to transform opaque neural networks into readable mathematical equations using the SymPy library and polynomial regression, allowing for a full understanding of the logic behind trading decisions. The approach combines the computational power of ML with the transparency of classical methods, giving traders the ability to analyze, adjust, and adapt models in real time.


MQL5 Trading Tools (Part 27): Rendering Parametric Butterfly Curve on Canvas
In this article, we explore the butterfly curve, a parametric mathematical equation, and render it visually on a MQL5 canvas. We build an interactive display with a draggable, resizable canvas window, supersampled curve rendering, gradient backgrounds, and a color-segmented legend. By the end, we have a fully functional visual tool that plots the butterfly curve directly on the MetaTrader 5 chart.

Client in Connexus (Part 7): Adding the Client Layer
In this article we continue the development of the connexus library. In this chapter we build the CHttpClient class responsible for sending a request and receiving an order. We also cover the concept of mocks, leaving the library decoupled from the WebRequest function, which allows greater flexibility for users.


Developing a Multi-Currency Expert Advisor (Part 28): Adding a Position Closing Manager
When running multiple strategies in parallel, you may want to periodically close all open positions and start the strategies over again. The existing code only allows this behavior to be implemented through manual intervention. Let's try to automate this part.


Market Microstructure in MQL5 (Part 2): Measuring long memory in MQL5 with Hurst estimators
Part 2 focuses on practical long-memory detection for intraday data. Three complementary Hurst estimators are implemented and combined into a confidence‑weighted composite, with confidence tied to valid regression scales. The final H and confidence populate the shared analysis struct, enabling indicators to act only when H departs from the neutral 0.40–0.60 band and to select trend‑following above 0.60 or mean‑reversion below 0.40.


Bivariate Copulae in MQL5 (Part 3): Implementation and Tuning of Mixed Copula Models in MQL5
The article extends our copula toolkit with mixed copulas implemented natively in MQL5. We construct Clayton–Frank–Gumbel and Clayton–Student–t–Gumbel mixtures, estimate them via EM, and enable sparsity control through SCAD with cross‑validation. Provided scripts tune hyperparameters, compare mixtures using information criteria, and save trained models. Practitioners can apply these components to capture asymmetric tail dependence and embed the selected model in indicators or Expert Advisors.


Introduction to MQL5 (Part 41): Beginner Guide to File Handling in MQL5 (III)
Learn how to read a CSV file in MQL5 and organize its trading data into dynamic arrays. This article shows step by step how to count file elements, store all data in a single array, and separate each column into dedicated arrays, laying the foundation for advanced analysis and trading performance visualization.


Feature Engineering for ML (Part 7): Entropy Features in Python
The article provides production-ready entropy estimators (Shannon, plug-in, Lempel–Ziv, Kontoyiannis) operating on tick-rule–encoded sequences. It resolves three correctness and performance issues in the original code, verifies outputs against chapter references, and extends encoding with quantile and sigma options. Users gain reproducible results and markedly improved computation speed for large bar sets.


Self Optimizing Expert Advisors in MQL5 (Part 14): Viewing Data Transformations as Tuning Parameters of Our Feedback Controller
Preprocessing is a powerful yet quickly overlooked tuning parameter. It lives in the shadows of its bigger brothers: optimizers and shiny model architectures. Small percentage improvements here can have disproportionately large, compounding effects on profitability and risk. Too often, this largely unexplored science is boiled down to a simple routine, seen only as a means to an end, when in reality it is where signal can be directly amplified, or just as easily destroyed.


Quantum Neural Network in MQL5 (Part II): Training a Neural Network with Backpropagation on ALGLIB Markov Matrices
The article presents an innovative quantum neural network architecture for algorithmic trading that combines the principles of quantum mechanics with modern machine learning methods. The system includes quantum effects (resonance, interference, decoherence), multi-level memory of different time scales, Markov chains with the ALGLIB library, and adaptive parameter control. The full implementation is done in MQL5 using the built-in matrix/vector types, which removes implementation barriers in MetaTrader 5.


MQL5 Trading Tools (Part 25): Expanding to Multiple Distributions with Interactive Switching
In this article, we expand the MQL5 graphing tool to support seventeen statistical distributions with interactive cycling via a header switch icon. We add type-specific data loading, discrete and continuous histogram computation, and theoretical density functions for each model, with dynamic titles, axis labels, and parameter panels that adapt automatically. The result lets you overlay distribution models on the same sample and compare fit across families without reloading the tool.


Bloch's Relative Moving Average (RMA) Framework Implementation In MQL5
We port Daniel Bloch's Relative Moving Average framework into a complete MetaTrader 5 system. Instead of smoothing price, the RMA measures where price sits inside its own recent distribution on a [0,1] fractile scale, and drives four cross-strategies with a regime-adaptive exit. Includes the engine, indicators, and a backtested Expert Advisor.


Introduction to MQL5 (Part 38): Mastering API and WebRequest Function in MQL5 (XII)
Create a practical bridge between MetaTrader 5 and Binance: fetch 30‑minute klines with WebRequest, extract OHLC/time values from JSON, and confirm a bullish engulfing pattern using only completed candles. Then assemble the query string, compute the HMAC‑SHA256 signature, add X‑MBX‑APIKEY, and submit authenticated orders. You get a clear, end‑to‑end EA workflow from data acquisition to order execution.


MQL5 Trading Tools (Part 28): Filling Sweep Polygons for Butterfly Curve in MQL5
We expand the capabilities of the MetaTrader 5 butterfly curve canvas by adding multi-layered wing fills, vein lines, scale dots, and a full body (abdomen, thorax, head, eyes, antennae). This article implements polygon fills with vertical and radial gradients, as well as filled circles and ellipses, all using supersampling antialiasing. You will also receive reusable MQL5 helper functions and a rendering order that transforms a simple curve into a customizable, detailed chart illustration.

From Basic to Intermediate: Struct (VI)
In this article, we will explore how to approach the implementation of a common structural code base. The goal is to reduce the programming workload and leverage the full potential of the programming language itself—in this case, MQL5.


Neural Networks in Trading: Adaptive Periodic Segmentation (Creating Tokens)
We invite you to embark on an exciting journey through the world of adaptive analysis of financial time series and learn how to turn complex spectral analysis and flexible convolution into real trading signals. You will see how LightGTS listens to the market rhythm, adapting to its changes through a variable-window stride, and how OpenCL acceleration can turn computation into a fast track to profitable decisions.

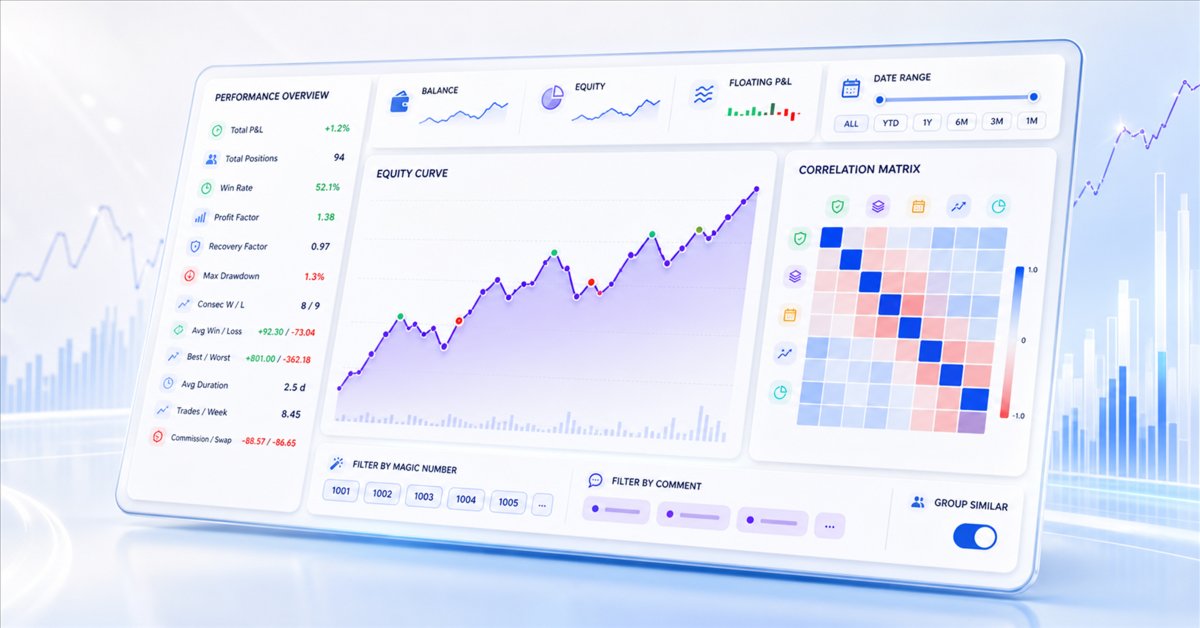
Creating an Interactive Portfolio Analyzer Dashboard with CCanvas in MQL5
This article presents a standalone Portfolio Analyzer dashboard implemented as an Expert Advisor for MetaTrader 5. It reads account deal history, reconstructs closed positions, and attributes results by magic number or normalized comment to deliver clear per-strategy metrics. The interface provides a vector equity curve, date filters, and strategy selectors, plus a Pearson correlation matrix to reveal strategy redundancy. You can attach it to a separate chart without modifying existing trading EAs.
Neural Networks in Trading: Adaptive Periodic Segmentation (Creating Tokens)
We invite you to embark on an exciting journey through the world of adaptive analysis of financial time series and learn how to turn complex spectral analysis and flexible convolution into real trading signals. You will see how LightGTS listens to the market rhythm, adapting to its changes through a variable-window stride, and how OpenCL acceleration can turn computation into a fast track to profitable decisions.


Implementing Practical Modules from Other Languages in MQL5 (Part 05): The Logging module from Python, Log Like a Pro
Integrating Python's logging module with MQL5 empowers traders with a systematic logging approach, simplifying the process of monitoring, debugging, and documenting trading activities. This article explains the adaptation process, offering traders a powerful tool for maintaining clarity and organization in trading software development.


Developing a Replay System (Part 57): Understanding a Test Service
One point to note: although the service code is not included in this article and will only be provided in the next one, I'll explain it since we'll be using that same code as a springboard for what we're actually developing. So, be attentive and patient. Wait for the next article, because every day everything becomes more interesting.


Implementing Anchored VWAP Indicator in MQL5: A Step-by-Step Guide
A step-by-step guide to building an anchored VWAP indicator with an interactive draggable anchor line in MQL5. The article covers the complete implementation, including calculation methodology, session resets, standard deviation bands, and custom visualization. Learn the architectural design decisions behind stateless boundary detection, multi-instance support, and cross-asset volume handling to build a versatile indicator with benchmarking, technical, and analytical capabilities.


Symbolic Aggregate Approximation (SAX) in MQL5: Historical Analog Search and Forecasting
Symbolic Aggregate approXimation (SAX) encodes price windows as short words to enable fast, sound similarity search on history. We implement SAX in pure MQL5, including Gaussian breakpoints, PAA, and the lower-bounding MINDIST, and validate it with a test harness. An indicator applies a no-lookahead, two-stage search, summarizes forward paths in ATR units, and draws a forecast fan, explicitly indicating when the sample shows no edge.


From Basic to Intermediate: Union (II)
Today we have a very funny and quite interesting article. We will look at Union and will try to solve the problem discussed earlier. We'll also explore some unusual situations that can arise when using union in applications. The materials presented here are intended for didactic purposes only. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


Modular Indicator Architecture in MQL5 (Part 1): Stop Copy-Pasting and Start Writing Scalable, Reusable Code
This article develops an object-oriented framework for MQL5 indicators by evolving a primitive example into reusable modules. It formalizes partial buffer recalculation in OnCalculate, moves logic into header-based classes (CAppliedPrice, CSma), and introduces CSubIndiBase, CIndicatorBase, and a registry to centralize requirements. You get portable components, isolated inputs, and clean buffers with minimal boilerplate, making new indicators faster to assemble and easier to maintain.


Biogeography-Based Optimization (BBO)
Biogeography-Based Optimization (BBO) is an elegant global optimization method inspired by natural processes of species migration between islands within archipelagos. The algorithm is based on a simple yet powerful idea: high-quality solutions actively share their characteristics, while low-quality ones actively adopt new features, creating a natural flow of information from the best solutions to the worst. A unique adaptive mutation operator provides an excellent balance between exploration and exploitation. BBO demonstrates high efficiency on a variety of tasks.


Overcoming Accessibility Problems in MQL5 Trading Tools (Part IV): Remote voice trading
Learn a practical way to execute MetaTrader 5 trades from Telegram voice notes using a Python middleware and an MQL5 EA acting as an HTTP client. The article covers architecture, WebRequest polling, in-memory queuing, JSON parsing with null-terminator stripping, and a constrained command grammar with a 0.001-lot default. You will configure the environment and validate round‑trip latency suitable for mobile data connections.