MQL4 and MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Overcoming The Limitation of Machine Learning (Part 2): Lack of Reproducibility
The article explores why trading results can differ significantly between brokers, even when using the same strategy and financial symbol, due to decentralized pricing and data discrepancies. The piece helps MQL5 developers understand why their products may receive mixed reviews on the MQL5 Marketplace, and urges developers to tailor their approaches to specific brokers to ensure transparent and reproducible outcomes. This could grow to become an important domain-bound best practice that will serve our community well if the practice were to be widely adopted.


Neural Networks in Trading: Generalizing Time Series Without Data-Specific Dependence (Mamba4Cast)
In this article, we introduce the Mamba4Cast framework and take a closer look at one of its key components: timestamp-based positional encoding. The article shows shows how time embedding is formed taking into account the calendar structure of the data.


Developing Smart Chart Objects in MQL5 (Part 1): Building a Stateful Trendline Management Framework
This article details a practical framework for converting MetaTrader 5 trendlines from static drawings into managed runtime entities. It covers object discovery, event-driven synchronization of user edits, and confirmation logic based on ATR multipliers and closed candles. A central manager coordinates multiple lines and updates their visual state. Readers can implement consistent, extensible rules for detecting proximity, validating bounces, and confirming breakouts.


Battle Royale Optimizer (BRO)
The article explores the Battle Royale Optimizer algorithm — a metaheuristic in which solutions compete with their nearest neighbors, accumulate “damage,” are replaced when a threshold is exceeded, and periodically shrink the search space around the current best solution. It presents both pseudocode and an MQL5 implementation of the CAOBRO class, including neighbor search, movement toward the best solution, and an adaptive delta interval. Test results on the Hilly, Forest, and Megacity functions highlight the strengths and limitations of the approach. The reader is provided with a ready-to-use foundation for experimentation and tuning key parameters such as popSize and maxDamage.


Feature Engineering for ML (Part 12): Fractal Features in MQL5
A direct MQL5 port of the fractal detector writes each pattern at its center bar, so a buffer read by an expert advisor holds a value that only existed n bars later. We implement CFractalFeatures.mqh with ProcessBar for bar-by-bar use and Compute for full-series recalculation, covering detection, strength scored against a fixed or volatility-scaled floor, an event-based support/resistance ring, and trend-filtered breakout signals. Output is eighteen buffers published at the confirmation bar, verified against the Python reference to within 1e-13.


An introduction to Receiver Operating Characteristic curves
ROC curves are graphical representations used to evaluate the performance of classifiers. Despite ROC graphs being relatively straightforward, there exist common misconceptions and pitfalls when using them in practice. This article aims to provide an introduction to ROC graphs as a tool for practitioners seeking to understand classifier performance evaluation.


Neural Networks in Trading: Skill Hierarchy for Adaptive Agent Behavior (Final Part)
The article discusses the practical implementation of the HiSSD framework in algorithmic trading tasks. It explains how the skill hierarchy and adaptive architecture can be used to build sustainable trading strategies.

Data Science and ML (Part 44): Forex OHLC Time series Forecasting using Vector Autoregression (VAR)
Explore how Vector Autoregression (VAR) models can forecast Forex OHLC (Open, High, Low, and Close) time series data. This article covers VAR implementation, model training, and real-time forecasting in MetaTrader 5, helping traders analyze interdependent currency movements and improve their trading strategies.


Integrating External Applications with MQL5 Community OAuth
Learn how to add “Sign in with MQL5” to your Android app using the OAuth 2.0 authorization code flow. The guide covers app registration, endpoints, redirect URI, Custom Tabs, deep-link handling, and a PHP backend that exchanges the code for an access token over HTTPS. You will authenticate real MQL5 users and access profile data such as rank and reputation.

Neural Networks in Trading: Generalized 3D Referring Expression Segmentation
While analyzing the market situation, we divide it into separate segments, identifying key trends. However, traditional analysis methods often focus on one aspect and thus limit the proper perception. In this article, we will learn about a method that enables the selection of multiple objects to ensure a more comprehensive and multi-layered understanding of the situation.


Neural networks made easy (Part 82): Ordinary Differential Equation models (NeuralODE)
In this article, we will discuss another type of models that are aimed at studying the dynamics of the environmental state.


Mutual information as criteria for Stepwise Feature Selection
In this article, we present an MQL5 implementation of Stepwise Feature Selection based on the mutual information between an optimal predictor set and a target variable.


Developing a Replay System (Part 67): Refining the Control Indicator
In this article, we'll look at what can be achieved with a little code refinement. This refinement is aimed at simplifying our code, making more use of MQL5 library calls and, above all, making it much more stable, secure and easy to use in other projects that we may develop in the future.


Neural Networks in Trading: Multi-Task Learning Based on the ResNeXt Model (Final Part)
We continue exploring a multi-task learning framework based on ResNeXt, which is characterized by modularity, high computational efficiency, and the ability to identify stable patterns in data. Using a single encoder and specialized "heads" reduces the risk of model overfitting and improves the quality of forecasts.


Fast Integration of a Large Language Model with MetaTrader 5 (Part II): Fine-Tuning on Real Data, Backtesting, and Live Trading by the Model
The article describes the process of fine-tuning a language model for trading based on real historical data from MetaTrader 5. The base model, which has only theoretical knowledge of technical analysis, is trained on a thousand examples of the real behavior of currency pairs (EURUSD, GBPUSD, USDCHF, USDCAD) over 180 days. After being trained using Ollama, the model begins to understand the specific characteristics of each instrument.


From Basic to Intermediate: Arrays and Strings (II)
In this article I will show that although we are still at a very basic stage of programming, we can already implement some interesting applications. In this case, we will create a fairly simple password generator. This way we will be able to apply some of the concepts that have been explained so far. In addition, we will look at how solutions can be developed for some specific problems.


The MQL5 Standard Library Explorer (Part 6): Optimizing a generated Expert Advisor
In this discussion, we follow up on the previously developed multi-signal Expert Advisor with the objective of exploring and applying available optimization methods. The aim is to determine whether the trading performance of the EA can be meaningfully improved through systematic optimization based on historical data.


MQL5 Wizard Techniques you should know (Part 87): Volatility-Scaled Money Management with Monotonic Queue in MQL5
This article presents a custom MQL5 money management class that adapts position sizing to real-time volatility using a monotonic queue for O(N) sliding-window extremes. The class applies inverse volatility scaling and optionally validates risk with an RBF network. We show implementation details in the Optimize method and compare results with the inbuilt Size-Optimized class to assess latency and risk control benefits.


From Novice to Expert: Candlestick Momentum Confirmation for Classic Crossover Strategies
In this article, we refine a moving average crossover strategy with a momentum candle filter and an immediate retracement bar confirmation. When both conditions are met, a pending stop order is placed using a pivot-based stop loss and a 2R take profit. The complete MQL5 Expert Advisor code, finite-state-machine logic, and chart annotations are detailed.


Combining LLM, CatBoost, and Quantum Computing into a Unified Trading System
The article proposes a synthesis of new technologies to overcome the limitations of classical indicators in market data analytics. It shows how language models and quantum encoding can reveal hidden market patterns that traditional methods overlook. The experiment confirms the value of new technologies and proposes an updated analysis methodology aligned with the current state of computational innovation.


Designing a Partial Close Engine in MQL5 with Configurable Profit Ladders
This MQL5 engine applies configurable profit ladders in R‑multiples to manage partial closes reliably. It prevents stranded remainders by rounding to lot step, computes close percentages from the original entry volume, and moves the stop to breakeven when configured. A supported filling mode is chosen automatically, and the download includes seven include files, a demo EA, and a verification script.


Developing a Replay System (Part 69): Getting the Time Right (II)
Today we will look at why we need the iSpread feature. At the same time, we will understand how the system informs us about the remaining time of the bar when there is not a single tick available for it. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.

Brain Storm Optimization algorithm (Part I): Clustering
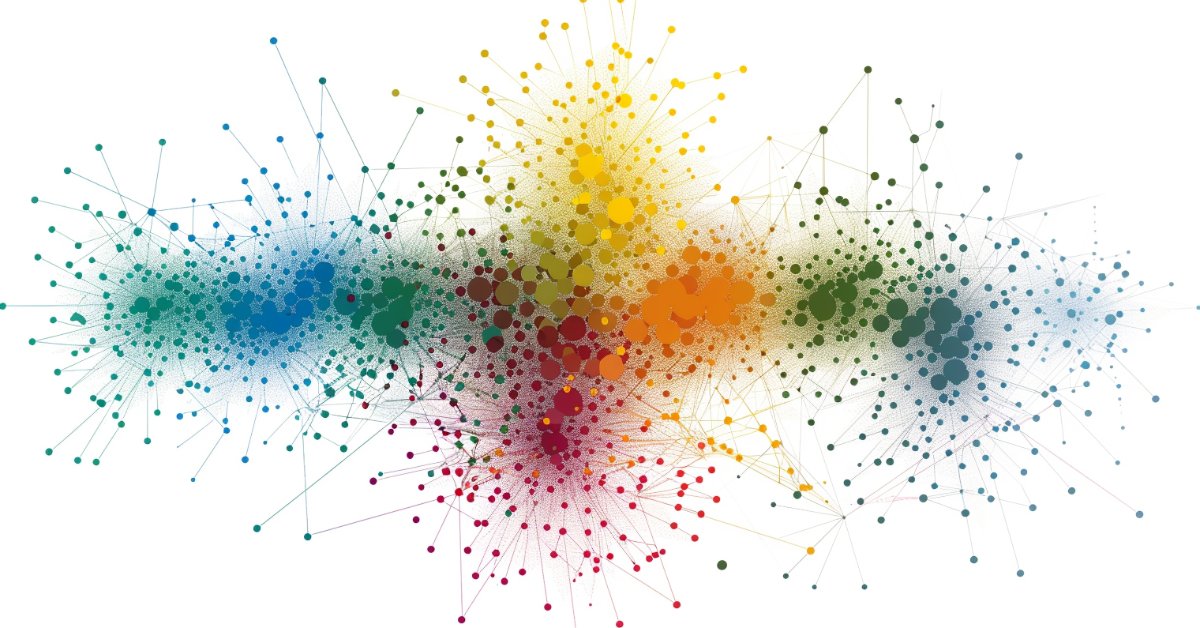
In this article, we will look at an innovative optimization method called BSO (Brain Storm Optimization) inspired by a natural phenomenon called "brainstorming". We will also discuss a new approach to solving multimodal optimization problems the BSO method applies. It allows finding multiple optimal solutions without the need to pre-determine the number of subpopulations. We will also consider the K-Means and K-Means++ clustering methods.


Deterministic Oscillatory Search (DOS)
Deterministic Oscillatory Search (DOS) algorithm is an innovative global optimization method that combines the advantages of gradient and swarm algorithms without the use of random numbers. The fitness oscillation and slope mechanism allows DOS to explore complex search spaces in a deterministic manner.


Forecasting in Trading Using Grey Models
The article discusses the application of Grey models to forecasting financial time series. We will consider the operating principles of Grey models and the specifics of their application to financial series. We will also discuss the advantages and limitations of using these models in trading.

Requesting in Connexus (Part 6): Creating an HTTP Request and Response
In this sixth article of the Connexus library series, we will focus on a complete HTTP request, covering each component that makes up a request. We will create a class that represents the request as a whole, which will help us bring together the previously created classes.

Neural Network in Practice: Least Squares
In this article, we'll look at a few ideas, including how mathematical formulas are more complex in appearance than when implemented in code. In addition, we will consider how to set up a chart quadrant, as well as one interesting problem that may arise in your MQL5 code. Although, to be honest, I still don't quite understand how to explain it. Anyway, I'll show you how to fix it in code.

Chemical reaction optimization (CRO) algorithm (Part I): Process chemistry in optimization
In the first part of this article, we will dive into the world of chemical reactions and discover a new approach to optimization! Chemical reaction optimization (CRO) uses principles derived from the laws of thermodynamics to achieve efficient results. We will reveal the secrets of decomposition, synthesis and other chemical processes that became the basis of this innovative method.


MQL5 Trading Tools (Part 17): Exploring Vector-Based Rounded Rectangles and Triangles
In this article, we explore vector-based methods for drawing rounded rectangles and triangles in MQL5 using canvas, with supersampling for anti-aliased rendering. We implement scanline filling, geometric precomputations for arcs and tangents, and border drawing to create smooth, customizable shapes. This approach lays the groundwork for modern UI elements in future trading tools, supporting inputs for sizes, radii, borders, and opacities.


Integrating MQL5 with Data Processing Packages (Part 8): Using Graph Neural Networks for Liquidity Zone Recognition
This article shows how to represent market structure as a graph in MQL5, turning swing highs/lows into nodes with features and linking them by edges. It trains a Graph Neural Network to score potential liquidity zones, exports the model to ONNX, and runs real-time inference in an Expert Advisor. Readers learn how to build the data pipeline, integrate the model, visualize zones on the chart, and use the signals for rule-based execution.


Digital Signal Processing for Traders: Building Ehlers' Filter Library in MQL5
We implement Ehlers-style DSP filters in a single reusable MQL5 library and use it to build two indicators. The Roofing Filter applies a 2‑pole high‑pass followed by a Super Smoother to isolate the tradeable 10–48‑bar band. The Even Better Sinewave normalizes the wave to about ±1, oscillating in cycle regimes and railing in trends, so you can read cycles and detect regime shifts in charts and EAs.


Larry Williams Market Secrets (Part 7): An Empirical Study of the Trade Day of the Week Concept
An empirical study of Larry Williams’ Trade Day of the Week concept, showing how time-based market bias can be measured, tested, and applied using MQL5. This article presents a practical framework for analyzing win rates and performance across trading days to improve short-term trading systems.

Most notable Artificial Cooperative Search algorithm modifications (ACSm)
Here we will consider the evolution of the ACS algorithm: three modifications aimed at improving the convergence characteristics and the algorithm efficiency. Transformation of one of the leading optimization algorithms. From matrix modifications to revolutionary approaches regarding population formation.


Application of the Grey Model in Technical Analysis of Financial Time Series
This article explores the grey model, a promising tool that can expand trader's capabilities. We will look at some options for applying this model to technical analysis and building trading strategies.


Market Simulation (Part 19): First Steps with SQL (II)
As we explained in the first article about SQL, there is no point in spending time programming procedures to do what is already built into SQL. However, without knowing the basics, you won’t be able to do anything with SQL or take full advantage of everything this tool offers. Therefore, in this article, we will look at how to perform basic tasks in databases.


Implementing Practical Modules from Other Languages in MQL5 (Part 06): Python-Like File IO operations in MQL5
This article shows how to simplify complex MQL5 file operations by building a Python-style interface for effortless reading and writing. It explains how to recreate Python’s intuitive file-handling patterns through custom functions and classes. The result is a cleaner, more reliable approach to MQL5 file I/O.


Overcoming Accessibility Problems in MQL5 Trading Tools (Part III): Bidirectional Speech Communication Between a Trader and an Expert Advisor
Build a local, bidirectional voice interface for MetaTrader 5 using MQL5 WebRequest and two Python services. The article implements offline speech recognition with Vosk, wake‑word detection, an HTTP command endpoint, and a text‑to‑speech server on localhost. You will wire an Expert Advisor that fetches commands, executes trades, and returns spoken confirmations for hands‑free operation.


From Basic to Intermediate: Template and Typename (III)
In this article, we will discuss the first part of the topic, which is not so easy for beginners to understand. In order not to get even more confused and to explain this topic correctly, we will divide the explanation into stages. We will devote this article to the first stage. However, although at the end of the article it may seem that we have reached the deadlock, in fact we will take a step towards another situation, which will be better understood in the next article.


Generative Adversarial Networks (GANs) for Synthetic Data in Financial Modeling (Part 2): Creating Synthetic Symbol for Testing
In this article we are creating a synthetic symbol using a Generative Adversarial Network (GAN) involves generating realistic Financial data that mimics the behavior of actual market instruments, such as EURUSD. The GAN model learns patterns and volatility from historical market data and creates synthetic price data with similar characteristics.


Market Simulation (Part 02): Cross Orders (II)
Unlike what was done in the previous article, here we will test the selection option using an Expert Advisor. Although this is not a final solution yet, it will be enough for now. With the help of this article, you will be able to understand how to implement one of the possible solutions.