MQL4 and MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

Developing an MQTT client for MetaTrader 5: a TDD approach — Part 2
This article is part of a series describing our development steps of a native MQL5 client for the MQTT protocol. In this part we describe our code organization, the first header files and classes, and how we are writing our tests. This article also includes brief notes about the Test-Driven-Development practice and how we are applying it to this project.


Market Heat Map Indicator Based on Prime-Number Density
An innovative indicator based on prime number theory helps identify strong reversal levels that other traders overlook. Testing on 10 assets showed that reversals in mathematically significant zones occur 1.5 to 1.8 times more frequently. Five practical application scenarios with specific rules for filtering out false breakouts and making precise market entries.


Market Simulation (Part 09): Sockets (III)
Today's article is a continuation of the previous one. We will look at the implementation of an Expert Advisor, focusing mainly on how the server code is executed. The code given in the previous article is not enough to make everything work as expected, so we need to dig a little deeper into it. Therefore, it is necessary to read both articles to better understand what will happen.


Chaos optimization algorithm (COA): Continued
We continue studying the chaotic optimization algorithm. The second part of the article deals with the practical aspects of the algorithm implementation, its testing and conclusions.


From Novice to Expert: Weekend Gap Size Effect Research Using MQL5 and Python
The article provides a practical research setup for weekend gap analysis: MQL5 extracts precise pip‑based gaps and tracks fills, while Python performs statistical testing and visualization. You will compute fill rates by gap buckets, model fill probability with logistic regression, and assess time-to-fill via Kaplan–Meier curves. All steps are configurable and reproducible for EURUSD, GBPUSD, USDJPY and beyond.


Market Microstructure in MQL5 (Part 1): Robust Foundation
This article builds the foundation layer of a twelve-part MQL5 market microstructure toolkit. It implements guarded math helpers (SafeDivide, SafeLog, SafeSqrt, SafeExp, SafeTanh), robust data validation (ValidateSymbolV2, SafeCopyClose), trimmed statistical estimators (robust mean var), a linear regression slope, shared structs, and an FFT. You compile a single include file that hardens indicators and expert advisors against silent numerical failures and standardizes data flow for later parts.

Ensemble methods to enhance classification tasks in MQL5
In this article, we present the implementation of several ensemble classifiers in MQL5 and discuss their efficacy in varying situations.


From Basic to Intermediate: Template and Typename (III)
In this article, we will discuss the first part of the topic, which is not so easy for beginners to understand. In order not to get even more confused and to explain this topic correctly, we will divide the explanation into stages. We will devote this article to the first stage. However, although at the end of the article it may seem that we have reached the deadlock, in fact we will take a step towards another situation, which will be better understood in the next article.

MQL5 Wizard Techniques you should know (Part 68): Using Patterns of TRIX and the Williams Percent Range with a Cosine Kernel Network
We follow up our last article, where we introduced the indicator pair of TRIX and Williams Percent Range, by considering how this indicator pairing could be extended with Machine Learning. TRIX and William’s Percent are a trend and support/ resistance complimentary pairing. Our machine learning approach uses a convolution neural network that engages the cosine kernel in its architecture when fine-tuning the forecasts of this indicator pairing. As always, this is done in a custom signal class file that works with the MQL5 wizard to assemble an Expert Advisor.


Building a Correlation-Aware Portfolio Risk Monitor in MQL5
The article quantifies correlation and portfolio risk in MetaTrader 5: from time-aligned returns to a covariance matrix, true portfolio variance against the independent-sum assumption, and position-level risk attribution. A MetaTrader 5 service runs in the background, shows the metrics on a small chart panel, and pushes alerts when risk thresholds are crossed. Source code is provided for an example script, a reusable risk engine class, and the service.

Analyzing binary code of prices on the exchange (Part I): A new look at technical analysis
This article presents an innovative approach to technical analysis based on converting price movements into binary code. The author demonstrates how various aspects of market behavior — from simple price movements to complex patterns — can be encoded in a sequence of zeros and ones.


Extremal Optimization (EO)
The article discusses the Extremal Optimization (EO) algorithm, an optimization method inspired by the Bak-Sneppen self-organized criticality model, where evolution occurs through the elimination of the worst-case components of the system. The modified population version of the algorithm demonstrates a shift away from theoretical principles in favor of practical efficiency, leading to the creation of powerful computational tools.


Hybridization of population algorithms. Sequential and parallel structures
Here we will dive into the world of hybridization of optimization algorithms by looking at three key types: strategy mixing, sequential and parallel hybridization. We will conduct a series of experiments combining and testing relevant optimization algorithms.


Market Simulation (Part 07): Sockets (I)
Sockets. Do you know what they are for or how to use them in MetaTrader 5? If the answer is no, let's start by studying them. In today's article, we'll cover the basics. Since there are several ways to do the same thing, and we are always interested in the result, I want to show that there is indeed a simple way to transfer data from MetaTrader 5 to other programs, such as Excel. However, the main idea is not to transfer data from MetaTrader 5 to Excel, but the opposite, that is, to transfer data from Excel or any other program to MetaTrader 5.

MQL5 Wizard Techniques You Should Know (Part 15): Support Vector Machines with Newton's Polynomial
Support Vector Machines classify data based on predefined classes by exploring the effects of increasing its dimensionality. It is a supervised learning method that is fairly complex given its potential to deal with multi-dimensioned data. For this article we consider how it’s very basic implementation of 2-dimensioned data can be done more efficiently with Newton’s Polynomial when classifying price-action.

Ordinal Encoding for Nominal Variables
In this article, we discuss and demonstrate how to convert nominal predictors into numerical formats that are suitable for machine learning algorithms, using both Python and MQL5.

Central Force Optimization (CFO) algorithm
The article presents the Central Force Optimization (CFO) algorithm inspired by the laws of gravity. It explores how principles of physical attraction can solve optimization problems where "heavier" solutions attract less successful counterparts.

Developing a Replay System (Part 33): Order System (II)
Today we will continue to develop the order system. As you will see, we will be massively reusing what has already been shown in other articles. Nevertheless, you will receive a small reward in this article. First, we will develop a system that can be used with a real trading server, both from a demo account or from a real one. We will make extensive use of the MetaTrader 5 platform, which will provide us with all the necessary support from the beginning.


Building Your Personal Expert Advisor (Part 1): From Fragile Script to Working EA
This article focuses on EA architecture rather than signal design. Starting with a flawed Moving Average crossover EA, we add new‑bar detection to prevent duplicate entries, Magic Number and position awareness, ATR‑based risk levels, and data and trade result validation, along with basic safeguards. You obtain a practical base to build and test advanced systems.


MQL5 Bootstrap (III): Simplified Functions for Working with News
This article presents a unified news model and a set of reusable MQL5 classes for working with the MetaTrader 5 Economic Calendar. You will retrieve, filter, and cache events by time, currency, country, and importance using a single interface across three providers: built-in calendar, CSV, and SQLite. The framework supports export/import, next/previous event lookup, and reliable strategy‑tester backtesting without changing trading logic.


Market Simulation (Part 17): Sockets (XI)
The implementation of the part of the code that will run in MetaTrader 5 does not present any difficulty. However, there are several points that need to be taken into account. This is necessary so that you can make the system work. Remember one important thing: not just one program will be running. In reality, we will have to run three programs simultaneously. It is important to implement and structure each of them in such a way that they can interact and communicate with one another, and that each of them understands what the others are trying or intending to do.

MQL5 Wizard Techniques you should know (Part 40): Parabolic SAR
The Parabolic Stop-and-Reversal (SAR) is an indicator for trend confirmation and trend termination points. Because it is a laggard in identifying trends its primary purpose has been in positioning trailing stop losses on open positions. We, however, explore if indeed it could be used as an Expert Advisor signal, thanks to custom signal classes of wizard assembled Expert Advisors.


RiskGate: Centralized Risk Management for Multiple EAs
Many MetaTrader 5 setups run several EAs on one account, so risk gets fragmented and correlated exposure slips through. The article introduces RiskGate, a centralized Service that evaluates EA intents account‑wide: EAs send a JSON signal, the Service returns approved, lot and reason. You will see the client/server wiring, example rules (daily loss, exposure and correlation caps), unit‑tested handler design, and an EA example. The result is consistent portfolio‑level risk with simpler EAs.


Developing a Terminal Manager (Part 2): Running Multiple Terminal Instances
Let's move on to using multiple terminal instances on the server by setting up a simple control panel for starting and stopping them. Now it is time to expand the functionality and move on to the next stages — implementing more complex features, such as managing multiple terminal instances, state persistence, integration with the MetaTrader 5 API, and a web interface with comprehensive information about the terminals.


Feature Engineering for ML (Part 4): Implementing Time Features in MQL5
Applying Python session boundaries to MQL5 broker timestamps misclassifies session membership by two to three hours on any non-UTC broker, corrupting session flags across the full backtest history. We implement CTimeFeatures.mqh, containing CRingBuffer and CTimeFeatures, with three EA-facing methods: Initialize (UTC offset capture and frequency gate configuration), Update (log return push to session-conditional ring buffers), and Calculate (cyclical encoding, session flags, and session volatility). The output is a flat double array drop-compatible with Python's get_time_features for sub-hourly, hourly, and daily timeframes.

Applying Localized Feature Selection in Python and MQL5
This article explores a feature selection algorithm introduced in the paper 'Local Feature Selection for Data Classification' by Narges Armanfard et al. The algorithm is implemented in Python to build binary classifier models that can be integrated with MetaTrader 5 applications for inference.

Artificial Tribe Algorithm (ATA)
The article provides a detailed discussion of the key components and innovations of the ATA optimization algorithm, which is an evolutionary method with a unique dual behavior system that adapts depending on the situation. ATA combines individual and social learning while using crossover for explorations and migration to find solutions when stuck in local optima.


Building a Modular Fair Value Gap (FVG) Detection Engine in MQL5
This article introduces a modular Fair Value Gap (FVG) detection engine for MQL5 packaged as a reusable include class, it evaluates imbalance zones on closed bars, applies a Simple True Range average filter to eliminate low-volatility noise, and supports wick-touch and close-through mitigation. A companion diagnostic indicator plots active gaps, and an Expert Advisor template demonstrates automated pullback entries with new-bar execution controls.


Overcoming The Limitation of Machine Learning (Part 4): Overcoming Irreducible Error Using Multiple Forecast Horizons
Machine learning is often viewed through statistical or linear algebraic lenses, but this article emphasizes a geometric perspective of model predictions. It demonstrates that models do not truly approximate the target but rather map it onto a new coordinate system, creating an inherent misalignment that results in irreducible error. The article proposes that multi-step predictions, comparing the model’s forecasts across different horizons, offer a more effective approach than direct comparisons with the target. By applying this method to a trading model, the article demonstrates significant improvements in profitability and accuracy without changing the underlying model.


The MQL5 Standard Library Explorer (Part 12): Multi-Timeframe Composite-Score Dashboard
The article implements CMultiTimeframeMatrix, a reusable dashboard that maps symbols vs. timeframes and displays a numeric, colour‑coded score. The score combines trend, momentum, and volatility, updates by timer, and respects performance constraints. You will learn how to build the UI with CAppDialog/CLabel, compute metrics via CMatrixDouble, and embed the component into a thin EA for a consistent, real-time overview.


Implementing a Breakeven Mechanism in MQL5 (Part 2): ATR- and RRR-Based Breakeven
This article completes the implementation of ATR- and RRRR-based breakeven mechanisms in MQL5 and develops, from scratch, a class that makes it easy to switch breakeven modes without having to enter the parameters again. To evaluate the effectiveness of each breakeven type, several backtests are run, analyzing their advantages and disadvantages in the context of algorithmic trading.


Overcoming Accessibility Challenges in MQL5 Trading Tools (Part II): Enabling EA Voice Using a Python Text-to-Speech Engine
Let's discuss how we can make our Expert Advisors speech‑capable using text‑to‑speech technology, partnering Python and MQL5. After reading this article, you will walk away with a working example of an EA that speaks dynamic market information. You will master the application of TTS, the WebRequest function, and learn how Python libraries integrate with the MQL5 language to create a truly voice‑aware trading tool.


Developing a Replay System (Part 68): Getting the Time Right (I)
Today we will continue working on getting the mouse pointer to tell us how much time is left on a bar during periods of low liquidity. Although at first glance it seems simple, in reality this task is much more difficult. This involves some obstacles that we will have to overcome. Therefore, it is important that you have a good understanding of the material in this first part of this subseries in order to understand the following parts.


First Fractal Breakout — Intraday Strategy, Expert Advisor and Backtesting
This article develops a market‑structure‑driven intraday breakout system based on Bill Williams fractals. We define session bounds, derive volatility‑scaled stops, use fixed risk and take‑profit multipliers, and limit trades to one per direction. An MQL5 Expert Advisor, visualization and statistics, tick-level backtests, an ORB comparison, and a cross-asset forward test provide a complete, replicable workflow.


MQL5 Trading Tools (Part 33): Building a Rich Content Markup Documentation System for MQL5 Programs
We extend the Part 9 setup wizard to build a canvas-based, in-chart documentation system for MetaTrader 5. The panel is tabbed and scrollable, supports inline styling, images, and interactive controls, and renders with supersampled anti-aliasing. The result is a reusable engine that any MQL5 program can embed to deliver self-contained documentation directly on the chart.

Category Theory in MQL5 (Part 12): Orders
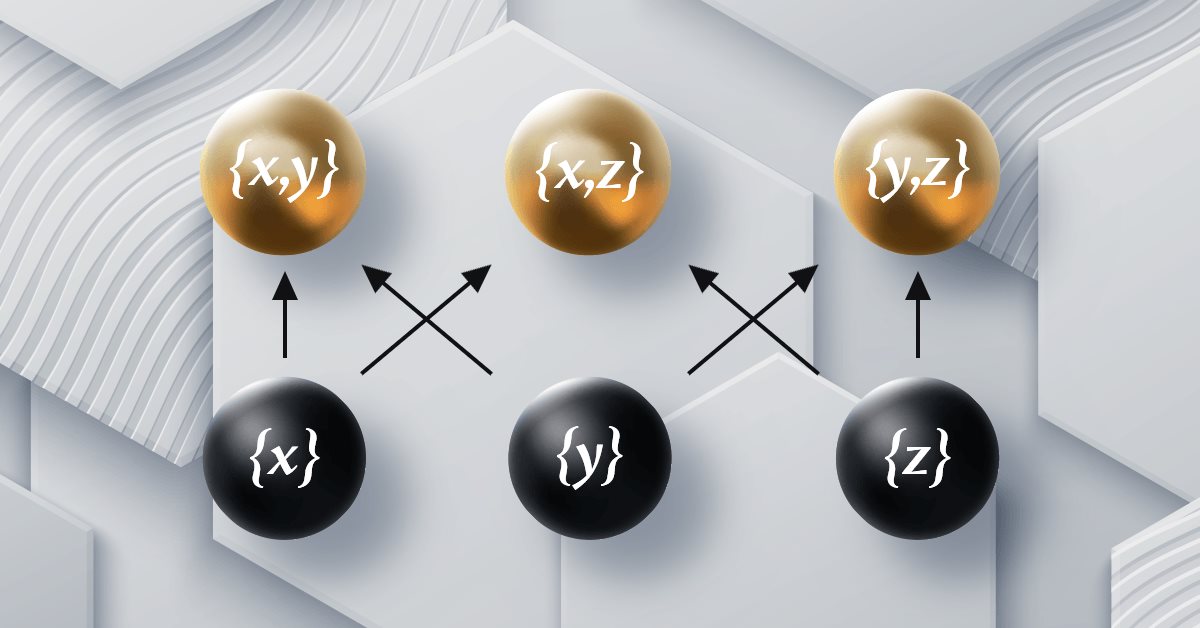
This article which is part of a series that follows Category Theory implementation of Graphs in MQL5, delves in Orders. We examine how concepts of Order-Theory can support monoid sets in informing trade decisions by considering two major ordering types.


Real-Time Polynomial Regression: A Causal Savitzky-Golay Implementation for MQL5
We adapt the Savitzky–Golay filter to a strictly causal, real-time form for MQL5 and derive the fixed coefficients for end-point evaluation. The article provides a full indicator and an Expert Advisor, explains the edge-evaluation noise sensitivity, and implements a multi-bar confirmation safeguard. Backtests on several symbols are shown without cherry-picking. You get ready-to-compile code, parameter guidance, and a reduced-lag alternative to moving averages.

Neuroboids Optimization Algorithm 2 (NOA2)
The new proprietary optimization algorithm NOA2 (Neuroboids Optimization Algorithm 2) combines the principles of swarm intelligence with neural control. NOA2 combines the mechanics of a neuroboid swarm with an adaptive neural system that allows agents to self-correct their behavior while searching for the optimum. The algorithm is under active development and demonstrates potential for solving complex optimization problems.


Can DOOM Run in MetaTrader 5: DLLs, Rendering, and MQL5 Input?
This article demonstrates how to run DOOM inside MetaTrader 5 by integrating a native Windows DLL with an MQL5 Expert Advisor. We cover building the DLL, real-time framebuffer rendering via ResourceCreate, keyboard input with a key-up workaround using GetAsyncKeyState, and running the game loop on a background thread. The techniques are directly applicable to custom visualization, external data bridges, and robust MQL5–native code integration.


Market Simulation (Part 08): Sockets (II)
How about creating something practical using sockets? In today's article, we'll start creating a mini-chat. Let's look together at how this is done - it will be very interesting. Please note that the code provided here is for educational purposes only. It should not be used for commercial purposes or in ready-made applications, as it does not provide data transfer security and the content transmitted over the socket can be accessed.