MQL4 and MQL5 Programming Articles

Study the MQL5 language for programming trading strategies in numerous published articles mostly written by you - the community members. The articles are grouped into categories to help you quicker find answers to any questions related to programming: Integration, Tester, Trading Strategies, etc.
Follow our new publications and discuss them on the Forum!
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Non-stationary processes and spurious regression
The article demonstrates spurious regression occurring when attempting to apply regression analysis to non-stationary processes using Monte Carlo simulation.


Interactive Supply and Demand Zone Manager in MQL5 (Part III): Zone Analysis, Stateful Interaction, and Pending Event Management
We extend the stateful supply and demand framework for MetaTrader 5 with a quantitative admission model and a dedicated interaction engine. Candidate zones are scored by structural symmetry, volume participation, and ATR‑normalized displacement, then classified into objective tiers. Admitted zones follow a deterministic lifecycle that tracks first touch, validates bounces, or confirms breakouts, with full telemetry for analysis and reproducibility.

From Basic to Intermediate: Definitions (I)
In this article we will do things that many will find strange and completely out of context, but which, if used correctly, will make your learning much more fun and interesting: we will be able to build quite interesting things based on what is shown here. This will allow you to better understand the syntax of the MQL5 language. The materials provided here are for educational purposes only. It should not be considered in any way as a final application. Its purpose is not to explore the concepts presented.


Online Machine Learning for Trade Signal Filtering in MQL5 (Part 1)
This article implements an online logistic‑regression trade filter in native MQL5 and integrates it into an EMA‑crossover EA with a closed‑trade feedback loop. It details the shared class, features, SGD update, persistence, and a read‑only probability view. Synthetic experiments cover multi‑seed separation, calibration, feature ablation, regime‑shift baselines, and hyperparameter sweeps. You get reproducible scripts and a walk‑forward protocol to validate the filter on your own instrument.


First Fractal Breakout — Intraday Strategy, Expert Advisor and Backtesting
This article develops a market‑structure‑driven intraday breakout system based on Bill Williams fractals. We define session bounds, derive volatility‑scaled stops, use fixed risk and take‑profit multipliers, and limit trades to one per direction. An MQL5 Expert Advisor, visualization and statistics, tick-level backtests, an ORB comparison, and a cross-asset forward test provide a complete, replicable workflow.


Covariance Matrix Adaptation Evolution Strategy (CMA-ES)
The article explores one of the most interesting non-gradient optimization algorithms, which learns to understand the geometry of the objective function. We will focus on the classical implementation of CMA-ES with a slight modification - replacing the normal distribution with the power one. We will thoroughly examine the math behind the algorithm, as well as practical implementation, and check where CMA-ES is unbeatable and where it should be avoided.


Quantum Computing and Gradient Boosting in EURUSD Trading
The article describes the practical implementation of a hybrid algorithmic trading system that combines quantum computing (IBM Qiskit) and gradient boosting (CatBoost) to predict movements in the EURUSD pair on the hourly time frame. The system extracts four unique quantum features from a probability distribution across 256 states using eight qubits and, in combination with classical indicators and delta encoding of time categories, achieves 62% accuracy on 15,000 candlesticks.


Neural Networks in Trading: LSTM Optimization for Multivariate Time Series Forecasting (DA-CG-LSTM)
This article introduces the DA-CG-LSTM algorithm, which offers new approaches to time series analysis and forecasting. It explains how innovative attention mechanisms and model flexibility can improve forecast accuracy.


Population optimization algorithms: Micro Artificial immune system (Micro-AIS)
The article considers an optimization method based on the principles of the body's immune system - Micro Artificial Immune System (Micro-AIS) - a modification of AIS. Micro-AIS uses a simpler model of the immune system and simple immune information processing operations. The article also discusses the advantages and disadvantages of Micro-AIS compared to conventional AIS.


Building an Object-Oriented Order Block Engine in MQL5
The article presents a production-oriented Order Block engine for MQL5 packaged as an include class, it validates zones via displacement and market structure break, maintains mitigation state only on closed bars, and avoids heavy copies by passing data by reference. A diagnostic indicator plots zones, and an EA gates logic to new bars for stable performance and reproducible tests.


Feature Engineering for ML (Part 11): Fractal Features in Python
The article examines a Williams five‑bar fractal feature pipeline and shows how a centered rolling window creates a true look‑ahead leak. It identifies two additional silent bugs—a hardcoded shift tied to the default n and a volatility threshold that ignores its input—and consolidates fixes under a single leak_safe flag. Readers get leak‑free fractal, level, trend, and signal features, plus guidance on when unshifted columns remain valid for labeling.


Price Action Analysis Toolkit Development (Part 71): Weekend Gap Structure Mapping in MQL5
The article delivers an object-based MQL5 implementation that detects weekend gaps from time discontinuities and renders them directly on the chart. It manages graphical objects, tracks state transitions (fresh, partial, reaction, filled), and preserves completed gaps as historical zones. The result is a reproducible framework for monitoring how price revisits and fills weekend gap structures.


Beyond the Clock (Part 4): Efficacy of Bars on Trending and Mean-Reversion Strategies
Does better return conditioning buy strategy performance? We hold bar count fixed across time, tick, tick-imbalance, and tick-runs on 60.5 million EURUSD ticks, then meta-label RSI, Bollinger, and ADX/DI entries and score with purged cross-validation. No family delivers a consistent edge; efficacy varies narrowly and the best case fails a permutation test. Readers learn how to control overlap, leakage, and multiple testing in bar studies.


Market Positioning Codex for VGT with Kendall's Tau and Distance Correlation
In this article, we look to explore how a complimentary indicator pairing can be used to analyze the recent 5-year history of Vanguard Information Technology Index Fund ETF. By considering two options of algorithms, Kendall’s Tau and Distance-Correlation, we look to select not just an ideal indicator pair for trading the VGT, but also suitable signal-pattern pairings of these two indicators.


Neural Networks in Trading: An Intelligent Forecast Pipeline (Sparse Mixture of Experts)
We invite you to explore the practical implementation of a sparse mixture of experts block for time series in the OpenCL computing environment. This article provides a step-by-step explanation of how masked multi-window convolution works, as well as how gradient-based training is organized in the presence of multiple information streams.


Developing a Manual Backtesting Expert Advisor: Additional Features
We enhance the manual backtesting EA with real-time lot adjustment, an order module for buy/sell stops and limits, and a Trade Manager to modify TP/SL and close positions individually. The article explains control setup with CButton/CBmpButton/CEdit, logic in OnTick, and workarounds for Strategy Tester input constraints. Readers can reuse these components to speed up testing workflows and implement robust trade management.


How to Test and Customize Built-in MQL5 Programs: Custom BullishBearish MeetingLines Stoch Expert Advisor
We demonstrate a practical customization path for a built-in MetaTrader 5 EA using BullishBearish MeetingLines Stoch. The workflow covers baseline testing in the Strategy Tester, parameter optimization, and code-level changes. Two modifications are implemented: exposing Stochastic thresholds as inputs and adding an optional Moving Average filter to limit counter‑trend signals. The article includes the full modified code for replication.


The Avellaneda-Stoikov Model: Inventory-Aware Quoting for Two-Sided Strategies
This article builds the Avellaneda–Stoikov formulas in MQL5, feeds them with rolling estimates of mid-price volatility and a proxy for order-flow intensity, and plots the reservation price with bid and ask in real time. A bar-by-bar simulation contrasts adaptive and fixed quoting under the same fill rules. The result is a tested class, an indicator, and a backtest to improve inventory control in two‑sided strategies.

The Disagreement Problem: Diving Deeper into The Complexity Explainability in AI
In this article, we explore the challenge of understanding how AI works. AI models often make decisions in ways that are hard to explain, leading to what's known as the "disagreement problem". This issue is key to making AI more transparent and trustworthy.

MQL5 Wizard Techniques you should know (Part 18): Neural Architecture Search with Eigen Vectors
Neural Architecture Search, an automated approach at determining the ideal neural network settings can be a plus when facing many options and large test data sets. We examine how when paired Eigen Vectors this process can be made even more efficient.


Overcoming The Limitation of Machine Learning (Part 8): Nonparametric Strategy Selection
This article shows how to configure a black-box model to automatically uncover strong trading strategies using a data-driven approach. By using Mutual Information to prioritize the most learnable signals, we can build smarter and more adaptive models that outperform conventional methods. Readers will also learn to avoid common pitfalls like overreliance on surface-level metrics, and instead develop strategies rooted in meaningful statistical insight.


A Practical Kalman Filter Price Smoother in MQL5: Adaptive Noise Estimation Without External Libraries
Fixed-weight moving averages introduce regime-insensitive lag. This work presents an adaptive scalar Kalman filter indicator in native MQL5 that estimates process noise Q from rolling return variance and measurement noise R from rolling price variance, with floor clamps for stability, and recomputes the Kalman Gain on every bar. The chart-overlay output is benchmarked against a 20-period EMA using MAE, RMSE, lag, and smoothness metrics to quantify tracking and noise suppression.


How to Detect and Normalize Chart Objects in MQL5 (Part 4): Fully Automated Analytical Objects System
This part extends the series with a modular, event-driven MQL5 pipeline: swing detection feeds an object placer for trendlines, SR, Fibonacci, channels, and pitchforks; evaluators monitor interactions and generate signals; adaptive logic executes trades with valid stops per instrument. The topology manager synchronizes placement, scanning, and processing. The code is structured into reusable components for easy reuse and scaling.


Publish Your Article Code to MQL5 Algo Forge in 10 Minutes: A Step-by-Step Guide
The article provides a step-by-step guide on how to migrate code from a published project into a fully-fledged MQL5 Algo Forge project. You will set up the environment and authentication in MetaEditor, create a project in Shared Projects, select the type, arrange the files, add README.md, check the encoding and build, commit the changes to Git, and open the repository publicly. The article helps to build a working structure and preserve version history for the convenience of readers.


Building a Visual Position Planning Tool for MetaTrader 5
This article develops a visual position planning tool in MQL5 for evaluating trade setups before execution. The tool utilizes interactive Entry, Stop-Loss, and Take-Profit lines to calculate the stop distance, risk amount, estimated position size, potential reward, and risk-to-reward ratio directly on the chart. It supports market, limit, and stop order scenarios while keeping the focus strictly on planning and analysis rather than trade execution.


Developing a Replay System (Part 64): Playing the service (V)
In this article, we will look at how to fix two errors in the code. However, I will try to explain them in a way that will help you, beginner programmers, understand that things don't always go as you expect. Anyway, this is an opportunity to learn. The content presented here is intended solely for educational purposes. In no way should this application be considered as a final document with any purpose other than to explore the concepts presented.


From Basic to Intermediate: Objects (II)
In today's article, we will look at how to control some object properties in a simple way using code. We will also see how a custom application can place more than one object on the same chart. In addition, we will begin to understand the importance of assigning a short name to any indicator we plan to implement.


Data Science and ML (Part 48): Are Transformers a Big Deal for Trading?
From ChatGPT to Gemini and many model AI tools for text, image, and video generation. Transformers have rocked the AI-world. But, are they applicable in the financial (trading) space? Let's find out.

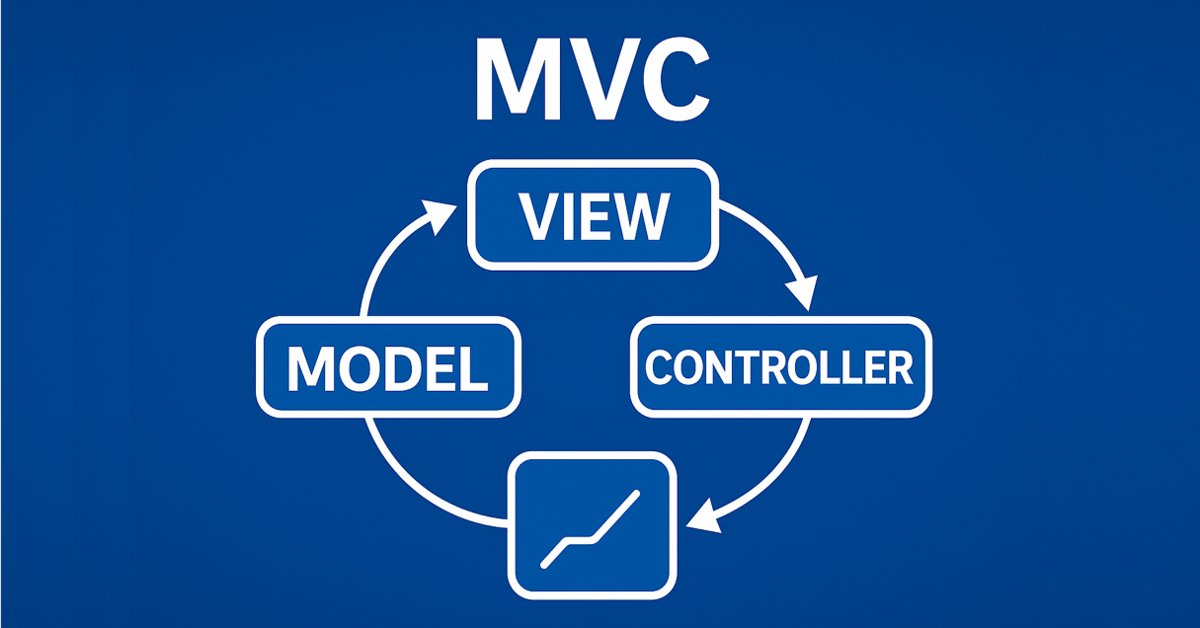
Table and Header Classes based on a table model in MQL5: Applying the MVC concept
This is the second part of the article devoted to the implementation of the table model in MQL5 using the MVC (Model-View-Controller) architectural paradigm. The article discusses the development of table classes and the table header based on a previously created table model. The developed classes will form the basis for further implementation of View and Controller components, which will be discussed in the following articles.


MQL5 Wizard Techniques you should know (Part 88): Using Blooms Filter with a Custom Trailing Class
Our next focus in these series on ideas that can be rapidly prototyped with the MQL5 Wizard, is a Custom Trailing class that uses the Blooming Filter. Trailing Stop systems are an optional but very resourceful part to any trading system that we want to explore more in these series besides the traditional Entry Signals.


File-Based Versioning of EA Parameters in MQL5
This article explains how to implement parameter versioning in MQL5 using binary files and packed structures. It shows how to write and read fixed-size records with FileWriteStruct and FileReadStruct in FILE_BIN mode, including version numbers, timestamps, and a checksum. You will also see how to detect changes via checksums, append records safely, and load the latest configuration without overwriting prior settings.


Developing a Replay System (Part 30): Expert Advisor project — C_Mouse class (IV)
Today we will learn a technique that can help us a lot in different stages of our professional life as a programmer. Often it is not the platform itself that is limited, but the knowledge of the person who talks about the limitations. This article will tell you that with common sense and creativity you can make the MetaTrader 5 platform much more interesting and versatile without resorting to creating crazy programs or anything like that, and create simple yet safe and reliable code. We will use our creativity to modify existing code without deleting or adding a single line to the source code.


Reimagining Classic Strategies (Part VIII): Currency Markets And Precious Metals on the USDCAD
In this series of articles, we revisit well-known trading strategies to see if we can improve them using AI. In today's discussion, join us as we test whether there is a reliable relationship between precious metals and currencies.


Development and Forward Testing of an Autonomous LLM Agent for Trading with SEAL
A hybrid architecture based on Llama 3.2 and SEAL is being tested on eight currency pairs (M15), with forward-period data isolation and information leakage control. The methodology combines adversarial self-play, curriculum learning, and class balancing to ensure stable training. The experiments confirm the gap between forecast accuracy and actual returns, providing readers with practical guidelines for testing strategies and accurately assessing their generalizability.


Neural Networks in Trading: Actor—Director—Critic (Final Part)
The Actor–Director–Critic framework is an evolution of the classic agent learning architecture. The article presents practical experience of its implementation and adaptation to financial market conditions.


Mastering Log Records (Part 9): Implementing the builder pattern and adding default configurations
This article shows how to drastically simplify the use of the Logify library with the Builder pattern and automatic default configurations. It explains the structure of the specialized builders, how to use them with smart auto-completion, and how to ensure a functional log even without manual configuration. It also covers tweaks for MetaTrader 5 build 5100.


Mastering Log Records (Part 10): Avoiding Log Replay by Implementing a Suppression
We created a log suppression system in the Logify library. It details how the CLogifySuppression class reduces console noise by applying configurable rules to avoid repetitive or irrelevant messages. We also cover the external configuration framework, validation mechanisms, and comprehensive testing to ensure robustness and flexibility in log capture during bot or indicator development.


Introduction to MQL5 (Part 39): Beginner Guide to File Handling in MQL5 (I)
This article introduces file handling in MQL5 using a practical, project-based workflow. You will use FileSelectDialog to choose or create a CSV file, open it with FileOpen, and write structured account headers such as account name, balance, login, date range, and last update. The result is a clear foundation for a reusable trading journal and safe file operations in MetaTrader 5.


MQL5 Trading Tools (Part 37): Adding a Per-Object Property-Editing Ribbon to the Canvas Drawing Layer
We add a descriptor-driven property stack and a floating ribbon that binds to the current selection on the drawing layer. The article covers the descriptor list for each tool, the engine get/set API with snapshot-and-restore live preview, and widget renderers for color, opacity, line width, line style, fonts, and level visibility. You get in-place, real-time editing of object appearance via a compact, draggable panel.


Seasonality Indicator by Hours, Days of the Week, and Days of the Month
The article explains how to develop a tool for analyzing recurring price patterns in financial markets — by day of the month (1-31), day of the week (Monday-Sunday), or hour of the day (0-23). The indicator analyzes historical data, calculates the average return for each period, and displays the results as a histogram with a forecast. It includes customizable parameters: seasonality type, number of bars analyzed, display as percentages or absolute values, chart colors.