Articles on strategy testing in MQL5

How to develop, write and test a trading strategy, how to find the optimal system parameters and how to analyze the results? The MetaTrader platform offers developers of trading robots rich functionality for fast and accurate testing of trading ideas. Read these articles to learn how to test multi-currency robots and how to use MQL5 Cloud Network for optimization purposes.
Developers of automated trading systems are recommended to start with the testing fundamentals and tick generation algorithms in the strategy tester.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Category Theory in MQL5 (Part 18): Naturality Square
This article continues our series into category theory by introducing natural transformations, a key pillar within the subject. We look at the seemingly complex definition, then delve into examples and applications with this series’ ‘bread and butter’; volatility forecasting.


Stress Testing Trade Sequences with Monte Carlo in MQL5
A backtest shows only one path among many possible outcomes. This MQL5 script performs 1000 bootstrap Monte Carlo resamples of a trade P&L series, draws a percentile fan chart on the chart via CCanvas, and reports probability of ruin, value at risk, and 95th‑percentile worst drawdown. The result is a practical view of path risk and drawdown exposure beyond a single equity curve.

Category Theory in MQL5 (Part 7): Multi, Relative and Indexed Domains
Category Theory is a diverse and expanding branch of Mathematics which is only recently getting some coverage in the MQL5 community. These series of articles look to explore and examine some of its concepts & axioms with the overall goal of establishing an open library that provides insight while also hopefully furthering the use of this remarkable field in Traders' strategy development.

Archery Algorithm (AA)
The article takes a detailed look at the archery-inspired optimization algorithm, with an emphasis on using the roulette method as a mechanism for selecting promising areas for "arrows". The method allows evaluating the quality of solutions and selecting the most promising positions for further study.

Developing a multi-currency Expert Advisor (Part 6): Automating the selection of an instance group
After optimizing the trading strategy, we receive sets of parameters. We can use them to create several instances of trading strategies combined in one EA. Previously, we did this manually. Here we will try to automate this process.


Developing a Replay System (Part 32): Order System (I)
Of all the things that we have developed so far, this system, as you will probably notice and eventually agree, is the most complex. Now we need to do something very simple: make our system simulate the operation of a trading server. This need to accurately implement the way the trading server operates seems like a no-brainer. At least in words. But we need to do this so that the everything is seamless and transparent for the user of the replay/simulation system.

Artificial Electric Field Algorithm (AEFA)
The article presents an artificial electric field algorithm (AEFA) inspired by Coulomb's law of electrostatic force. The algorithm simulates electrical phenomena to solve complex optimization problems using charged particles and their interactions. AEFA exhibits unique properties in the context of other algorithms related to laws of nature.


Developing a Replay System (Part 48): Understanding the concept of a service
How about learning something new? In this article, you will learn how to convert scripts into services and why it is useful to do so.

Developing a multi-currency Expert Advisor (Part 8): Load testing and handling a new bar
As we progressed, we used more and more simultaneously running instances of trading strategies in one EA. Let's try to figure out how many instances we can get to before we hit resource limitations.


Quantitative approach to risk management: Applying VaR model to optimize multi-currency portfolio using Python and MetaTrader 5
This article explores the potential of the Value at Risk (VaR) model for multi-currency portfolio optimization. Using the power of Python and the functionality of MetaTrader 5, we demonstrate how to implement VaR analysis for efficient capital allocation and position management. From theoretical foundations to practical implementation, the article covers all aspects of applying one of the most robust risk calculation systems – VaR – in algorithmic trading.


Developing a multi-currency Expert Advisor (Part 16): Impact of different quote histories on test results
The EA under development is expected to show good results when trading with different brokers. But for now we have been using quotes from a MetaQuotes demo account to perform tests. Let's see if our EA is ready to work on a trading account with different quotes compared to those used during testing and optimization.


Market Simulation (Part 20): First steps with SQL (III)
Although we can perform operations on a database containing about 10 records, the material is absorbed much better when we work with a file that contains more than 15 thousand records. That is, if we tried to create such a database manually, this task would be enormous. However, it is difficult to find such a database, even for educational purposes, that is available for download. But in reality, we don’t need to resort to that — we can use MetaTrader 5 to create a database for ourselves. In today's article, we will look at how to do this.

Developing a Replay System — Market simulation (Part 09): Custom events
Here we'll see how custom events are triggered and how the indicator reports the state of the replay/simulation service.


Developing a Replay System (Part 26): Expert Advisor project — C_Terminal class
We can now start creating an Expert Advisor for use in the replay/simulation system. However, we need something improved, not a random solution. Despite this, we should not be intimidated by the initial complexity. It's important to start somewhere, otherwise we end up ruminating about the difficulty of a task without even trying to overcome it. That's what programming is all about: overcoming obstacles through learning, testing, and extensive research.


Developing a multi-currency Expert Advisor (Part 15): Preparing EA for real trading
As we gradually approach to obtaining a ready-made EA, we need to pay attention to issues that seem secondary at the stage of testing a trading strategy, but become important when moving on to real trading.


Formulating Dynamic Multi-Pair EA (Part 9): Market Microstructure Execution Noise Filtering
This article presents a multi-symbol execution filter that scores real-time market quality before any trade is allowed. It measures spread behavior, tick velocity, quote gaps, micro-volatility, and a slippage estimate, then classifies the state to block degraded conditions. Once noise settles, a liquidity sweep continuation model evaluates structure shifts so entries occur only when execution is mechanically stable.


How to Research a Trading Idea: A Range Breakout Strategy Case Study
This article demonstrates a practical approach to researching trading ideas using a range breakout strategy as an example. We will go through the entire process, from formalizing trading rules and building a baseline model to parameter optimization, forward testing, and evaluating the robustness of the results. The main goal of the article is to develop an understanding of how statistics and testing can be used to identify, validate, and evaluate trading hypotheses.


Atomic Orbital Search (AOS) algorithm
The article considers the Atomic Orbital Search (AOS) algorithm, which uses the concepts of the atomic orbital model to simulate the search for solutions. The algorithm is based on probability distributions and the dynamics of interactions in the atom. The article discusses in detail the mathematical aspects of AOS, including updating the positions of candidate solutions and the mechanisms of energy absorption and release. AOS opens new horizons for applying quantum principles to computing problems by offering an innovative approach to optimization.


Developing a Replay System — Market simulation (Part 11): Birth of the SIMULATOR (I)
In order to use the data that forms the bars, we must abandon replay and start developing a simulator. We will use 1 minute bars because they offer the least amount of difficulty.

Category Theory in MQL5 (Part 5): Equalizers
Category Theory is a diverse and expanding branch of Mathematics which is only recently getting some coverage in the MQL5 community. These series of articles look to explore and examine some of its concepts & axioms with the overall goal of establishing an open library that provides insight while also hopefully furthering the use of this remarkable field in Traders' strategy development.


From Novice to Expert: Extending a Liquidity Strategy with Trend Filters
The article extends a liquidity-based strategy with a simple trend constraint: trade liquidity zones only in the direction of the EMA(50). It explains filtering rules, presents a reusable TrendFilter.mqh class and EA integration in MQL5, and compares baseline versus filtered tests. Readers gain a clear directional bias, reduced overtrading in countertrend phases, and ready-to-use source files.


Developing a Replay System — Market simulation (Part 10): Using only real data for Replay
Here we will look at how we can use more reliable data (traded ticks) in the replay system without worrying about whether it is adjusted or not.


Developing a Replay System — Market simulation (Part 14): Birth of the SIMULATOR (IV)
In this article we will continue the simulator development stage. this time we will see how to effectively create a RANDOM WALK type movement. This type of movement is very intriguing because it forms the basis of everything that happens in the capital market. In addition, we will begin to understand some concepts that are fundamental to those conducting market analysis.


Python-MetaTrader 5 Strategy Tester (Part 02): Dealing with Bars, Ticks, and Overloading Built-in Functions in a Simulator
In this article, we introduce functions similar to those provided by the Python-MetaTrader 5 module, providing a simulator with a familiar interface and a custom way of handling bars and ticks internally.


Population optimization algorithms: Differential Evolution (DE)
In this article, we will consider the algorithm that demonstrates the most controversial results of all those discussed previously - the differential evolution (DE) algorithm.


Using the MQL5 Economic Calendar for News Filter (Part 4): Accurate Backtesting with Static Data
This article implements a static, CSV-based news source for the Strategy Tester, so historical economic news events can be preloaded and queried during backtesting. It replaces live calendar calls in tester mode with a fast in-memory search, preserves the live logic for trading, and delivers deterministic, repeatable results with explicit control over included events, enabling reliable validation of news-aware filters, stop suspension, and trade-blocking rules.


Developing a multi-currency Expert Advisor (Part 18): Automating group selection considering forward period
Let's continue to automate the steps we previously performed manually. This time we will return to the automation of the second stage, that is, the selection of the optimal group of single instances of trading strategies, supplementing it with the ability to take into account the results of instances in the forward period.

Developing a Replay System — Market simulation (Part 08): Locking the indicator
In this article, we will look at how to lock the indicator while simply using the MQL5 language, and we will do it in a very interesting and amazing way.

Implementing Practical Modules from Other Languages in MQL5 (Part 03): Schedule Module from Python, the OnTimer Event on Steroids
The schedule module in Python offers a simple way to schedule repeated tasks. While MQL5 lacks a built-in equivalent, in this article we’ll implement a similar library to make it easier to set up timed events in MetaTrader 5.


Developing a Replay System — Market simulation (Part 24): FOREX (V)
Today we will remove a limitation that has been preventing simulations based on the Last price and will introduce a new entry point specifically for this type of simulation. The entire operating mechanism will be based on the principles of the forex market. The main difference in this procedure is the separation of Bid and Last simulations. However, it is important to note that the methodology used to randomize the time and adjust it to be compatible with the C_Replay class remains identical in both simulations. This is good because changes in one mode lead to automatic improvements in the other, especially when it comes to handling time between ticks.

Developing a multi-currency Expert Advisor (Part 20): Putting in order the conveyor of automatic project optimization stages (I)
We have already created quite a few components that help arrange auto optimization. During the creation, we followed the traditional cyclical structure: from creating minimal working code to refactoring and obtaining improved code. It is time to start clearing up our database, which is also a key component in the system we are creating.


Developing Market Entropy Indicator: Trading System Based on Information Theory
This article explores the development of a Market Entropy Indicator based on principles from Information Theory to measure the uncertainty and information content within financial markets. By applying concepts such as Shannon Entropy to price movements, the indicator quantifies whether the market is structured (trending), transitioning, or chaotic.

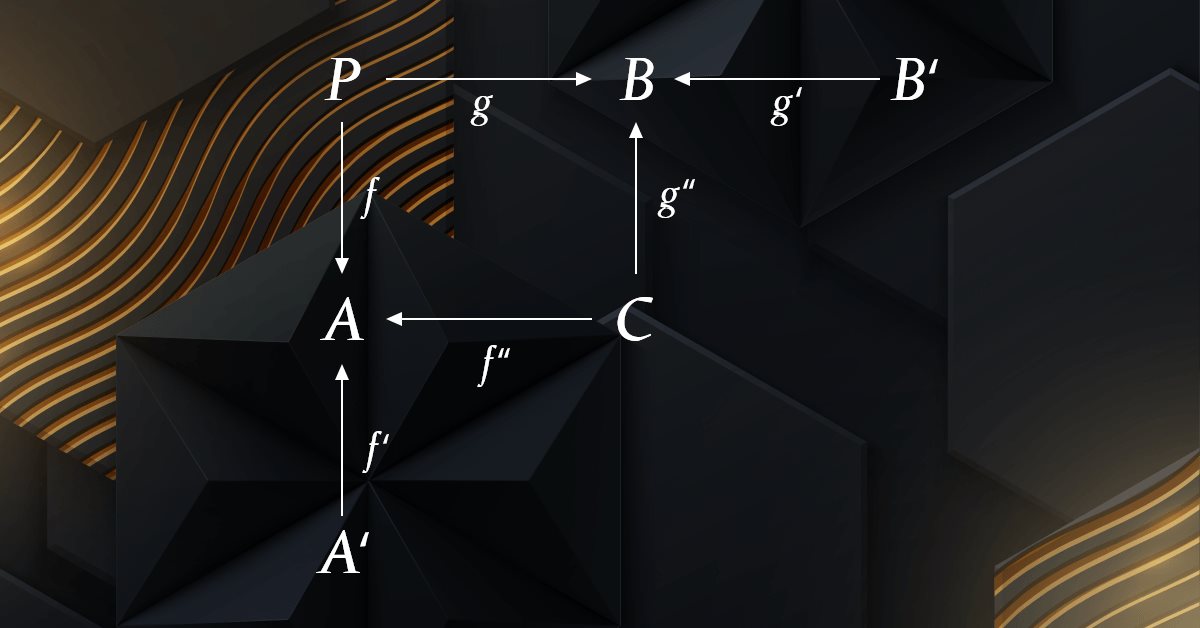
Category Theory in MQL5 (Part 4): Spans, Experiments, and Compositions
Category Theory is a diverse and expanding branch of Mathematics which as of yet is relatively uncovered in the MQL5 community. These series of articles look to introduce and examine some of its concepts with the overall goal of establishing an open library that provides insight while hopefully furthering the use of this remarkable field in Traders' strategy development.


Developing a Replay System — Market simulation (Part 13): Birth of the SIMULATOR (III)
Here we will simplify a few elements related to the work in the next article. I'll also explain how you can visualize what the simulator generates in terms of randomness.


Developing a Replay System (Part 73): An Unusual Communication (II)
In this article, we will look at how to transmit information in real time between the indicator and the service, and also understand why problems may arise when changing the timeframe and how to solve them. As a bonus, you will get access to the latest version of the replay /simulation app.

Developing a multi-currency Expert Advisor (Part 24): Adding a new strategy (I)
In this article, we will look at how to connect a new strategy to the auto optimization system we have created. Let's see what kind of EAs we need to create and whether it will be possible to do without changing the EA library files or minimize the necessary changes.


Developing a Replay System (Part 42): Chart Trade Project (I)
Let's create something more interesting. I don't want to spoil the surprise, so follow the article for a better understanding. From the very beginning of this series on developing the replay/simulator system, I was saying that the idea is to use the MetaTrader 5 platform in the same way both in the system we are developing and in the real market. It is important that this is done properly. No one wants to train and learn to fight using one tool while having to use another one during the fight.


Developing a Replay System (Part 70): Getting the Time Right (III)
In this article, we will look at how to use the CustomBookAdd function correctly and effectively. Despite its apparent simplicity, it has many nuances. For example, it allows you to tell the mouse indicator whether a custom symbol is on auction, being traded, or the market is closed. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


Market Simulation (Part 23): Position View (I)
The content we will cover from this point on is much more complex in terms of theory and concepts. I will try to make the material as simple as possible. The programming part itself is quite simple and straightforward. But if you do not understand the theory behind it, you will be left with no practical basis at all for refining or adapting the replay/simulation system to tasks different from the ones I am going to show. I do not want you merely to compile and use the code I present. I want you to learn, understand and, if possible, be able to create something even better.

Population optimization algorithms: Mind Evolutionary Computation (MEC) algorithm
The article considers the algorithm of the MEC family called the simple mind evolutionary computation algorithm (Simple MEC, SMEC). The algorithm is distinguished by the beauty of its idea and ease of implementation.