Articles on strategy testing in MQL5

How to develop, write and test a trading strategy, how to find the optimal system parameters and how to analyze the results? The MetaTrader platform offers developers of trading robots rich functionality for fast and accurate testing of trading ideas. Read these articles to learn how to test multi-currency robots and how to use MQL5 Cloud Network for optimization purposes.
Developers of automated trading systems are recommended to start with the testing fundamentals and tick generation algorithms in the strategy tester.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register


Market Simulation (Part 06): Transferring Information from MetaTrader 5 to Excel
Many people, especially non=programmers, find it very difficult to transfer information between MetaTrader 5 and other programs. One such program is Excel. Many use Excel as a way to manage and maintain their risk control. It is an excellent program and easy to learn, even for those who are not VBA programmers. Here we will look at how to establish a connection between MetaTrader 5 and Excel (a very simple method).


Developing a multi-currency Expert Advisor (Part 13): Automating the second stage — selection into groups
We have already implemented the first stage of the automated optimization. We perform optimization for different symbols and timeframes according to several criteria and store information about the results of each pass in the database. Now we are going to select the best groups of parameter sets from those found at the first stage.

Developing a multi-currency Expert Advisor (Part 19): Creating stages implemented in Python
So far we have considered the automation of launching sequential procedures for optimizing EAs exclusively in the standard strategy tester. But what if we would like to perform some handling of the obtained data using other means between such launches? We will attempt to add the ability to create new optimization stages performed by programs written in Python.

Chaos theory in trading (Part 1): Introduction, application in financial markets and Lyapunov exponent
Can chaos theory be applied to financial markets? In this article, we will consider how conventional Chaos theory and chaotic systems are different from the concept proposed by Bill Williams.


Population optimization algorithms: Stochastic Diffusion Search (SDS)
The article discusses Stochastic Diffusion Search (SDS), which is a very powerful and efficient optimization algorithm based on the principles of random walk. The algorithm allows finding optimal solutions in complex multidimensional spaces, while featuring a high speed of convergence and the ability to avoid local extrema.

Category Theory in MQL5 (Part 15) : Functors with Graphs
This article on Category Theory implementation in MQL5, continues the series by looking at Functors but this time as a bridge between Graphs and a set. We revisit calendar data, and despite its limitations in Strategy Tester use, make the case using functors in forecasting volatility with the help of correlation.


Price Action Analysis Toolkit Development (Part 57): Developing a Market State Classification Module in MQL5
This article develops a market state classification module for MQL5 that interprets price behavior using completed price data. By examining volatility contraction, expansion, and structural consistency, the tool classifies market conditions as compression, transition, expansion, or trend, providing a clear contextual framework for price action analysis.

Population optimization algorithms: Artificial Bee Colony (ABC)
In this article, we will study the algorithm of an artificial bee colony and supplement our knowledge with new principles of studying functional spaces. In this article, I will showcase my interpretation of the classic version of the algorithm.


Developing a multi-currency Expert Advisor (Part 5): Variable position sizes
In the previous parts, the Expert Advisor (EA) under development was able to use only a fixed position size for trading. This is acceptable for testing, but is not advisable when trading on a real account. Let's make it possible to trade using variable position sizes.


Testing Visualization: Account State Charts
Enjoy the process of testing with charts, displaying the balance - now all the necessary information is always in view!


Building a Candlestick Trend Constraint Model (Part 10): Strategic Golden and Death Cross (EA)
Did you know that the Golden Cross and Death Cross strategies, based on moving average crossovers, are some of the most reliable indicators for identifying long-term market trends? A Golden Cross signals a bullish trend when a shorter moving average crosses above a longer one, while a Death Cross indicates a bearish trend when the shorter average moves below. Despite their simplicity and effectiveness, manually applying these strategies often leads to missed opportunities or delayed trades.


Building A Candlestick Trend Constraint Model (Part 8): Expert Advisor Development (II)
Think about an independent Expert Advisor. Previously, we discussed an indicator-based Expert Advisor that also partnered with an independent script for drawing risk and reward geometry. Today, we will discuss the architecture of an MQL5 Expert Advisor, that integrates, all the features in one program.


Using Deep Reinforcement Learning to Enhance Ilan Expert Advisor
We revisit the Ilan grid Expert Advisor and integrate Q-learning in MQL5 to build an adaptive version for MetaTrader 5. The article shows how to define state features, discretize them for a Q-table, select actions with ε-greedy, and shape rewards for averaging and exits. You will implement saving/loading the Q-table, tune learning parameters, and test on EURUSD/AUDUSD in the Strategy Tester to evaluate stability and drawdown risks.


GIT: What is it?
In this article, I will introduce a very important tool for developers. If you are not familiar with GIT, read this article to get an idea of what it is and how to use it with MQL5.

Population optimization algorithms: Cuckoo Optimization Algorithm (COA)
The next algorithm I will consider is cuckoo search optimization using Levy flights. This is one of the latest optimization algorithms and a new leader in the leaderboard.


Automating Market Entropy Indicator: Trading System Based on Information Theory
This article presents an EA that automates the previously introduced Market Entropy methodology. It computes fast and slow entropy, momentum, and compression states, validates signals, and executes orders with SL/TP and optional position reversal. The result is a practical, configurable tool that applies information-theoretic signals without manual interpretation.

From "Best Pass" to Robust Solutions: Exploring the Optimization Surface in MetaTrader 5
The article examines an engineering approach to optimizing an Expert Advisor in MetaTrader 5: from collecting custom metrics through Optimization Frames to parameter surface analysis. A simple event-driven EMA/RSI model demonstrates CSV export, smoothing, and local stability assessment in Python. The goal is to find stable areas of configurations and validate them with forward optimization for reliable implementation.


Formulating Dynamic Multi-Pair EA (Part 2): Portfolio Diversification and Optimization
Portfolio Diversification and Optimization strategically spreads investments across multiple assets to minimize risk while selecting the ideal asset mix to maximize returns based on risk-adjusted performance metrics.


Market Simulation (Part 15): Sockets (IX)
In this article, we will discuss one of the possible solutions to what we have been trying to demonstrate—namely, how to allow an Excel user to perform an action in MetaTrader 5 without sending orders or opening or closing positions. The idea is that the user employs Excel to conduct fundamental analysis of a particular symbol. And by using only Excel, they can instruct an expert advisor running in MetaTrader 5 to open or close a specific position.

Billiards Optimization Algorithm (BOA)
The BOA method is inspired by the classic game of billiards and simulates the search for optimal solutions as a game with balls trying to fall into pockets representing the best results. In this article, we will consider the basics of BOA, its mathematical model, and its efficiency in solving various optimization problems.


Population optimization algorithms: Nelder–Mead, or simplex search (NM) method
The article presents a complete exploration of the Nelder-Mead method, explaining how the simplex (function parameter space) is modified and rearranged at each iteration to achieve an optimal solution, and describes how the method can be improved.

Trading with the MQL5 Economic Calendar (Part 7): Preparing for Strategy Testing with Resource-Based News Event Analysis
In this article, we prepare our MQL5 trading system for strategy testing by embedding economic calendar data as a resource for non-live analysis. We implement event loading and filtering for time, currency, and impact, then validate it in the Strategy Tester. This enables effective backtesting of news-driven strategies.

Estimate future performance with confidence intervals
In this article we delve into the application of boostrapping techniques as a means to estimate the future performance of an automated strategy.

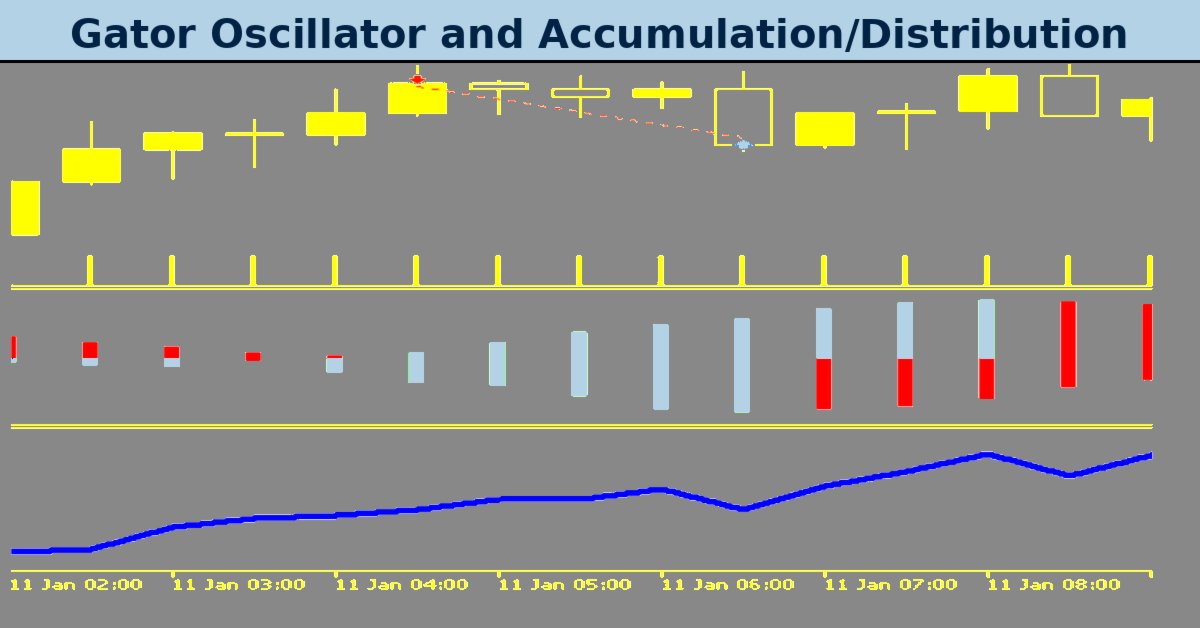
MQL5 Wizard Techniques you should know (Part 77): Using Gator Oscillator and the Accumulation/Distribution Oscillator
The Gator Oscillator by Bill Williams and the Accumulation/Distribution Oscillator are another indicator pairing that could be used harmoniously within an MQL5 Expert Advisor. We use the Gator Oscillator for its ability to affirm trends, while the A/D is used to provide confirmation of the trends via checks on volume. In exploring this indicator pairing, as always, we use the MQL5 wizard to build and test out their potential.


Developing a multi-currency Expert Advisor (Part 21): Preparing for an important experiment and optimizing the code
For further progress it would be good to see if we can improve the results by periodically re-running the automatic optimization and generating a new EA. The stumbling block in many debates about the use of parameter optimization is the question of how long the obtained parameters can be used for trading in the future period while maintaining the profitability and drawdown at the specified levels. And is it even possible to do this?


Developing a Replay System (Part 59): A New Future
Having a proper understanding of different ideas allows us to do more with less effort. In this article, we'll look at why it's necessary to configure a template before the service can interact with the chart. Also, what if we improve the mouse pointer so we can do more things with it?


Population optimization algorithms: Saplings Sowing and Growing up (SSG)
Saplings Sowing and Growing up (SSG) algorithm is inspired by one of the most resilient organisms on the planet demonstrating outstanding capability for survival in a wide variety of conditions.


MetaTrader 5: Build a Market to Suit Your Strategy — Renko/Range/Volume, Synthetics, and Stress Tests on Custom Symbols
In this article, we demonstrate how to use API of the MetaTrader 5 custom symbols to transform your terminal into a data constructor for generating timeless Renko, Range, and Equal-Volume charts and assembling synthetic instruments. We will analyze tick aggregation and history modification for stress tests (spread widening, stop level changes) taking into account platform limitations. Besides, you will get some practice of handling CiCustomSymbol and routing orders to a real symbol through the CustomOrder wrapper with ready-made code fragments.


Implementing the Truncated Newton Conjugate-Gradient Algorithm in MQL5
This article implements a box‑constrained Truncated Newton Conjugate‑Gradient (TNC) optimizer in MQL5 and details its core components: scaling, projection to bounds, line search, and Hessian‑vector products via finite differences. It provides an objective wrapper supporting analytic or numerical derivatives and validates the solver on the Rosenbrock benchmark. A logistic regression example shows how to use TNC as a drop‑in alternative to LBFGS.

Atomic Orbital Search (AOS) algorithm: Modification
In the second part of the article, we will continue developing a modified version of the AOS (Atomic Orbital Search) algorithm focusing on specific operators to improve its efficiency and adaptability. After analyzing the fundamentals and mechanics of the algorithm, we will discuss ideas for improving its performance and the ability to analyze complex solution spaces, proposing new approaches to extend its functionality as an optimization tool.


Developing a Replay System — Market simulation (Part 17): Ticks and more ticks (I)
Here we will see how to implement something really interesting, but at the same time very difficult due to certain points that can be very confusing. The worst thing that can happen is that some traders who consider themselves professionals do not know anything about the importance of these concepts in the capital market. Well, although we focus here on programming, understanding some of the issues involved in market trading is paramount to what we are going to implement.

A New Approach to Custom Criteria in Optimizations (Part 1): Examples of Activation Functions
The first of a series of articles looking at the mathematics of Custom Criteria with a specific focus on non-linear functions used in Neural Networks, MQL5 code for implementation and the use of targeted and correctional offsets.


Developing a Multi-Currency Advisor (Part 27): Component for Displaying Multi-Line Text
If there is a need to display text on a chart, we can use the Comment() function. But its capabilities are quite limited. Therefore, in this article, we will create our own component - a full-screen dialog window capable of displaying multi-line text with flexible font settings and scrolling support.


Custom Indicator: Plotting Partial Entry, Exit and Reversal Deals for Netting Accounts
In this article, we will look at a non-standard way of creating an indicator in MQL5. Instead of focusing on a trend or chart pattern, our goal will be to manage our own positions, including partial entries and exits. We will make extensive use of dynamic matrices and some trading functions related to trade history and open positions to indicate on the chart where these trades were made.

From Novice to Expert: The Essential Journey Through MQL5 Trading
Unlock your potential! You're surrounded by opportunities. Discover 3 top secrets to kickstart your MQL5 journey or take it to the next level. Let's dive into discussion of tips and tricks for beginners and pros alike.

Developing a Replay System (Part 27): Expert Advisor project — C_Mouse class (I)
In this article we will implement the C_Mouse class. It provides the ability to program at the highest level. However, talking about high-level or low-level programming languages is not about including obscene words or jargon in the code. It's the other way around. When we talk about high-level or low-level programming, we mean how easy or difficult the code is for other programmers to understand.


Category Theory in MQL5 (Part 13): Calendar Events with Database Schemas
This article, that follows Category Theory implementation of Orders in MQL5, considers how database schemas can be incorporated for classification in MQL5. We take an introductory look at how database schema concepts could be married with category theory when identifying trade relevant text(string) information. Calendar events are the focus.


Developing a Replay System (Part 74): New Chart Trade (I)
In this article, we will modify the last code shown in this series about Chart Trade. These changes are necessary to adapt the code to the current replay/simulation system model. The content presented here is intended solely for educational purposes. Under no circumstances should the application be viewed for any purpose other than to learn and master the concepts presented.


MQL5 Wizard Techniques you should know (Part 37): Gaussian Process Regression with Linear and Matérn Kernels
Linear Kernels are the simplest matrix of its kind used in machine learning for linear regression and support vector machines. The Matérn kernel on the other hand is a more versatile version of the Radial Basis Function we looked at in an earlier article, and it is adept at mapping functions that are not as smooth as the RBF would assume. We build a custom signal class that utilizes both kernels in forecasting long and short conditions.


Developing a Multi-Currency Expert Advisor (Part 29): Improving the Conveyor
We are going to improve the usability of the automated optimization conveyor: we will explore the process from creating an optimization project to testing the final EA. For clarity, let us walk through the entire process step by step creating the final EA, while stopping to make any desired corrections.