Articles on trading system automation in MQL5

Read articles on the trading systems with a wide variety of ideas at the core. Learn how to use statistical methods and patterns on candlestick charts, how to filter signals and where to use semaphore indicators.
The MQL5 Wizard will help you create robots without programming to quickly check your trading ideas. Use the Wizard to learn about genetic algorithms.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

MQL5 Wizard Techniques you should know (Part 30): Spotlight on Batch-Normalization in Machine Learning
Batch normalization is the pre-processing of data before it is fed into a machine learning algorithm, like a neural network. This is always done while being mindful of the type of Activation to be used by the algorithm. We therefore explore the different approaches that one can take in reaping the benefits of this, with the help of a wizard assembled Expert Advisor.

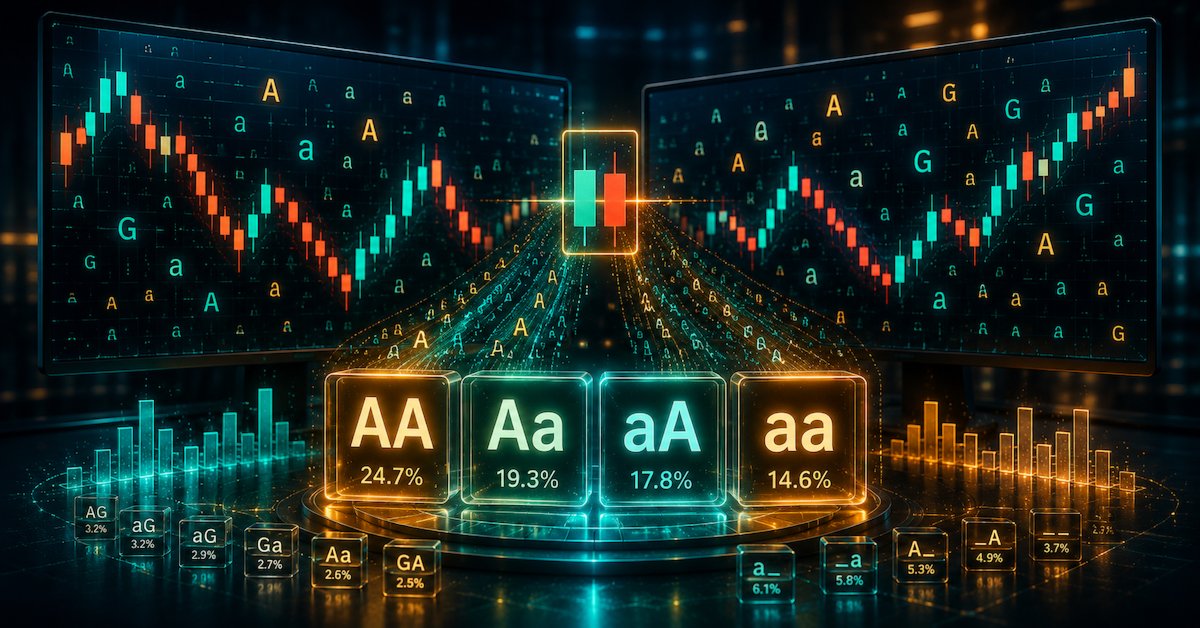
Encoding Candlestick Patterns (Part 4): Frequency Analysis for Double-Candlestick Structures
This article extends single-candlestick analysis to ordered double-candlestick patterns using an MQL5 script. The script encodes candles into symbols, extracts every consecutive two-symbol sequence (treating Aa and aA as different), counts occurrences and percentages, and writes sorted frequency tables to a text file. Readers can quickly identify the most recurrent transitions by symbol, timeframe, and lookback for further statistical testing.


Neural Networks in Trading: An Intelligent Forecast Pipeline (Conclusion)
The article provides a fascinating look at how SwiGLU embedding reveals hidden market patterns, and how a sparse Mixture of Experts within a Decoder-Only Transformer makes forecasts more accurate at reasonable computational cost. We take an in-depth look at the integration of Time‑MoE into MQL5 and OpenCL, and provide a step-by-step guide to configuring and training the model.


MQL5 Wizard Techniques you should know (Part 97): Using Convex Hull and a miniature GRU Network in a Custom Trailing Stop Class
For this article we look at a custom MQL5 Wizard class for Trailing Stops. Our implemented custom class ‘CTrailingConvexHullGRU’, is built from merging the Convex Hull algorithm with a GRU network. As always we seek to develop a model that is testable with MQL5 Wizard-Assembled Expert Advisors and can be tuned with various Money Management and entry Signals classes. Our testing is with the 'Envelopes' and the RSI classes for Signal.


Neural Networks in Trading: Hierarchical Skill Discovery for Adaptive Agent Behavior (HiSSD)
In this article, we explore the HiSSD framework, which combines hierarchical learning and multi-agent approaches to create adaptive systems. We examine in detail how this innovative methodology helps uncover hidden patterns in financial markets and optimize trading strategies in decentralized environments.


Mapping the Shape of Price: The Mapper Lens and Cover in MQL5
The article introduces the Mapper pipeline in MQL5 by implementing the two fundamental components: CTDAMapperFilter (lens) and CTDAMapperCover (overlapping intervals). It explains three lens options—eccentricity, density, and coordinate—plus cover parameters (resolution and gain), and demonstrates how a price point cloud is reduced to one value per point and interval memberships. Readers obtain ready inputs for subsequent clustering and graph construction.


Neural Networks in Trading: Effective Feature Extraction for Accurate Classification (Building Objects)
Mantis is a versatile tool for in-depth time series analysis that can be flexibly scaled to accommodate any financial scenario. Learn how a combination of patching, local convolutions, and cross-attention enables a highly accurate interpretation of market patterns.


Developing a Replay System (Part 58): Returning to Work on the Service
After a break in development and improvement of the service used for replay/simulator, we are resuming work on it. Now that we've abandoned the use of resources like terminal globals, we'll have to completely restructure some parts of it. Don't worry, this process will be explained in detail so that everyone can follow the development of our service.


Neural Networks in Trading: Heterogeneity-Informed Meta-Parameter Learning (HimNet)
We invite you to explore the HimNet framework, which combines the flexibility of spatio-temporal adaptation with high computational efficiency, enabling accurate and stable forecasts for financial time series. The article explains in detail how its key components interact with one another, transforming complex algorithms into a manageable architecture.


Beyond GARCH (Part VIII): The MMAR Library And Putting it to Work in an Expert Advisor
This article finalizes the MMAR project with a CMMAR facade class and a demo Expert Advisor for MetaTrader 5. The facade exposes a compact API—configure, Fit(), Forecast()—that wraps partition analysis, spectrum fitting and Monte Carlo simulation. You will learn how to load data, fit the model and obtain a volatility forecast, with diagnostics and status handling for robust use in EAs.


Neural Networks in Trading: The Adaptive Graph Diffusion Model (Conclusion)
In this article, we conclude our work on building the SAGDFN framework using MQL5, summarizing the development process and presenting the results of its practical testing. Let's combine the modules we've already implemented into a single system, highlight the strengths of this approach, point out its weaknesses, and discuss possible ways to improve it.


Neural Networks in Trading: A Unified View of Space and Time (Global-Local Attention)
We are continuing our work on implementing the approaches proposed by the authors of the Extralonger framework. This time, we will focus on building a Global-Local Spatial Attention module using MQL5, examining both its structure and its practical integration into the overall computational process.


Trading with the MQL5 Economic Calendar (Part 12): SQLite Storage and Deduplication
In this article, we replace the embedded CSV snapshot with a SQLite layer that persists calendar events and triggered trade IDs across restarts. The database lives in the common terminal folder and is shared by live charts and the strategy tester, so both modes read the same data without recompiling. An on-demand downloader with a canvas progress bar fetches history from the calendar API and stores it for offline reuse.


Beyond GARCH (Part III): Building the MMAR and the Verdict
With the multifractal parameters from Part 2 in hand, this article builds the full MMAR process. We construct the multiplicative cascade for trading time, generate Fractional Brownian Motion via Davies-Harte FFT, and combine both into X(t) = B_H[theta(t)]. A 1000-path Monte Carlo simulation produces the volatility forecast, which we then pit against GARCH on the same EURUSD M5 data. Does Mandelbrot's fractal architecture outforecast Engle's conditional variance framework? Part 3 of a eight-part series leading to a native MQL5 library and Expert Advisor.


Institutional-Grade Multi-Currency Portfolio Engine in MQL5 (Part 1): Architecture of a Multi-Currency EA Framework
The article details a master–agent MQL5 framework that mitigates cross-symbol risk concentration. A single Portfolio Controller publishes risk limits and halt flags to Instrument Agents through shared channels and a readiness flag, while agents size orders only within the published budget. It contrasts global variables, named pipes, and files, and clarifies timer intervals and latency so data allocation may be up to one cycle stale without breaking coordination.


Neural Networks in Trading: Generalizing Time Series Without Data-Specific Dependence (Conclusion)
The article will show you how Mamba4Cast turns theory into a working trading algorithm and lays the groundwork for your own experiments. Do not miss this opportunity to gain a full range of knowledge and inspiration for developing your own strategy.


Building a Position Lifecycle Manager in MQL5 (Part 1): The Foundation of Reusable Position Management
A state-driven Position Lifecycle Manager brings structure to post-entry trade handling in MetaTrader 5. It discovers open positions, tracks them via managed objects, applies ATR-based protection, executes break-even transitions, and removes completed trades, with a clear NEW → PROTECTED → BREAKEVEN → CLOSED flow. The article shows integration with the standard MACD EA to enable reuse across strategies.


MetaTrader 5 Machine Learning Blueprint (Part 19): Bagging Regimes
We test AFML's claim that the sequential bootstrap decorrelates bagged trees on overlapping triple‑barrier labels by isolating two levers: draw count and draw rule. One decision identical tree is bagged under four row‑sampling regimes and evaluated on EURUSD 2022–2023 for draw uniqueness, between‑tree correlation, AUC, and calibration. Decorrelation comes almost entirely from throttling max_samples to average uniqueness; the sequential draw adds little. Out-of-bag inflation is largest under full-count sequential sampling.


MQL5 Wizard Techniques you should know (Part 100): Sliding Window Median and Bidirectional LSTM for a Custom Trailing Stop
CTrailingSlidingMedianBiLSTM is a custom MQL5 Wizard trailing module that combines robust median/MAD outlier filtering with a BiLSTM context score in the range [-1, 1]. Four algorithm modes (standard, bands, RSI, adaptive) target noise, mean-reverting bursts and liquidity spikes, reducing premature stop adjustments. This module is intended for side-by-side evaluation with diverse entry signals and money management settings.


Automating Classic Market Methods in MQL5 (Part 6): Jesse Livermore's Pivotal Point System
This article presents a complete MQL5 Expert Advisor that implements Jesse Livermore's market key as a deterministic state machine. It detects pivotal levels from consolidations using ATR and volume expansion, scales in across four tranches, and exits on abnormal behavior defined by range and volume. The EA validates inputs in OnInit, requires a hedging account, and compiles out of the box for testing Livermore's rules on daily data.


MetaTrader 5 Machine Learning Blueprint (Part 18): Sequential Bootstrap, Corrected — Clone, Class Erasure, and the Comparison Toolkit
The article diagnoses two defects that neutralize sequential bootstrap during cross‑validation: type erasure of SequentiallyBootstrappedBaggingClassifier and a fold‑level shape mismatch from cloning full samples info sets. It retains the classifier's identity, adds find seq bagging to re‑inject fold‑sliced t1 in CalibratorCV.fit, and resets state per split. A new bootstrap_comparison module reports OOF and OOB metrics and memory, letting you verify that sequential sampling is applied correctly and quantify its impact.


Automating Classic Market Methods in MQL5 (Part 7): The Nicolas Darvas Box System
This article implements the Darvas Box method as a complete MQL5 Expert Advisor. We code box detection with a three-session hold, volume contraction during consolidation, and volume-confirmed breakouts, plus a staircase pyramid with a shared, rolling stop at the latest box floor. The EA uses a state machine to run box scanning and trade management in parallel, providing a ready-to-compile system with configurable inputs and clear on-chart diagnostics.


Engineering Trading Discipline into Code (Part 8): Building a Setup Confirmation and Trade Authorization Layer in MQL5
This article introduces an MQL5 trade authorization framework built around CDisciplineLayer, CDisciplineGuardian, and CDisciplinePanel. The framework manages setup lifecycles, signal freshness, session restrictions, setup expiry, and global trading locks through a centralized authorization layer. It also provides automated enforcement of violations and a real-time dashboard, enabling consistent trade validation and monitoring before and after execution.


Exporting MetaTrader 5 Open Positions to a Live-Refreshing HTML Dashboard
The article builds an MQL5 Expert Advisor that writes a self-refreshing HTML positions dashboard to MQL5/Files on every tick, so you can monitor open trades in any browser. It covers reading live position data, generating a complete page with inline CSS and a JavaScript reload timer, and writing the file atomically. The design escapes HTML in comments, shows an explicit empty state, and writes a clear offline page on EA shutdown.


MQL5 Wizard Techniques you should know (Part 98): Using an Unscented Kalman Filter and a Capsule Network in a Custom Signal Class
This article presents 'CSignalUKFCapsNet', as a custom class coded in MQL5. This class is meant to be used with the MQL5 Wizard when assembling an Expert Advisor and when selected in the Wizard it defines the Expert Advisor's entry signals. In building this custom class, we brought together the algorithm Unscented Kalman Filter and the Capsule Neural Network. Our algorithm is showcased with four operation modes, and the coding of this as a custom class for the MQL5 Wizard, allows testing with various Trailing Stop methods and Money Management systems.


MQL5 Trading Tools (Part 36): Adding Shape and Annotation Tools with In-Place Label Editing to the Canvas Drawing Layer
We add eight shape tools and nine annotation tools to the canvas and implement a full in-place label-editing system. The article walks through geometry, AA rendering, shared word-wrap and supersampled text helpers, and the caret-driven state machine for typing, navigation, and selection. This yields a complete, consistent annotation toolkit with editable labels that plugs into the prior interaction pipeline.


Adaptive Spread Monitoring and Order Gating in MQL5
This article presents a distribution-adaptive spread monitor for MQL5 that replaces fixed thresholds with a rolling histogram of each symbol's recent spread. It explains percentile estimation from bins, a four-state GREEN/YELLOW/RED/WARMING classification, and a CCanvas dashboard rendered from real histogram data. You will get a ready workflow for per-symbol order gating and controlled alerting via arm/disarm hysteresis plus cooldown, with a verification script and clear calibration and resolution limits.


Neural Networks in Trading: Effective Feature Extraction for Accurate Classification (Final Part)
The Mantis framework transforms complex time series into informative tokens and serves as a reliable foundation for an intelligent trading agent capable of operating in real time.


Measuring Market Efficiency with Lempel-Ziv Complexity
This article presents a compact MQL5 library for market-complexity analysis: LZ76 complexity and Normalized Compression Distance built on a SAX symbolizer, exposed through a simple facade and an efficiency indicator. It explains the discretization choices, normalization, and distance formulation, and validates the code with unit checks and an independent cross-check. You get a ready-to-use library and indicator, plus a disciplined way to interpret readings with a shuffle null and a direction check.


Building a Trade Analytics System (Part 3): Storing MetaTrader 5 Trades in SQLite
This article extends a Flask backend to reliably receive, validate, and store closed trade data from MetaTrader 5 using SQLite and Flask‑SQLAlchemy. It implements required‑field checks, timestamp conversion, transaction‑safe persistence, and working retrieval endpoints for all trades and single records, plus a basic summary. The result is a complete data pipeline with local testing that records trades and exposes them through a structured API for further analysis.


Neural Networks in Trading: Decomposition Instead of Scaling (SSCNN)
In this article, we begin our exploration of the SSCNN framework — a modern architectural solution for time series analysis that combines accuracy, a structured design, and high computational efficiency. We will systematically examine its theoretical aspects, highlight the key differences from its predecessors, and begin the practical implementation of its basic components in the MQL5 environment.


Bonobo Optimizer (BO)
The article presents the implementation and analysis of the Bonobo Optimizer algorithm, which is based on the unique behavioral characteristics of bonobos — their dynamic fission-fusion social structure and three mating strategies. What interesting features does this method have?


Cross Recurrence Quantification Analysis (CRQA) in MQL5: Building a Complete Analysis Library
This article extends the MQL5 RQA library to Cross-Recurrence Quantification Analysis (CRQA) for comparing two time series. We implement dual‑series embedding, cross‑recurrence matrix construction, adapted metrics (CRR, CDET, CLAM, CENTR, and others), and rolling‑window analysis, with optional GPU acceleration via OpenCL. A ready-to-use indicator compares two symbols in real time, supporting timestamp alignment and normalization for practical inter-market analysis.


Neural Networks in Trading: Disentangling Structured Components (Conclusion)
The article provides a detailed explanation of the SCNN architecture and one way to implement it using MQL5. We will show how time series decomposition can be combined with neural network methods and attention mechanisms.


Designing a Unified Order Execution Gateway Class in MQL5
This class provides one point of contact for trade operations in MQL5. It rounds and clamps lot sizes, validates SL/TP against the broker's minimum distance, resolves a compatible filling policy, and applies bounded retries for transient retcodes. Calls return a structured CGatewayResult instead of raw retcodes, simplifying error handling and maintenance across strategies.


Network Momentum for MetaTrader5: Trading the Lead-Lag Graph Between Markets
This article builds a trend-following Expert Advisor that trades momentum spillover across markets, implemented fully in MQL5 without external solvers. It detects leaders with Derivative Dynamic Time Warping, learns a sparse weighted network by convex optimization, and propagates momentum through it with a reverting response. Readers get a step-by-step, reproducible pipeline and a working EA ready to run in the Strategy Tester.


Market Simulation: Getting started with SQL in MQL5 (IV)
Many people tend to underestimate SQL, or even not use it at all, because they do not fully understand how it actually works. When running queries against an SQL database, we are not always looking for a universal answer; in some cases, we need a very specific and practical answer. If a database is created with a proper structure and data model, almost any type of information can be integrated into it.


Lazy-Loading Indicator Handles in MQL5: A Resource Manager Pattern for Multi-Timeframe EAs
Multi‑timeframe EAs that initialize every indicator handle in OnInit() pay a fixed startup cost even when most handles are never used. CIndicatorCache applies lazy loading with composite‑key lookup, reference‑counted Acquire/Release, and a deterministic FlushAll() for cleanup. Handles are created on first request and reused across ticks, reducing startup latency, avoiding repeated heap allocation, and preventing terminal resource leaks through centralized ownership.


Building Your Personal Expert Advisor (Part 2): Risk Management and Dynamic Lot Sizing
This part implements risk-based position sizing for the EA. Lot size is derived from account balance, a chosen risk percent, and ATR-based stop distance, then confined and rounded to the broker's volume rules and minimum stop levels. An optional drawdown-aware layer reduces risk during equity declines. Readers get a reproducible sizing function that keeps per-trade risk consistent and orders acceptable to the server.


Implementing the Decorator Pattern in MQL5: Adding Logging, Timing, and Filtering to Any Indicator Non-Invasively
Cross-cutting concerns like logging, timing, and threshold filtering should not live inside indicator classes. We show how to apply the decorator pattern in MQL5 with a shared IIndicator interface, an owning CBaseDecorator, and concrete CLoggingDecorator, CTimingDecorator, and CThresholdFilterDecorator layers. You can stack behaviors per EA, keep computation code closed to modification, and get deterministic cleanup by deleting only the outermost decorator.