Articles on machine learning in trading

Creating AI-based trading robots: native integration with Python, matrices and vectors, math and statistics libraries and much more.
Find out how to use machine learning in trading. Neurons, perceptrons, convolutional and recurrent networks, predictive models — start with the basics and work your way up to developing your own AI. You will learn how to train and apply neural networks for algorithmic trading in financial markets.
Add a new article

You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration
Log in
You agree to website policy and terms of use
If you do not have an account, please register

Central Force Optimization (CFO) algorithm
The article presents the Central Force Optimization (CFO) algorithm inspired by the laws of gravity. It explores how principles of physical attraction can solve optimization problems where "heavier" solutions attract less successful counterparts.


Chaos optimization algorithm (COA): Continued
We continue studying the chaotic optimization algorithm. The second part of the article deals with the practical aspects of the algorithm implementation, its testing and conclusions.


Extremal Optimization (EO)
The article discusses the Extremal Optimization (EO) algorithm, an optimization method inspired by the Bak-Sneppen self-organized criticality model, where evolution occurs through the elimination of the worst-case components of the system. The modified population version of the algorithm demonstrates a shift away from theoretical principles in favor of practical efficiency, leading to the creation of powerful computational tools.

MQL5 Wizard Techniques you should know (Part 68): Using Patterns of TRIX and the Williams Percent Range with a Cosine Kernel Network
We follow up our last article, where we introduced the indicator pair of TRIX and Williams Percent Range, by considering how this indicator pairing could be extended with Machine Learning. TRIX and William’s Percent are a trend and support/ resistance complimentary pairing. Our machine learning approach uses a convolution neural network that engages the cosine kernel in its architecture when fine-tuning the forecasts of this indicator pairing. As always, this is done in a custom signal class file that works with the MQL5 wizard to assemble an Expert Advisor.

Analyzing binary code of prices on the exchange (Part I): A new look at technical analysis
This article presents an innovative approach to technical analysis based on converting price movements into binary code. The author demonstrates how various aspects of market behavior — from simple price movements to complex patterns — can be encoded in a sequence of zeros and ones.

MQL5 Wizard Techniques You Should Know (Part 15): Support Vector Machines with Newton's Polynomial
Support Vector Machines classify data based on predefined classes by exploring the effects of increasing its dimensionality. It is a supervised learning method that is fairly complex given its potential to deal with multi-dimensioned data. For this article we consider how it’s very basic implementation of 2-dimensioned data can be done more efficiently with Newton’s Polynomial when classifying price-action.

Ordinal Encoding for Nominal Variables
In this article, we discuss and demonstrate how to convert nominal predictors into numerical formats that are suitable for machine learning algorithms, using both Python and MQL5.


Feature Engineering for ML (Part 4): Implementing Time Features in MQL5
Applying Python session boundaries to MQL5 broker timestamps misclassifies session membership by two to three hours on any non-UTC broker, corrupting session flags across the full backtest history. We implement CTimeFeatures.mqh, containing CRingBuffer and CTimeFeatures, with three EA-facing methods: Initialize (UTC offset capture and frequency gate configuration), Update (log return push to session-conditional ring buffers), and Calculate (cyclical encoding, session flags, and session volatility). The output is a flat double array drop-compatible with Python's get_time_features for sub-hourly, hourly, and daily timeframes.


Overcoming The Limitation of Machine Learning (Part 4): Overcoming Irreducible Error Using Multiple Forecast Horizons
Machine learning is often viewed through statistical or linear algebraic lenses, but this article emphasizes a geometric perspective of model predictions. It demonstrates that models do not truly approximate the target but rather map it onto a new coordinate system, creating an inherent misalignment that results in irreducible error. The article proposes that multi-step predictions, comparing the model’s forecasts across different horizons, offer a more effective approach than direct comparisons with the target. By applying this method to a trading model, the article demonstrates significant improvements in profitability and accuracy without changing the underlying model.

Artificial Tribe Algorithm (ATA)
The article provides a detailed discussion of the key components and innovations of the ATA optimization algorithm, which is an evolutionary method with a unique dual behavior system that adapts depending on the situation. ATA combines individual and social learning while using crossover for explorations and migration to find solutions when stuck in local optima.

Applying Localized Feature Selection in Python and MQL5
This article explores a feature selection algorithm introduced in the paper 'Local Feature Selection for Data Classification' by Narges Armanfard et al. The algorithm is implemented in Python to build binary classifier models that can be integrated with MetaTrader 5 applications for inference.


Neural network trading EA based on PatchTST
The article presents the revolutionary architecture of PatchTST, a tailored transformer for financial time series analysis that breaks market data into 16-bar patches for efficient processing. We will discuss the full implementation of a trading robot in MQL5 covering everything from mathematical fundamentals and data structures to a ready-made EA with risk management and continuous learning systems.

Category Theory in MQL5 (Part 12): Orders
This article which is part of a series that follows Category Theory implementation of Graphs in MQL5, delves in Orders. We examine how concepts of Order-Theory can support monoid sets in informing trade decisions by considering two major ordering types.


Detecting and Classifying Fractal Patterns Using Machine Learning
In this article, we will touch upon the intriguing topic of fractal analysis and market forecasting using machine learning. These are just the first steps towards exploring the diverse fractal structures that form on financial price charts. We will use the correlation to find patterns and the CatBoost algorithm to classify these patterns.

Neuroboids Optimization Algorithm 2 (NOA2)
The new proprietary optimization algorithm NOA2 (Neuroboids Optimization Algorithm 2) combines the principles of swarm intelligence with neural control. NOA2 combines the mechanics of a neuroboid swarm with an adaptive neural system that allows agents to self-correct their behavior while searching for the optimum. The algorithm is under active development and demonstrates potential for solving complex optimization problems.


Bivariate Copulae in MQL5 (Part 1): Implementing Gaussian and Student's t-Copulae for Dependency Modeling
This is the first part of an article series presenting the implementation of bivariate copulae in MQL5. This article presents code implementing Gaussian and Student's t-copulae. It also delves into the fundamentals of statistical copulae and related topics. The code is based on the Arbitragelab Python package by Hudson and Thames.


Analyzing weather impact on currencies of agricultural countries using Python
What is the relationship between weather and Forex? Classical economic theory has long ignored the influence of such factors as weather on market behavior. But everything has changed. Let's try to find connections between the weather conditions and the position of agricultural currencies on the market.


Population optimization algorithms: Evolution of Social Groups (ESG)
We will consider the principle of constructing multi-population algorithms. As an example of this type of algorithm, we will have a look at the new custom algorithm - Evolution of Social Groups (ESG). We will analyze the basic concepts, population interaction mechanisms and advantages of this algorithm, as well as examine its performance in optimization problems.

Neural Networks in Trading: Reducing Memory Consumption with Adam-mini Optimization
One of the directions for increasing the efficiency of the model training and convergence process is the improvement of optimization methods. Adam-mini is an adaptive optimization method designed to improve on the basic Adam algorithm.

Example of Causality Network Analysis (CNA) and Vector Auto-Regression Model for Market Event Prediction
This article presents a comprehensive guide to implementing a sophisticated trading system using Causality Network Analysis (CNA) and Vector Autoregression (VAR) in MQL5. It covers the theoretical background of these methods, provides detailed explanations of key functions in the trading algorithm, and includes example code for implementation.

Role of random number generator quality in the efficiency of optimization algorithms
In this article, we will look at the Mersenne Twister random number generator and compare it with the standard one in MQL5. We will also find out the influence of the random number generator quality on the results of optimization algorithms.


Neuro-Structural Trading Engine — NSTE (Part II): Jardine's Gate Six-Gate Quantum Filter
This article introduces Jardine's Gate, a six-gate orthogonal signal filter for MetaTrader 5 that validates LSTM predictions across entropy, expert interference, confidence, regime-adjusted probability, trend direction, and consecutive-loss kill switch dimensions. Out of 43,200 raw signals per month, only 127 pass all six gates. Readers get the complete QuantumEdgeFilter MQL5 class, threshold calibration logic, and gate performance analytics.


Beyond the Clock (Part 4): Efficacy of Bars on Trending and Mean-Reversion Strategies
Does better return conditioning buy strategy performance? We hold bar count fixed across time, tick, tick-imbalance, and tick-runs on 60.5 million EURUSD ticks, then meta-label RSI, Bollinger, and ADX/DI entries and score with purged cross-validation. No family delivers a consistent edge; efficacy varies narrowly and the best case fails a permutation test. Readers learn how to control overlap, leakage, and multiple testing in bar studies.


Distribution-Free Price Channels in MQL5: Quantile Regression by Iteratively Reweighted Least Squares
We build a rolling price channel by fitting the 0.1, 0.5 and 0.9 conditional quantile lines via IRLS with pinball loss, packaged as a reusable class and two MetaTrader 5 indicators. We verify in-sample coverage, examine quantile crossing, and compare the channel width with ATR, Bollinger and regression widths on matched horizons. Tests in the Strategy Tester show the edges are descriptive, while the normalized width works as a volatility/regime feature.

MQL5 Wizard Techniques you should know (Part 54): Reinforcement Learning with hybrid SAC and Tensors
Soft Actor Critic is a Reinforcement Learning algorithm that we looked at in a previous article, where we also introduced python and ONNX to these series as efficient approaches to training networks. We revisit the algorithm with the aim of exploiting tensors, computational graphs that are often exploited in Python.


MQL5 Wizard Techniques you should know (Part 47): Reinforcement Learning with Temporal Difference
Temporal Difference is another algorithm in reinforcement learning that updates Q-Values basing on the difference between predicted and actual rewards during agent training. It specifically dwells on updating Q-Values without minding their state-action pairing. We therefore look to see how to apply this, as we have with previous articles, in a wizard assembled Expert Advisor.

Bacterial Chemotaxis Optimization (BCO)
The article presents the original version of the Bacterial Chemotaxis Optimization (BCO) algorithm and its modified version. We will take a closer look at all the differences, with a special focus on the new version of BCOm, which simplifies the bacterial movement mechanism, reduces the dependence on positional history, and uses simpler math than the computationally heavy original version. We will also conduct the tests and summarize the results.


Gaussian Processes in Machine Learning (Part 2): Implementing and Testing a Classification Model in MQL5
In this section, we will look at the implementation of the key interfaces of the library of Gaussian processes in MQL5: IKernel, ILikelihood, and IInference. We will also demonstrate its operation on synthetic data and implement indicators for classification and regression, demonstrating its operation in online mode - with retraining of the model on each new bar.


Analyzing Price Time Gaps in MQL5 (Part II): Creating a Heat Map of Liquidity Distribution Over Time
A detailed guide on how to create a heat map indicator for MetaTrader 5 that visualizes the price distribution over time. The article reveals the mathematical basis of time density analysis, where each price level is colored from red (minimum stay time) to blue (maximum stay time).


Neural Networks in Trading: Two-Dimensional Connection Space Models (Chimera)
In this article, we will explore the innovative Chimera framework: a two-dimensional state-space model that uses neural networks to analyze multivariate time series. This method offers high accuracy with low computational cost, outperforming traditional approaches and Transformer architectures.

MQL5 Wizard Techniques you should know (Part 20): Symbolic Regression
Symbolic Regression is a form of regression that starts with minimal to no assumptions on what the underlying model that maps the sets of data under study would look like. Even though it can be implemented by Bayesian Methods or Neural Networks, we look at how an implementation with Genetic Algorithms can help customize an expert signal class usable in the MQL5 wizard.

MQL5 Wizard Techniques you should know (14): Multi Objective Timeseries Forecasting with STF
Spatial Temporal Fusion which is using both ‘space’ and time metrics in modelling data is primarily useful in remote-sensing, and a host of other visual based activities in gaining a better understanding of our surroundings. Thanks to a published paper, we take a novel approach in using it by examining its potential to traders.


How to Implement Metaprompting for Trading Signals in an MQL5 Expert Advisor
Metaprompting is an approach in which the LLM itself optimizes trading instructions based on actual P&L and signal quality metrics. The article demonstrates a practical implementation in Python and MQL5: a prompt version registry, an execution agent, an evaluator for directional accuracy and profit factor, and a meta-LLM that generates improvements in a loop. The solution is integrated into the Expert Advisor without interrupting trading.


Risk Manager for Trading Robots (Part I): Risk Control Include File for Expert Advisors
Trading is characterized by high demands on risk management discipline. The article presents an analysis of the main reasons for traders' failures and proposes a technical solution in the form of the CEnhancedRiskManager class for the MQL5 platform. It includes practical testing on an aggressive grid EA.

Population optimization algorithms: Charged System Search (CSS) algorithm
In this article, we will consider another optimization algorithm inspired by inanimate nature - Charged System Search (CSS) algorithm. The purpose of this article is to present a new optimization algorithm based on the principles of physics and mechanics.

Neuroboids Optimization Algorithm (NOA)
A new bioinspired optimization metaheuristic, NOA (Neuroboids Optimization Algorithm), combines the principles of collective intelligence and neural networks. Unlike conventional methods, the algorithm uses a population of self-learning "neuroboids", each with its own neural network that adapts its search strategy in real time. The article reveals the architecture of the algorithm, the mechanisms of self-learning of agents, and the prospects for applying this hybrid approach to complex optimization problems.


Neural Networks in Trading: The Temporal Query Model (TQNet)
The TQNet framework opens up new possibilities for modeling and forecasting financial time series by combining modularity, flexibility, and high performance. The article explores the possibility of implementing complex mechanisms for handling global correlations, including advanced parameter initialization methods.

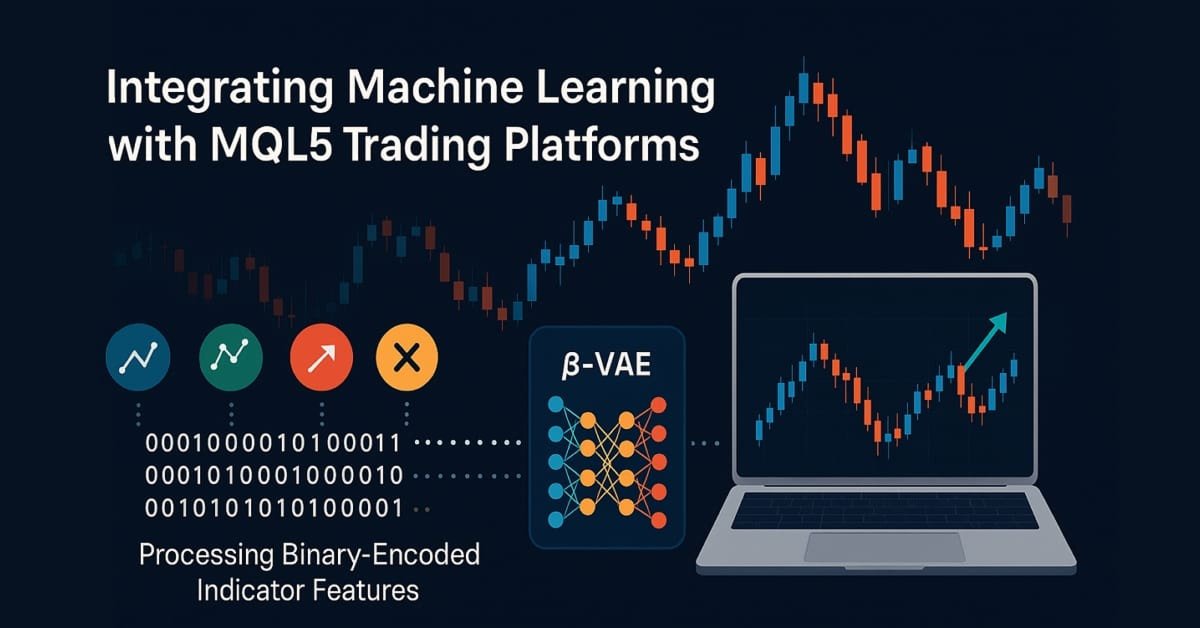
MQL5 Wizard Techniques you should know (Part 81): Using Patterns of Ichimoku and the ADX-Wilder with Beta VAE Inference Learning
This piece follows up ‘Part-80’, where we examined the pairing of Ichimoku and the ADX under a Reinforcement Learning framework. We now shift focus to Inference Learning. Ichimoku and ADX are complimentary as already covered, however we are going to revisit the conclusions of the last article related to pipeline use. For our inference learning, we are using the Beta algorithm of a Variational Auto Encoder. We also stick with the implementation of a custom signal class designed for integration with the MQL5 Wizard.


Color Harmony Algorithm (CHA)
We take a closer look at the Color Harmony Algorithm (CHA) — a meta-heuristic optimization method based on Munsell's theory of color harmony. We explore the structure of the hue circle, harmony templates, the alternation between the concentration and dispersion phases, and the role of solution memory. From a theoretical framework to a working implementation in MQL5 and unbiased testing on a standard benchmark.


Neural Networks in Trading: LSTM Optimization for Multivariate Time Series Forecasting (Final Part)
We continue to implement the DA-CG-LSTM framework, which offers innovative methods for time series analysis and forecasting. The use of CG-LSTM and dual attention allows for more accurate detection of both long-term and short-term dependencies in data, which is particularly useful for working with financial markets.