VonAI ICT scalper deep neural engine
- Эксперты
-
Christopher Adie
 Quantitative Trading Expert | Algorithm Development Specialist
Professional Overview - Версия: 2.0
- Активации: 5
VonAI ICT Scalper — Deep Neural Commodity Execution Engine
Target Institutional Price: $499
LAUNCH TIER ALLOCATION
-
First 5 Copies: $249 (LIMITED INTRODUCTORY BATCH: 0/5 CLAIMED)
-
Remaining Copies: $499 (Locks in permanently once 5 sales are reached)
-
Global Cap: Strictly limited to 220 lifetime licenses worldwide to preserve order execution quality.
OFFICIAL SETUP & CONFIGURATION PRESETS
All input parameters are pre-tuned and distributed via official .set files on our MQL5 Blog guide:
https://www.mql5.com/en/blogs/post/775921
(Download the official vonscalperAI.set directly from the blog to run with optimal broker spread conditions immediately).
Overview: Institutional Machine Learning Execution
Most automated trading robots fail in live conditions because they rely on curve-fitted indicators or dangerous loss-averaging schemes.
VonAI ICT Scalper pairs deterministic Smart Money concepts (Fair Value Gaps, Order Blocks, Liquidity Sweeps, and T3 Trend Momentum) with a pre-trained, embedded Machine Learning Neural Network (ONNX Engine) running natively in MetaTrader 5 memory.
Before any order is placed, the neural inference engine validates the structural setup against live market vectors: directional volatility (ATR), momentum slope (ADX), zone depth, session timing, and mathematical payoff ratios. Low-probability consolidations are filtered out in microseconds. Only high-probability institutional expansions are executed.
Verified Performance: Backtest & Walk-Forward Analysis
The system has undergone multi-year stress testing and live out-of-sample forward verification to ensure genuine statistical robustness without curve fitting.
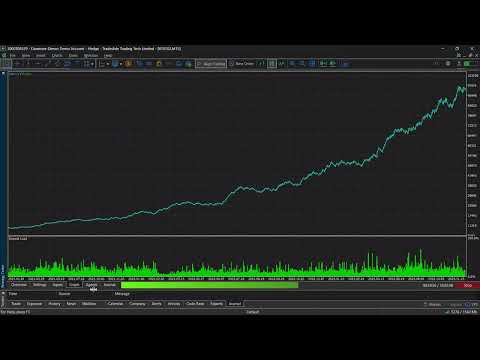
Multi-Year Real-Tick Stress Test (2021 – 2026)
-
Real-Tick Period: January 2021 – August 2026 (88.8M+ Ticks, 100% Quality)
-
Execution Realism: Tested under simulated 102 ms execution latency
-
Total Net Return: +$353,205.71 (+3,532%) on $10,000 base
-
Max Equity Drawdown: 14.17% (Cumulative across 5.5+ years of compounding; prop-firm compliant)
-
Profit Factor / Sharpe: 1.59 / 14.22
-
Average Trade Payoff: $2,081.36 Win vs. -$1,160.09 Loss (1.79 : 1 R:R)
Forward Walk-Forward Execution (2.5-Month Live Verification)
-
Account Base: $10,000.00
-
Net Profit Realized: +$728.94 (~3.0% / month pace)
-
Execution Realism: Forward log confirms a disciplined 2:1 R:R distribution with losses capped at ~$125 (~1.2% risk base) and wins expanding to +$255–$261.
-
Prop-Firm Discipline: Maintained zero consecutive equity violations; no martingale, no grid, and no hidden recovery averaging.
The 2020 Historical Stress Benchmark: Extreme Tail-Risk Survival
Quantitative commodities algorithms must demonstrate structural stability across unprecedented market regimes. Crude oil presents distinct systemic risks, most notably the historical April 20, 2020 event where front-month WTI dropped into negative territory (-$37.63/bbl) accompanied by extreme liquidity gaps and severe spread expansion.
-
Structural Invalidation (No Falling-Knife Execution): The engine operates strictly on confirmed order-block imbalances and liquidity sweeps. During hyper-extended unidirectional capitulation, the model withholds market entries until structural stabilization criteria are verified.
-
Deterministic Single-Ticket Risk: Every trade enforces an immutable Stop Loss placed simultaneously with the market order. Without grid averaging or recovery sizing, capital exposure remains strictly capped at predetermined parameters (e.g., 1.0% equity risk).
-
Regime Adaptation: Preserving capital during macro volatility contractions enables unconstrained compounding as institutional order flow returns to baseline parameters.
The Institutional Takeaway: A reliable algorithmic framework does not rely on curve-fitted, zero-drawdown assumptions. It demonstrates that during historic macroeconomic stress events, portfolio risk remains mechanically bound, preserving capital for sustained systematic execution.
Core System Architecture
-
100% Native ONNX Binary: No external DLLs, no Python dependencies, and no remote server connections required. The entire trained neural model is embedded inside the .ex5 file.
-
Hard Stop Loss & Take Profit: Placed simultaneously on broker servers at market execution.
-
Prop-Firm Compliance Protection: Hard-coded daily drawdown circuit breakers designed to satisfy strict funding evaluation rules.
-
Pre-Configured Presets: Plug-and-play .set files available for download eliminate manual parameter guesswork.
Recommended Specifications
-
Primary Symbol: XTIUSD / WTI / US OIL (Crude Oil)
-
Recommended Timeframe: M15 (Optimized for M15)
-
Account Type: ECN, Raw Spread, or Low-Spread Standard
-
Minimum Balance: $100 (Recommended: $500–$1,000+ for prop evaluations)
-
Execution: Low-latency VPS recommended (<20ms ping)
Quick Start Guide
-
Open your broker's XTIUSD (or WTI/USOIL) chart on the M15 timeframe.
-
Drag VonScalper.ex5 onto the chart.
-
In the Inputs tab, load your preferred .set file downloaded from our MQL5 blog.
-
Ensure the "Allow Algo Trading" button in MT5 is toggled ON (Green).