Comprehensive Guide to Automated Trading Architectures: Mechanics, Risks, and Why Breakouts Endure

When evaluating an Expert Advisor on the market, inspecting past profitability alone is rarely enough. The single most important factor determining whether an algorithm will survive long term or eventually wipe out an account is its underlying architecture. Every automated system is built on a specific trading philosophy, and each approach comes with distinct structural advantages, hidden execution costs, and mathematical risks.
Below is an objective breakdown of the primary automated trading architectures used in the algorithmic space today.
- Scalping Strategies
Scalping systems aim to capture small, rapid price fluctuations, often using momentum indicators or micro-breakouts.
The primary advantage of scalping is that it can be operated on relatively small balances with strictly defined risk parameters. Trades open and close within minutes, meaning capital is rarely tied up in painful multi-day drawdowns.
However, scalping is extremely sensitive to infrastructure. It demands a fast Virtual Private Server located close to the broker matching engine and an ultra-low spread CN or RAW account. Over time, many retail brokers detect fast order turnover and may introduce subtle execution delays, negative slippage, or wider spreads that steadily erode narrow profit margins.
- Grid Systems
Grid trading involves placing orders at predetermined intervals above or below a base price, relying on position averaging to exit baskets of trades collectively in profit.
Strategy-filtered grids wait for technical extremes before placing positions, while logic-less grids deploy fixed orders blindly. While a well-configured grid can produce uninterrupted profits for weeks or months, the mathematical reality remains punishing: an extended, uncorrected trend will continually open larger exposures, eventually triggering deep drawdowns or complete account liquidation unless hard equity protection stops it.
- Martingale Systems
Martingale strategies attempt to create a high-win-rate curve by increasing position sizing following a losing trade, aiming to recover accumulated losses with a single winner.
A capped martingale approach, where lot scaling is restricted to only one or two recovery steps, limits exposure to a larger predefined drawdown. In contrast, uncapped exponential lot doubling gambles the entire account balance on the fragile assumption that a market reversal must occur before capital runs out.
- Grid Martingale Combinations
- Arbitrage
While theoretically risk-free on paper, retail implementation is virtually impossible today. Brokers utilize sophisticated server-side plug-ins to identify toxic arbitrage flow immediately. Retail arbitrage attempts routinely result in heavy artificial slippage, rejected orders, profit cancellations, and permanent account terminations.
- High-Frequency Trading (HFT)
In institutional environments, HFT functions through multi-million dollar co-located fiber connections directly on exchange matching engines. On retail MetaTrader platforms, true HFT cannot function. Retail execution bridges, processing latency (even 2 to 5 milliseconds is too slow for genuine HFT), and retail bid-ask spreads make the strategy unviable on standard consumer broker accounts.
- Hedging Architectures
While some traders view hedging as a safe alternative to a Stop Loss, it introduces severe operational complexities. Holding opposing positions doubles margin requirements on non-netting accounts and doubles ongoing spread and overnight swap costs. Furthermore, mathematically unlocking a negative hedged position without realizing a loss is notoriously difficult for automated logic, often mutating into a locked grid that drains equity through carrying costs.
- Subjective Price Action and Complex Chart Patterns
While effective in discretionary manual trading, translating complex geometric chart patterns into rigid MQL5 code is notoriously difficult. Price action patterns rely heavily on context and human interpretation, making algorithmic execution prone to false pattern recognitions.
- Breakout Trading (The Evergreen Price Action)
Unlike subjective chart formations, breakout trading focuses on concrete, objective price levels: swing highs, swing lows, daily range boundaries, and structural liquidity pools.
Breakouts have remained a pillar of technical trading for decades because they are anchored in market mechanics. When a critical price barrier breaks, clusters of stop orders are triggered alongside aggressive institutional momentum, driving the market swiftly toward the next liquidity zone. For algorithmic trading, breakout levels can be calculated mathematically and executed with clean precision.
In our latest development, Tectonic Gold, the primary objective was to eliminate the structural flaws commonly found in traditional retail robots.
Instead of relying on fragile grid averaging, dangerous martingale scaling, or complex hedged locks, Tectonic Gold is engineered around multi-timeframe breakout principles. It scans multiple time horizons in parallel to identify verified institutional support and resistance levels across Gold (XAUUSD).
Every single trade is defended by an explicit Stop Loss and Take Profit from the exact millisecond of execution. While it incorporates rapid micro-breakout scalping alongside multi-day swing mechanics, the targets and safety buffers are mathematically calibrated so that minor broker slippage or temporary spread widening cannot degrade the strategy edge.
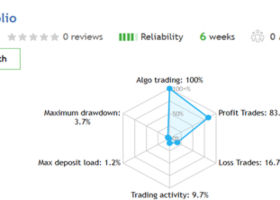
This transparent, disciplined architecture is why the system has maintained steady, verified live growth without relying on artificial balance recovery tricks.
Explore Tectonic Gold on the MQL5 Market:
https://www.mql5.com/en/market/product/184933