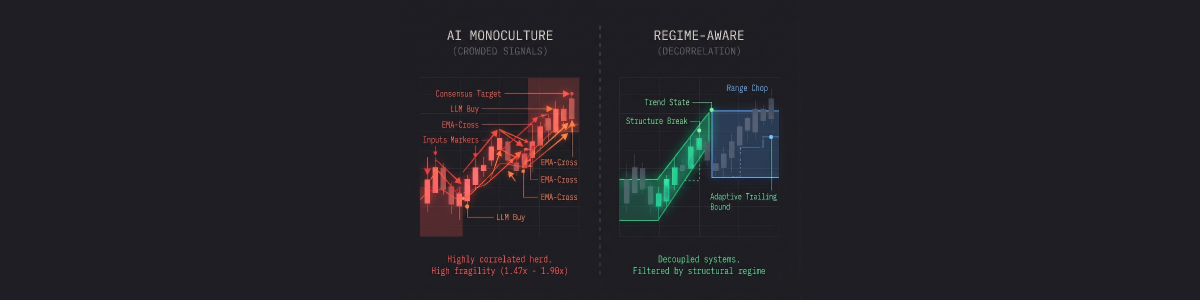
The AI Monoculture Paradox: Why Crowded Signals Crash Markets, and How Regime Detection Cuts Loss by 46%

What happens when thousands of systematic traders and automated portfolios use the exact same AI architectures, fine-tuned models, and standard technical indicator sets to interact with the market?
Recent quantitative studies ("The AI Monoculture Paradox in Financial Markets" and "Decorrelating the Advice Layer", arXiv: 2610.38340) have calculated hard numbers on a systemic risk every experienced live trader eventually feels on the chart: the cost of synchronized crowd behavior.
💥 The Core Findings on "Signal Crowding"
- Algorithmic Fragility: When independent market participants adopt similar AI models or standard parameter sets, they generate highly synchronized order flow—making liquidity 1.47x to 1.90x more fragile when the consensus reverses.
- The "Precision" Trap: A model or indicator may appear "sharper" in backtests, but its backtest does not account for the market impact and slippage when thousands of traders try to hit the same microsecond window.
- Regime Detection Saves Drawdowns: Microstructure research shows that while aggressive, static algorithms get run over by "adverse selection" when crowd regimes break, systems that deploy explicit regime-detection filters to shift or halt activity can cut losses by up to 46%.
Oscillator Disagreement Is Information—Don't Average It Out
Most common systems and AI bots look at indicators as isolated, binary triggers (e.g., "RSI is oversold, therefore buy"). In reality, oscillators or momentum measures disagree most of the time because they assess different structural layers of the auction.
Averaging disparate indicators together or forcing an AI to give a singular consensus view just hides the regime shift. The true Edge lies in measuring where these structural layers clash on closed, finalized bars—revealing when the herd has overcommitted and is about to get trapped.
To withstand these crowded systemic reversals, your trading logic must incorporate explicit state-of-the-market filters and structural validation:
Building on Falsification-First Measurement
Every tool I design operates under a strict falsification-first discipline: closed-bar values are final, nothing repaints, and every metric documents the exact boundaries where it ceases to be mathematically meaningful:
🔍 REGIME AND STRUCTURE — Identifying state shifts and stop coordination
- ▸ Oscillator Regime Suite (MT5) · $89 · MT4 Version ($89) — Tracks multiple oscillator agreements & regimes without blending them into useless averages
- ▸ Structure Flow and Trailing Stop (MT5) · $99 · MT4 Version ($99) — Maps objective structural breaks and volatility-adjusted trailing limits
📐 TREND PERSISTENCE — Estimating non-binary probabilities
- ▸ Trend Survival States (MT5) · 🆓 · 5-state structural classification
👉 Explore all 18 non-repainting measurement tools on my MQL5 profile: mql5.com/en/users/naamo (@naamo)
💬 How do you detect when a market regime has shifted from orderly trending flow into a highly crowded, volatile chop?
📚 References & Further Reading:
- The AI Monoculture Paradox in Financial Markets (SSRN: 4947018): https://papers.ssrn.com/sol3/papers.cfm?abstract_id=4947018
- Decorrelating the Advice Layer: Robust Optimization in Overcrowded Markets (arXiv: 2610.38340): https://arxiv.org/abs/2610.38340



