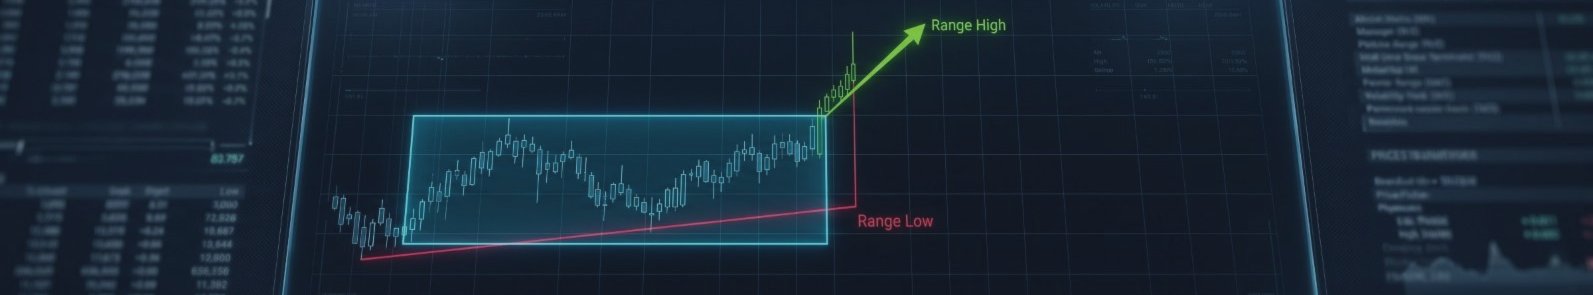
The 09:30 Liquidity Expansion: Automating Institutional 30-Minute Session Breakouts on MetaTrader 5

An in-depth quantitative guide to market microstructure, Auction Market Theory, opposite-boundary risk modeling, and how to eliminate false whipsaws with automated 1-trade-per-day execution.
⚡ Quick Summary & Key Takeaways
- The 09:30 AM Trap: Why 85% of retail scalpers lose money trading oscillators during the opening 30 minutes of the New York cash session.
- Auction Market Theory: How the Initial Balance (IB) establishes true institutional supply and demand boundaries.
- Opposite-Boundary Stop Loss: Why anchoring stops to the opposite side of the session range mathematically outperforms tight arbitrary point stops.
- Double Take-Profit Mechanics: De-risking trades at 2.0R while locking in Breakeven for an unrestricted 3.0R runner.
- Prop-Firm Discipline: The statistical proof behind why a strict 1-Trade-Per-Day rule is the single most effective defense against FTMO daily drawdown violations.
1. The Market Microstructure Trap: Why Conventional Indicators Fail at Market Open
Every trading day at exactly 09:30 AM Eastern Time (New York Cash Open), the financial markets experience an unprecedented influx of institutional liquidity. In equities, index futures (NASDAQ, US30, S&P 500), and commodities like Gold (XAUUSD), opening volume frequently surges by over 400% compared to pre-market averages.
Yet, this is precisely where the majority of retail traders blow their evaluation challenges. The standard retail playbook is filled with flaws:
- Lagging Oscillators (RSI, Stochastic, MACD): During violent opening volume injections, oscillators enter "overbought" or "oversold" territory within seconds. Traders trying to fade these moves get crushed by one-way institutional momentum.
- Chasing the First 5-Minute Candle: The first few minutes are dominated by market makers clearing pre-market stop orders and executing institutional opening cross-auctions. Entering during 09:30–09:35 routinely results in getting wicked out on both sides of the market.
- Arbitrary Pip Stops: Placing an arbitrary 15-pip or 20-point stop loss inside an expanding volatility regime almost guarantees getting stopped out before the true directional trend emerges.
To consistently extract profits from opening volatility, traders must abandon lagging indicators and adopt Auction Market Theory.
2. Institutional Theory: The 30-Minute Opening Range & Volatility Expansion
In institutional order flow, the market is an auction mechanism designed to facilitate trade. Between 09:30 and 10:00 AM New York time, smart money participants establish what quantitative analysts refer to as the Initial Balance (IB) or the Session Opening Range.
| Microstructure Level | Institutional Meaning | Market Participant Behavior |
|---|---|---|
| Session High (Range High) | Buy-Side Liquidity (BSL) Ceiling | Sellers defending premium pricing; breakout triggers aggressive stop-runs and momentum algorithms. |
| Session Low (Range Low) | Sell-Side Liquidity (SSL) Floor | Buyers defending discount pricing; breakdown forces long liquidations and trend-following sell programs. |
| 10:00 AM Post-Range Expansion | Price Discovery Phase | With the range locked, institutional algorithms fire directional orders to expand range into daily targets. |
By strictly waiting for the 30-minute window (09:30–10:00) to conclude, we allow the market makers to complete their initial distribution. Once the high and low are locked, any subsequent breach represents authentic directional capital displacement.
3. The Algorithmic Translation: Engineering the "Volume Strike" Protocol
How do we translate this institutional concept into pure, emotionless MQL5 algorithmic execution? Below is the quantitative architecture engineered into Volume Strike EA:
Step 1: Precision Range Identification (09:30 – 10:00)
The algorithm monitors tick-by-tick prices between the configurable start and end hours ( InpRangeStartTime = "09:30" , InpRangeEndTime = "10:00" ). It records the absolute highest high and lowest low of the session window. At 10:00:00, the range is permanently locked and visually shaded on the chart.
Step 2: Instantaneous Tick-Touch Breakout Execution
Rather than waiting for candle closes (which frequently surrender 30–50% of the move on high-beta assets like NASDAQ), the EA executes at the microsecond price touches:
- BUY Trigger: Current_Ask >= (Session_High + InpEntryOffsetPoints)
- SELL Trigger: Current_Bid <= (Session_Low - InpEntryOffsetPoints)
Step 3: Opposite-Boundary Structural Protection
Instead of guessing a stop loss, the EA anchors protection to structural market geometry:
- For a BUY: Stop Loss is positioned at the Range Low (minus optional buffer points). If price traverses the entire 30-minute range in reverse, the breakout thesis is invalidated.
- For a SELL: Stop Loss is positioned at the Range High (plus optional buffer points).
Step 4: Dual Target (Double TP) Engine
To optimize the mathematical expectancy, the position is split into two distinct tranches:
- Target 1 (TP 1 @ 2.0R): Closes 50% of the volume at twice the initial risk distance.
- Breakeven Migration: The moment TP 1 is struck, the Stop Loss on the remaining 50% automatically shifts to Entry Price + InpBreakEvenOffsetPoints , securing a 100% risk-free trade.
- Target 2 (TP 2 @ 3.0R): Captures explosive multi-session continuation runs with zero downside risk.
Step 5: The 1-Trade-Per-Day Prop-Firm Discipline
The single greatest killer of prop firm accounts is revenge trading after a choppy session. By enforcing a strict binary flag:
if(g_trades_executed_today >= 1) return; // Strict 1-Trade-Per-Day discipline
The EA takes the highest-probability expansion move of the day and shuts down until tomorrow's session rollover. This single mathematical constraint virtually eliminates the risk of breaching the FTMO 5% daily loss limit.
4. Step-by-Step MetaTrader 5 Setup & Backtesting Best Practices
To achieve institutional backtest accuracy that matches live execution, adhere strictly to these configuration guidelines:
Recommended Instruments & Settings
- NASDAQ 100 (NAS100 / US100 / USTEC): Ideal for 09:30–10:00 NY Cash Open. Range typically spans 60–120 index points.
- Dow Jones 30 (US30 / DJ30): Massive momentum expansion post-10:00 AM.
- Gold (XAUUSD): Highly responsive to London Open (08:00–08:30 GMT) or NY Open (13:30–14:00 GMT).
- Timeframe: M1, M5, or M15. (Note: Because Volume Strike executes on real-time tick touch, the chart timeframe does not restrict execution speed).
MT5 Strategy Tester Protocol
- Open the MT5 Strategy Tester ( Ctrl + R ).
- Select Volume Strike from the Experts dropdown.
- Set Model to: "Every tick based on real ticks" (Crucial for verifying millisecond tick-touch breakout accuracy).
- Input your broker's server time equivalent of 09:30 AM New York (e.g. 16:30 for standard GMT+2/GMT+3 European brokers).
- Observe the automated on-chart visual boxes, historical range lines, and trade markers.
5. Deploy the Free Strategy on Your MT5 Terminal
Rather than manually watching charts every morning at 09:30 and fighting emotional execution slippage, you can automate this exact framework today.
👉 Download the Free Demo of Volume Strike EA on the MQL5 Market
The Expert Advisor includes:
- Automated 30-minute session range detection and live chart box shading.
- Tick-level breakout execution with zero lag.
- Opposite-boundary Stop Loss calculation and dynamic Double TP runner management.
- Strict 1-Trade-Per-Day prop firm risk guardrails.
- On-chart visual dashboard displaying live equity, session range dimensions, and historical win rates.
6. Ecosystem Synergy: Complete Your Trading Portfolio
A resilient trading business never relies on a single strategy regime. Combine opening session volatility with our full institutional suite:
- APEX LIQUIDITY MATRIX: Catch multi-day trend expansions on XAUUSD with dynamic trailing stops and a 3:1 Reward-to-Risk target.
- PipViper Quant MT5: Institutional mean reversion and order-flow scalping for Asian and London sessions.
Have questions about configuring broker server time or optimizing range offsets for your prop firm challenge? Drop a comment below, and I will share pre-tested .set files for NAS100 and US30!




