Causoryx US100
- 专家
- 版本: 1.3
- 激活: 15

Causoryx US100
A price oscillator, the US opening window and defined M10 rules.
CAUSORYX looks for directional signals during the US opening window. It combines a normalized oscillator with completed M10 bars, fixed volume and a configurable initial-risk budget.
The trading approach
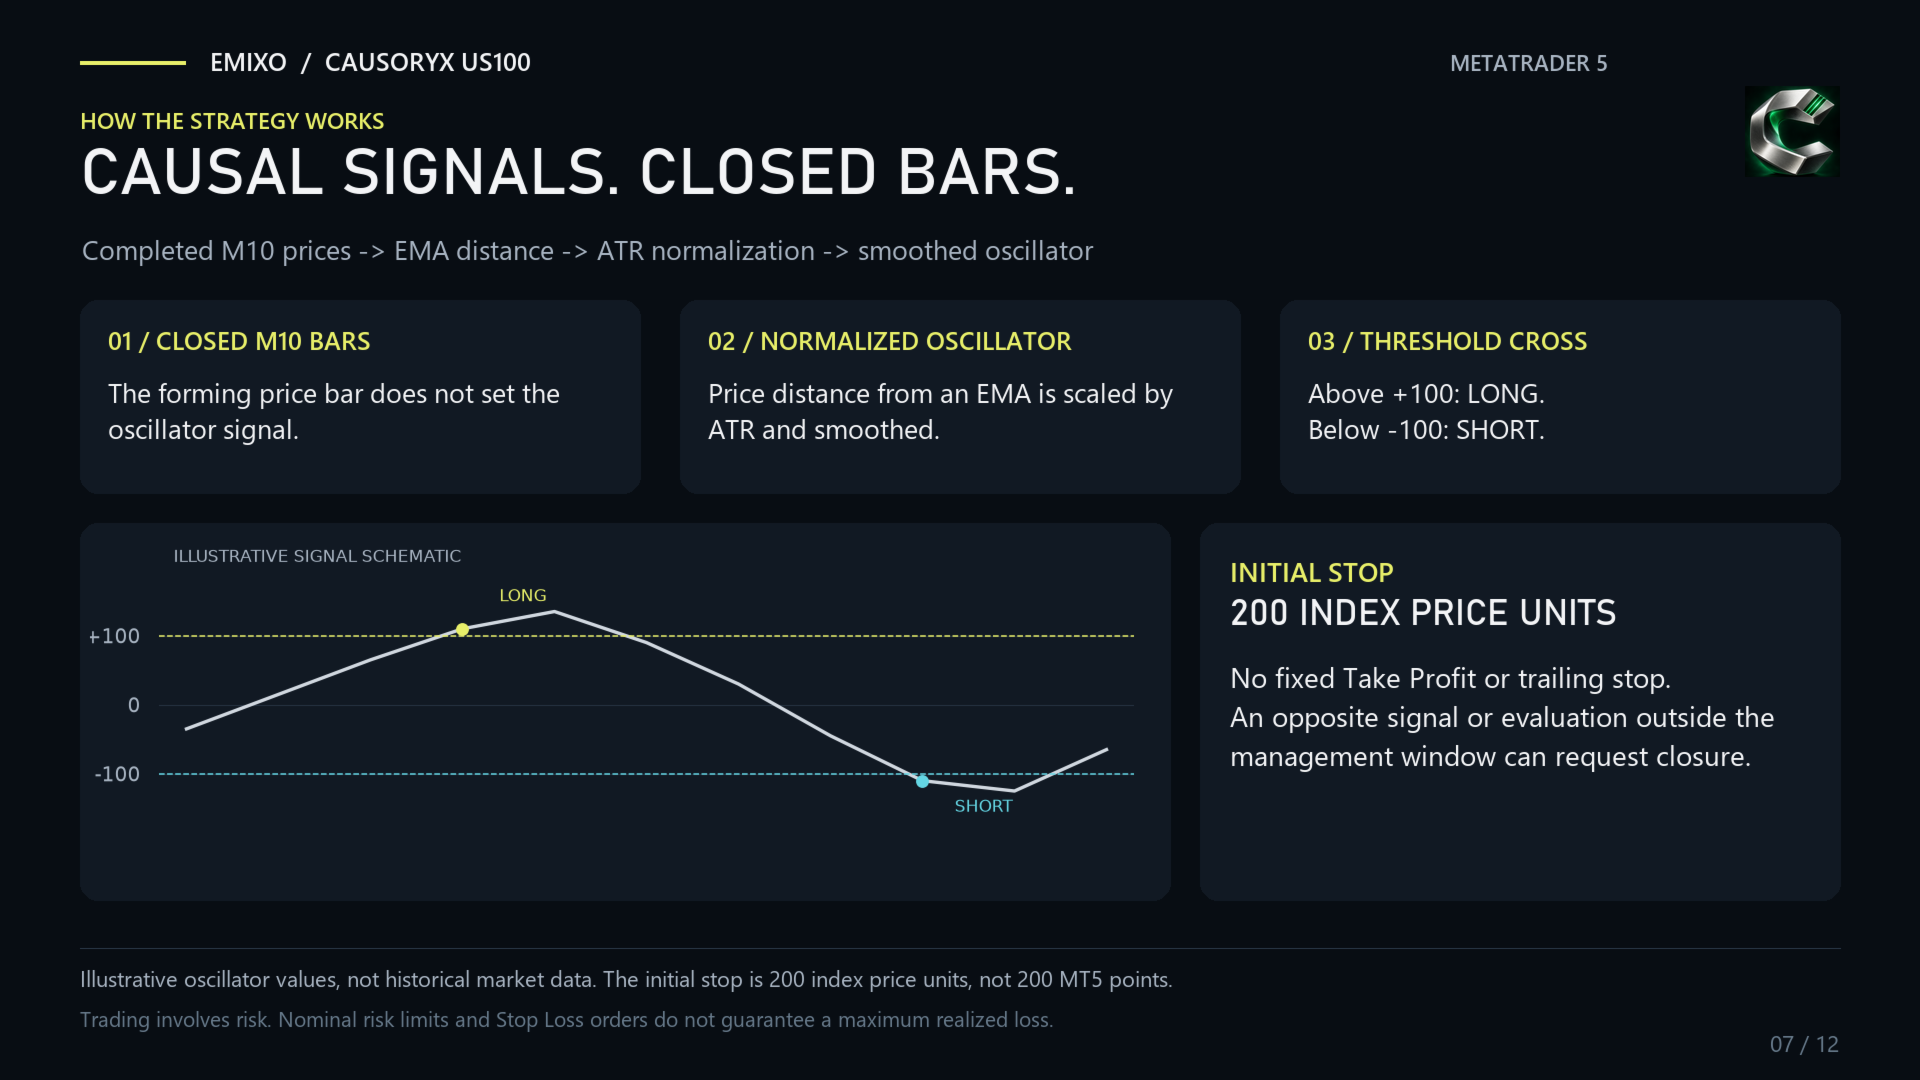
The model measures the distance from an exponential average relative to ATR, then smooths completed-bar values. Positive and negative threshold crossings generate the signals. On the strategy's reference clock, M10 decision bars run from 16:40 to 18:00.
What Causoryx offers
- An identifiable trading window. Entry selection focuses on the opening session, with configurable broker-clock settings.
- Completed-bar decisions. The oscillator uses the values specified by its M10 rules rather than a forming-bar signal.
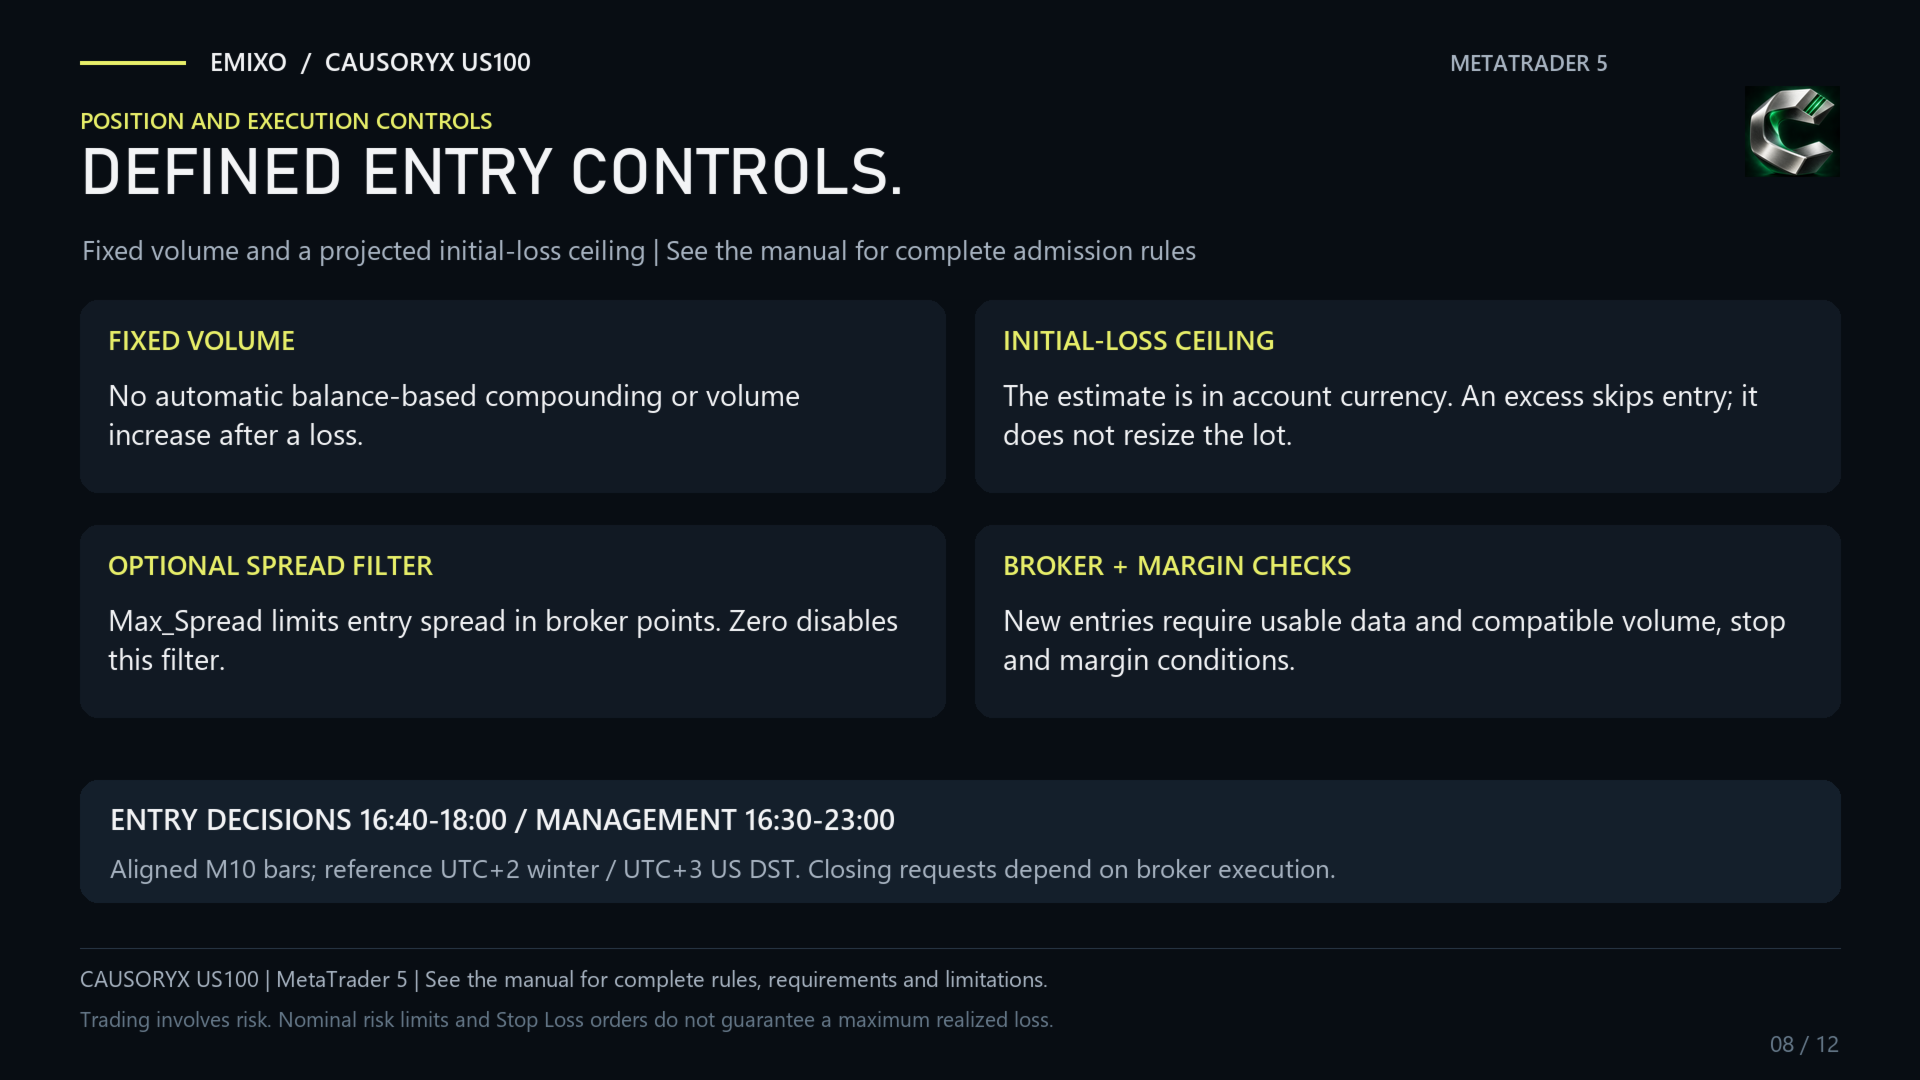
- Separate lots and budget. Choose fixed volume and the estimated initial-loss limit in account currency.
- Model-based exits. An initial stop, opposite signals and the management window define the trade's lifecycle.
Your settings
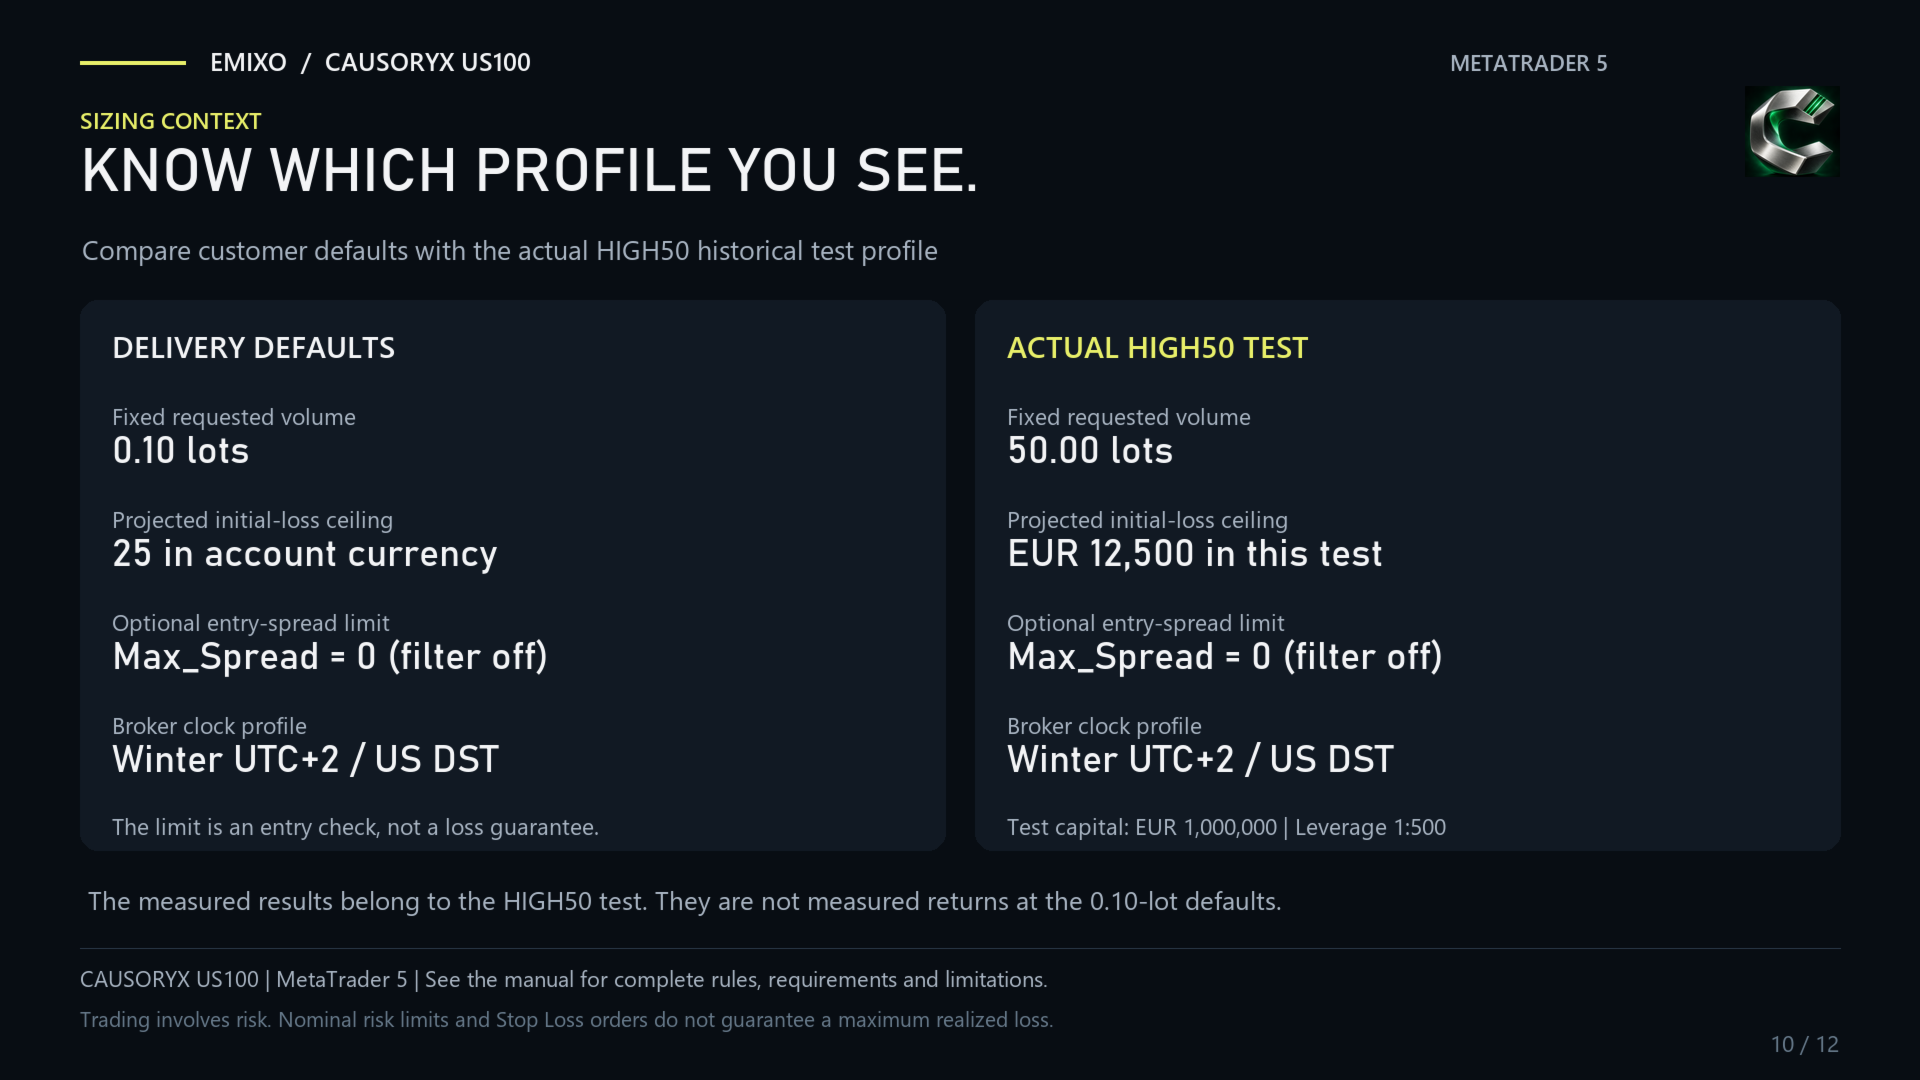
Defaults are 0.10 lots and an estimated initial-risk budget of 25 in account currency. On the reference US100 contract, the original stop distance is 200 index price units. The strategy manages exits without a fixed Take Profit or trailing stop; its management window is 16:30–23:00 on the specified reference clock.
Reference setup
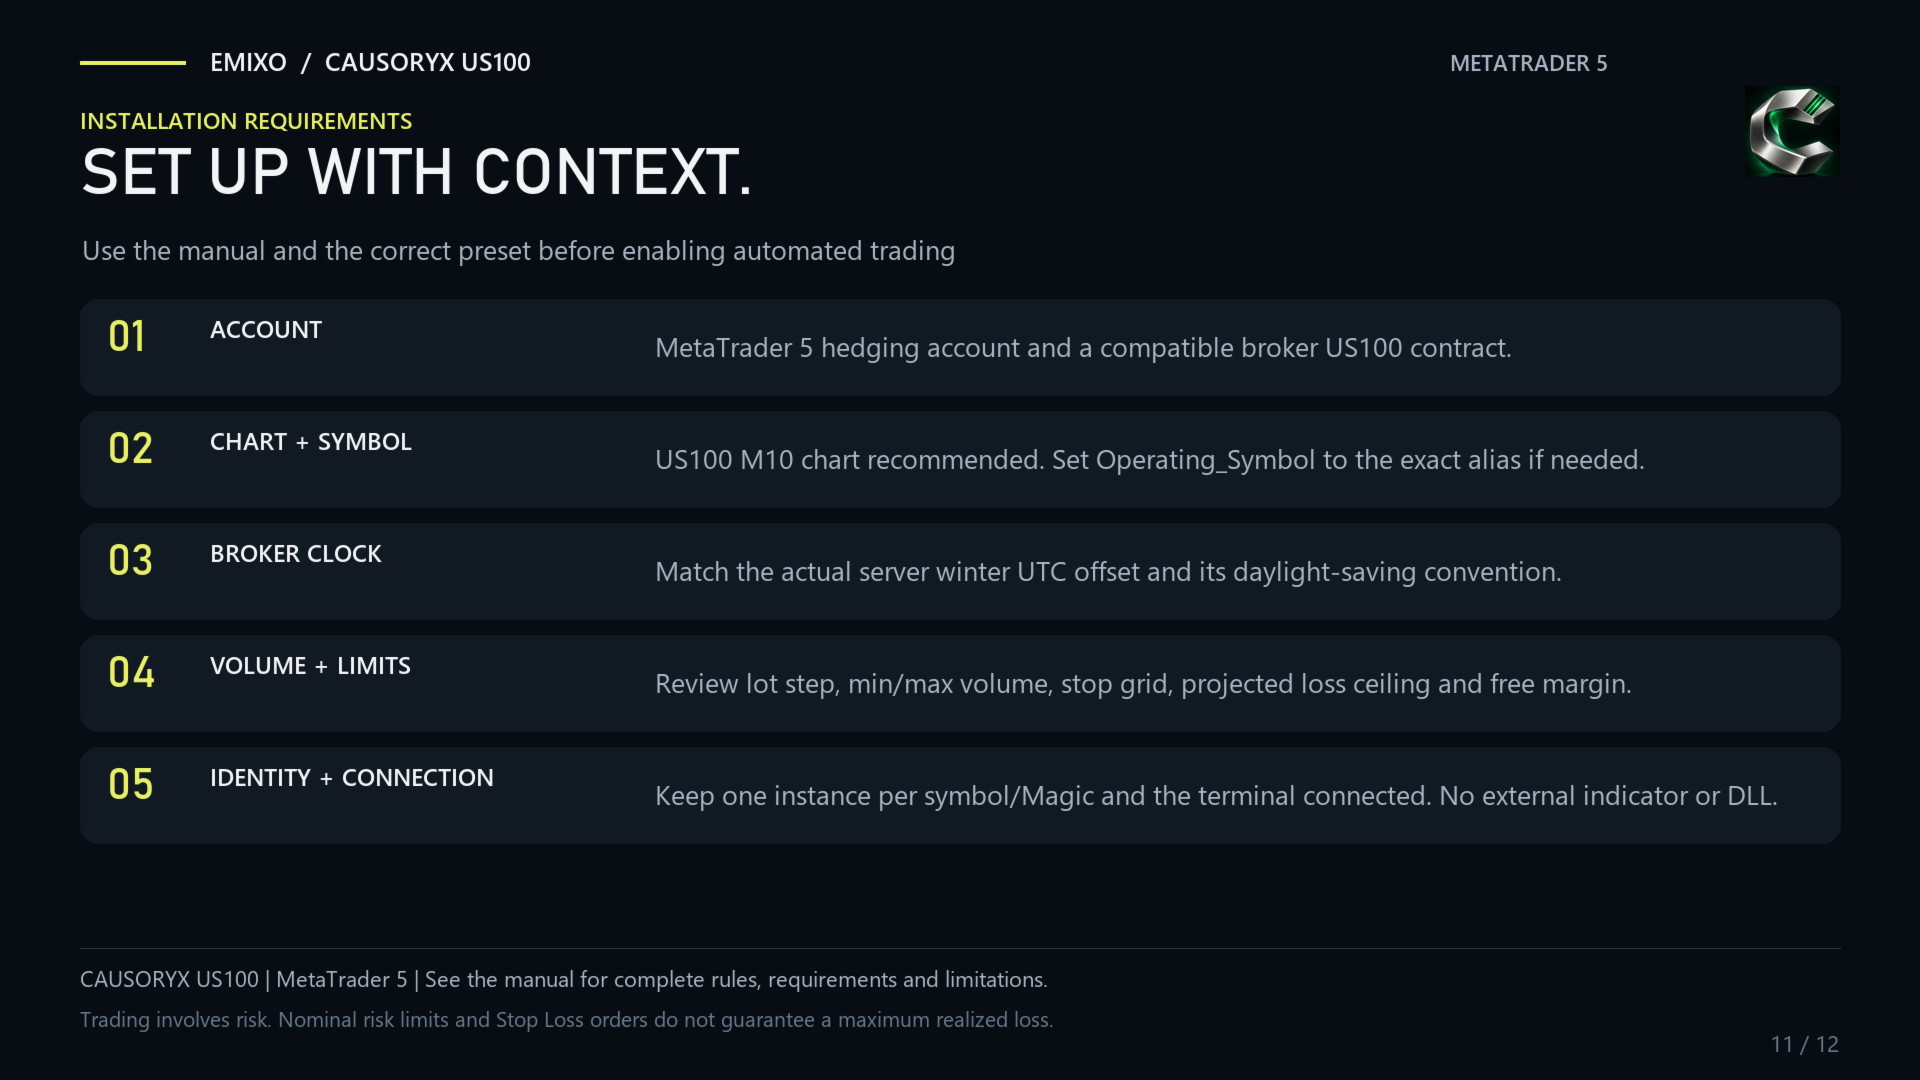
Use a hedging account and US100 M10. Configure the operating symbol and the broker's UTC/DST settings as described in the manual. The budget is a pre-entry check: a volume above the admitted estimate is not automatically resized.
Historical test
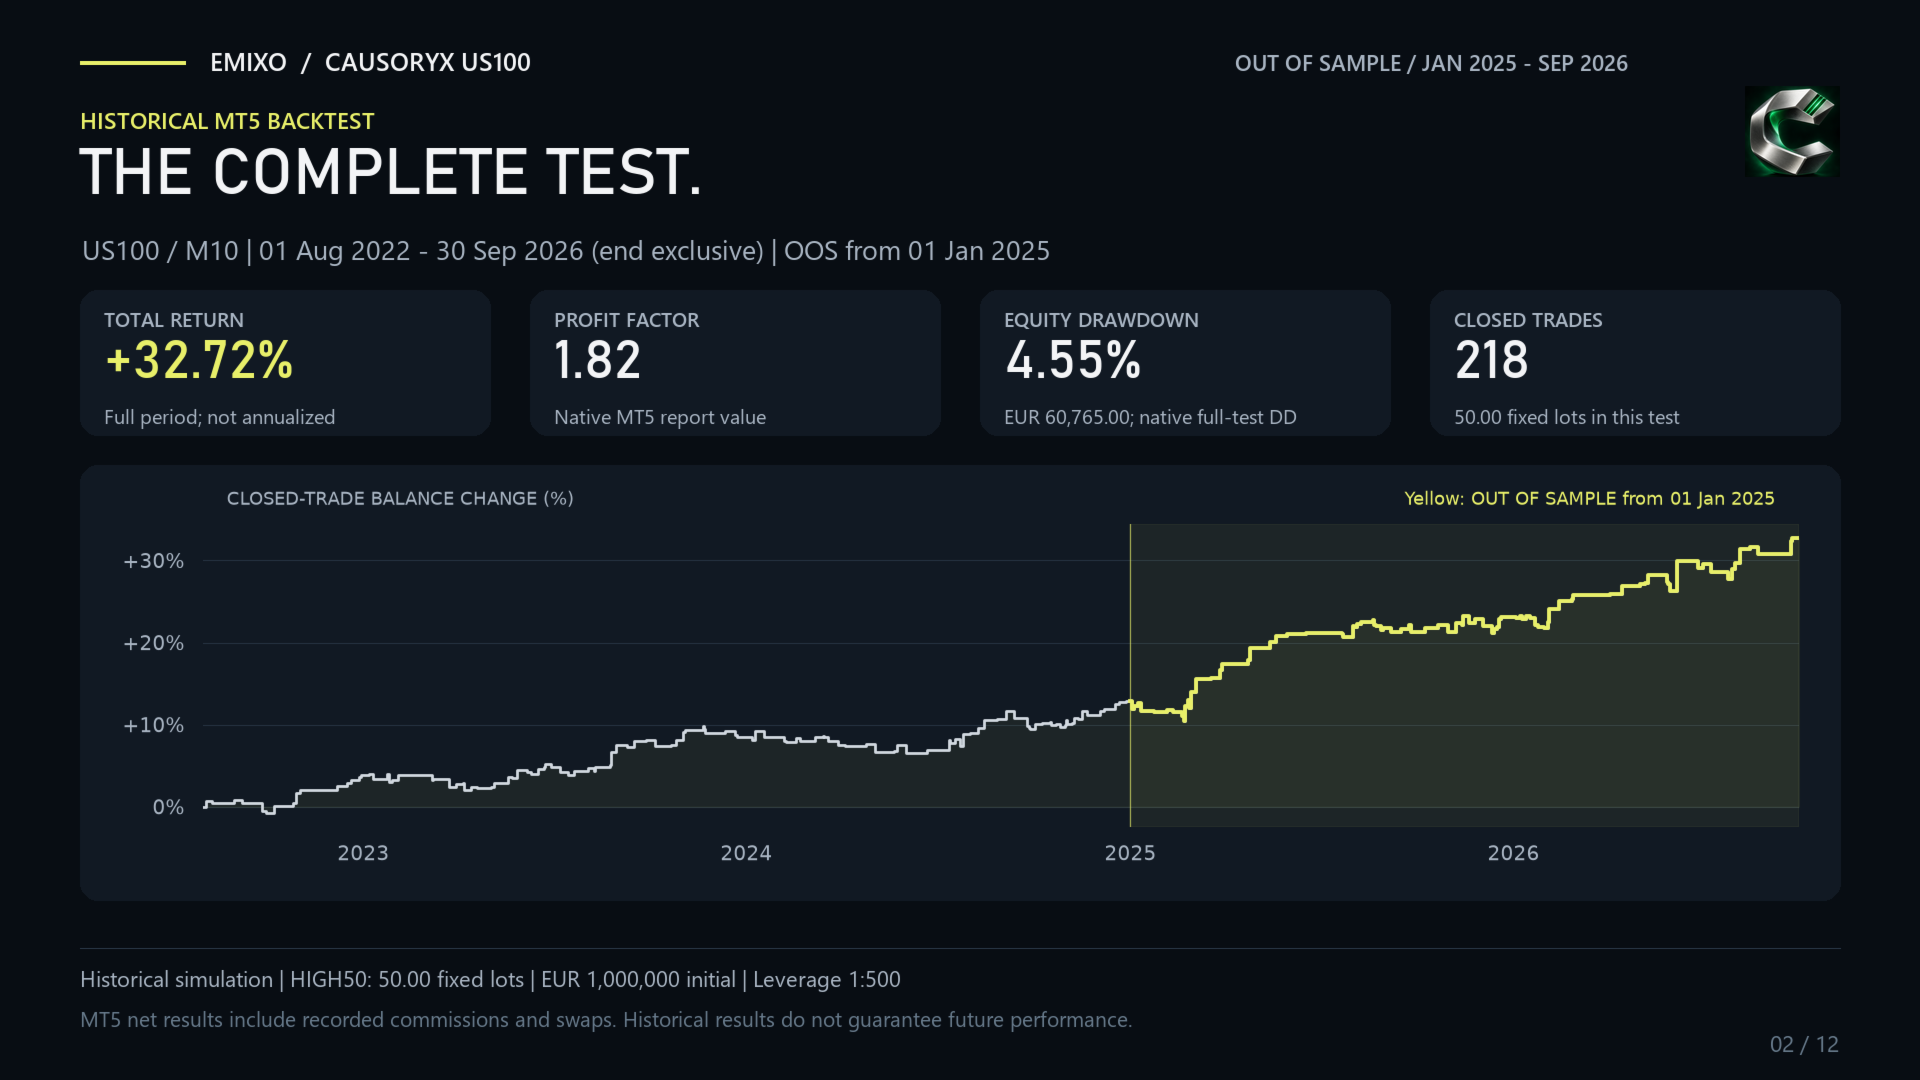
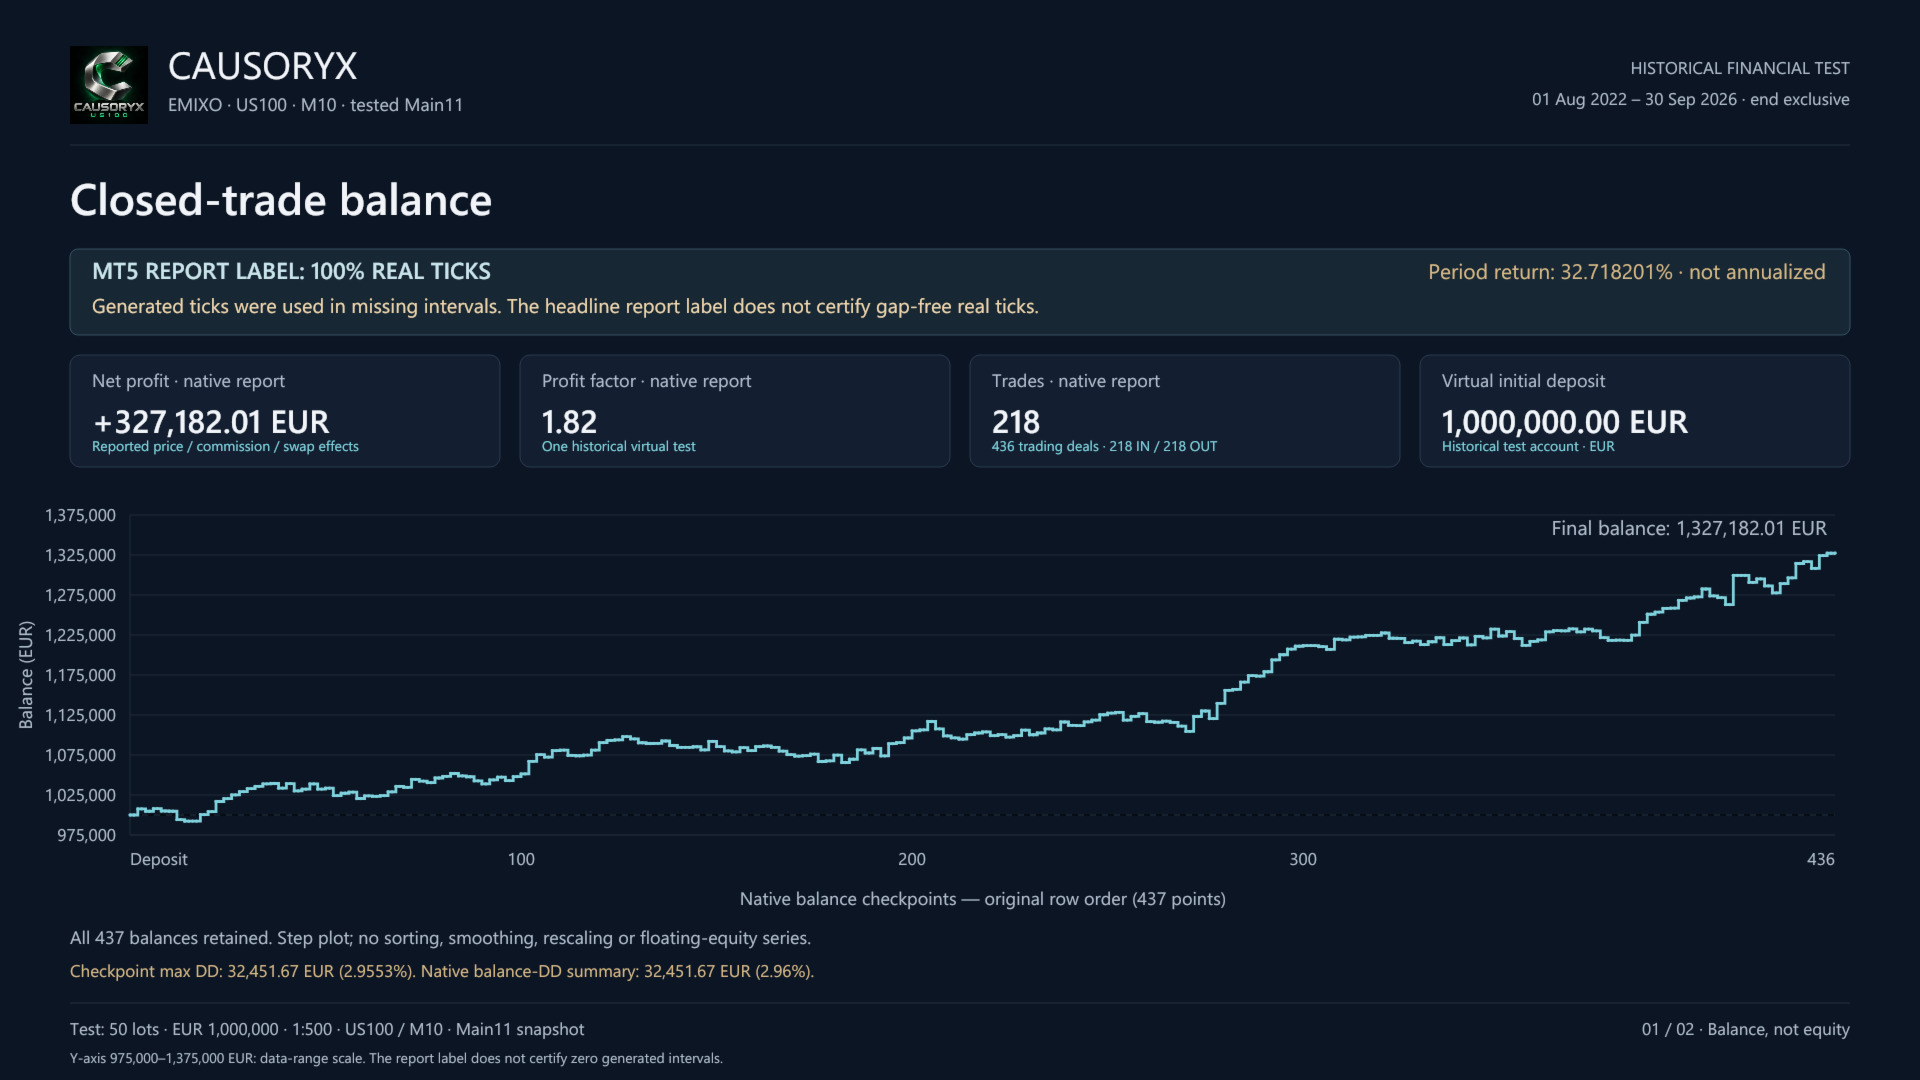
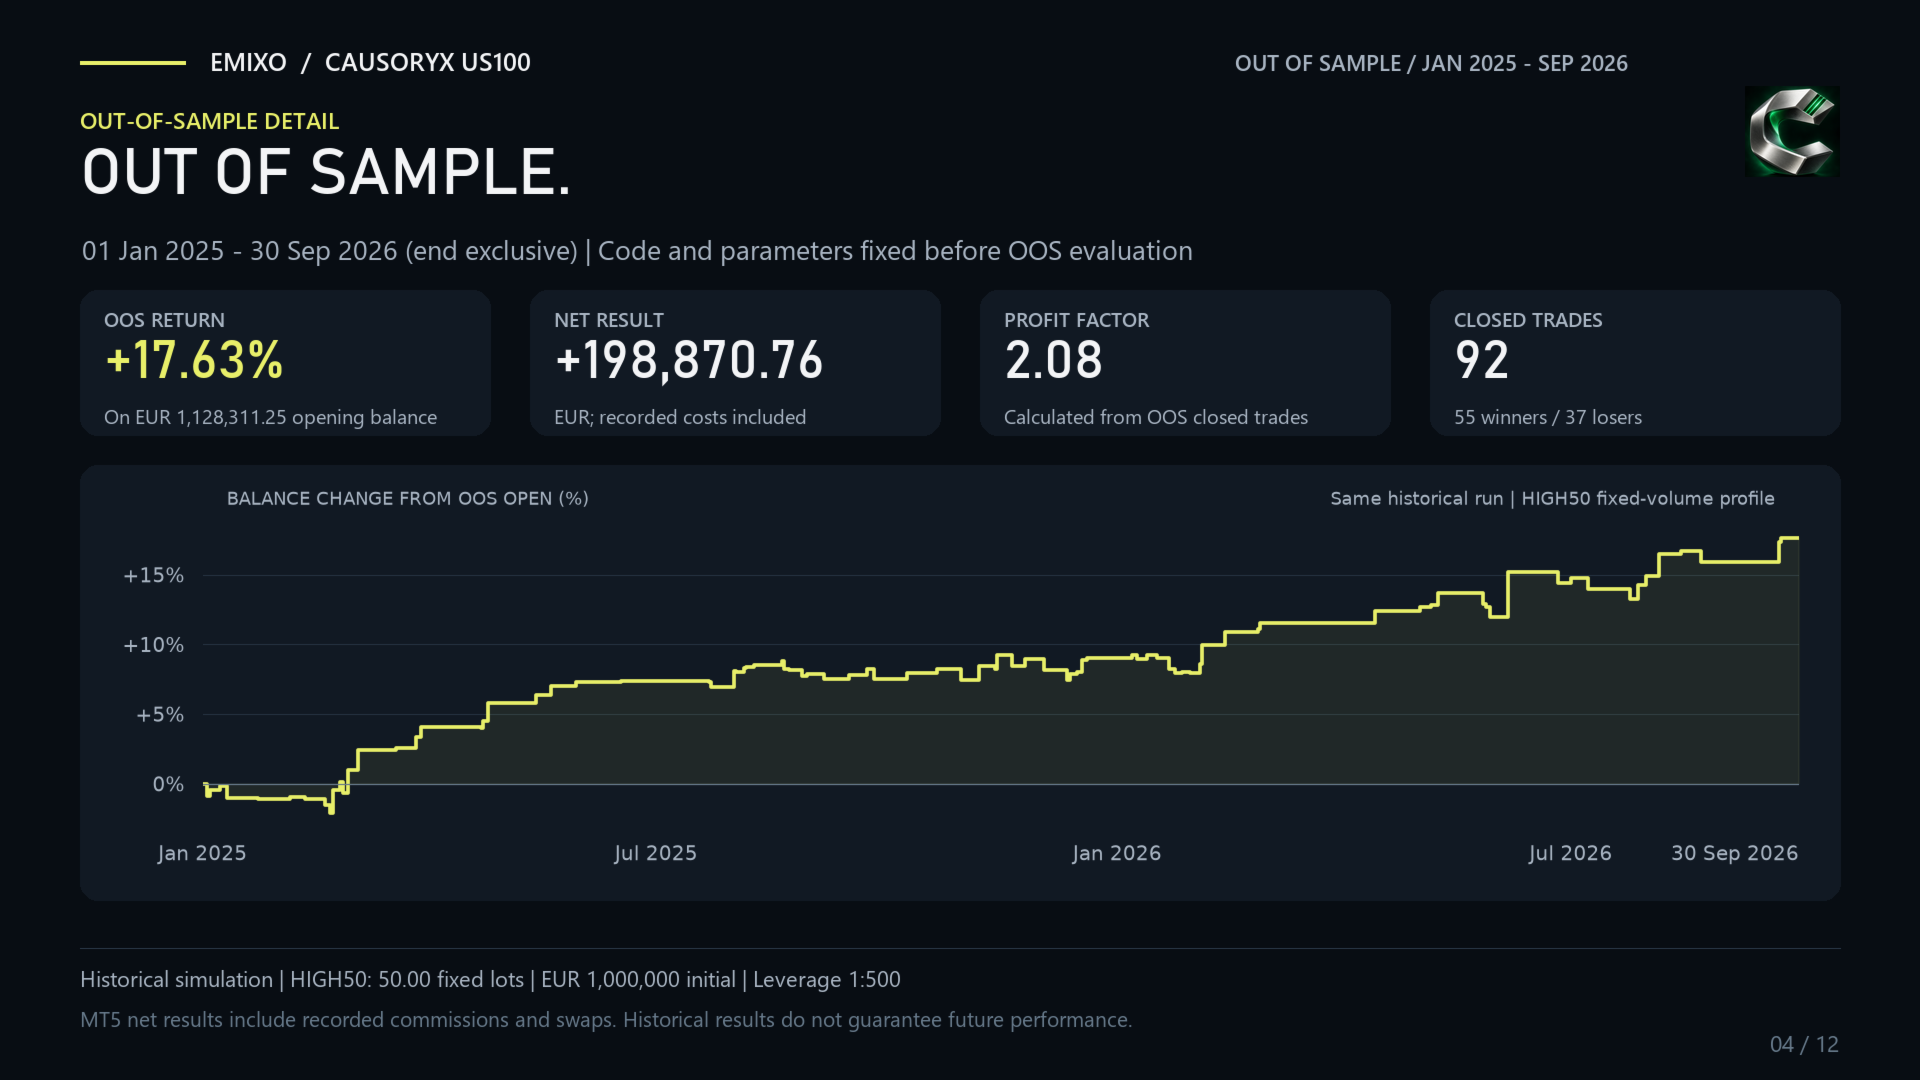
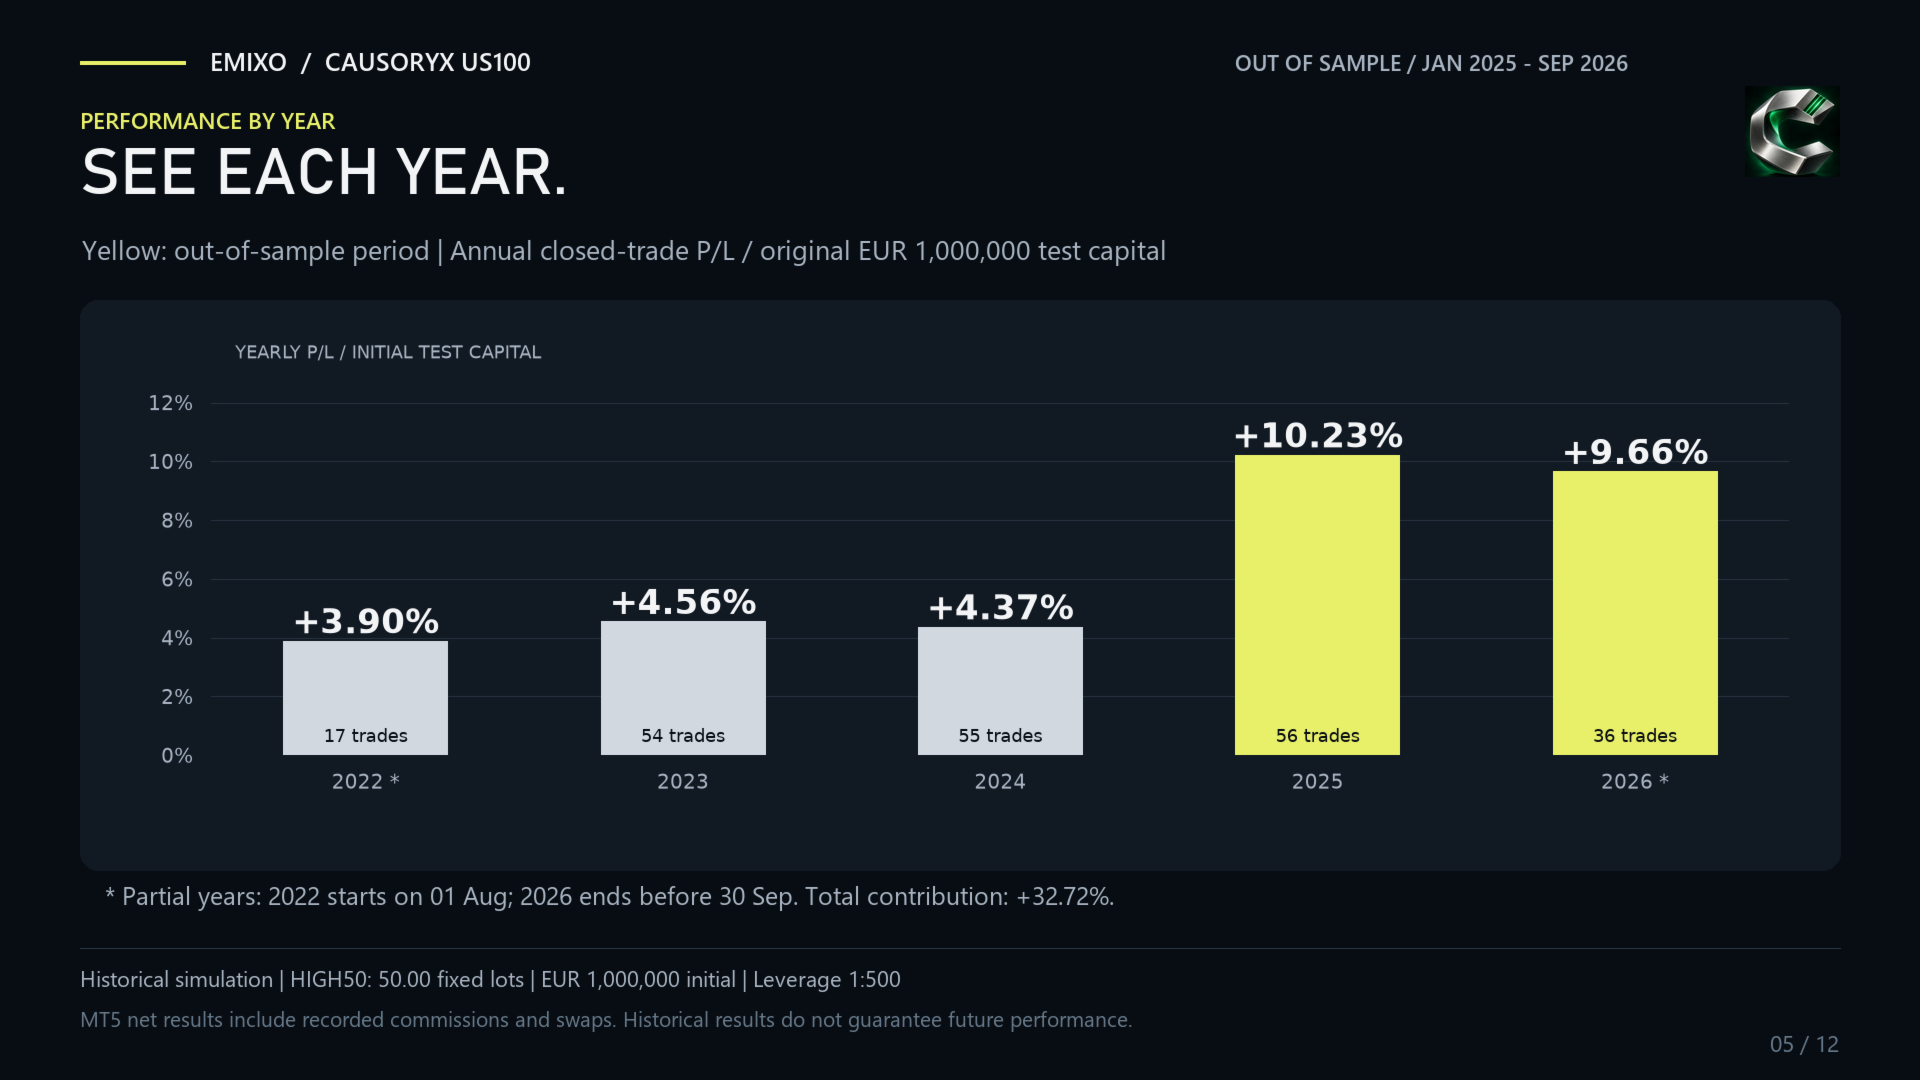
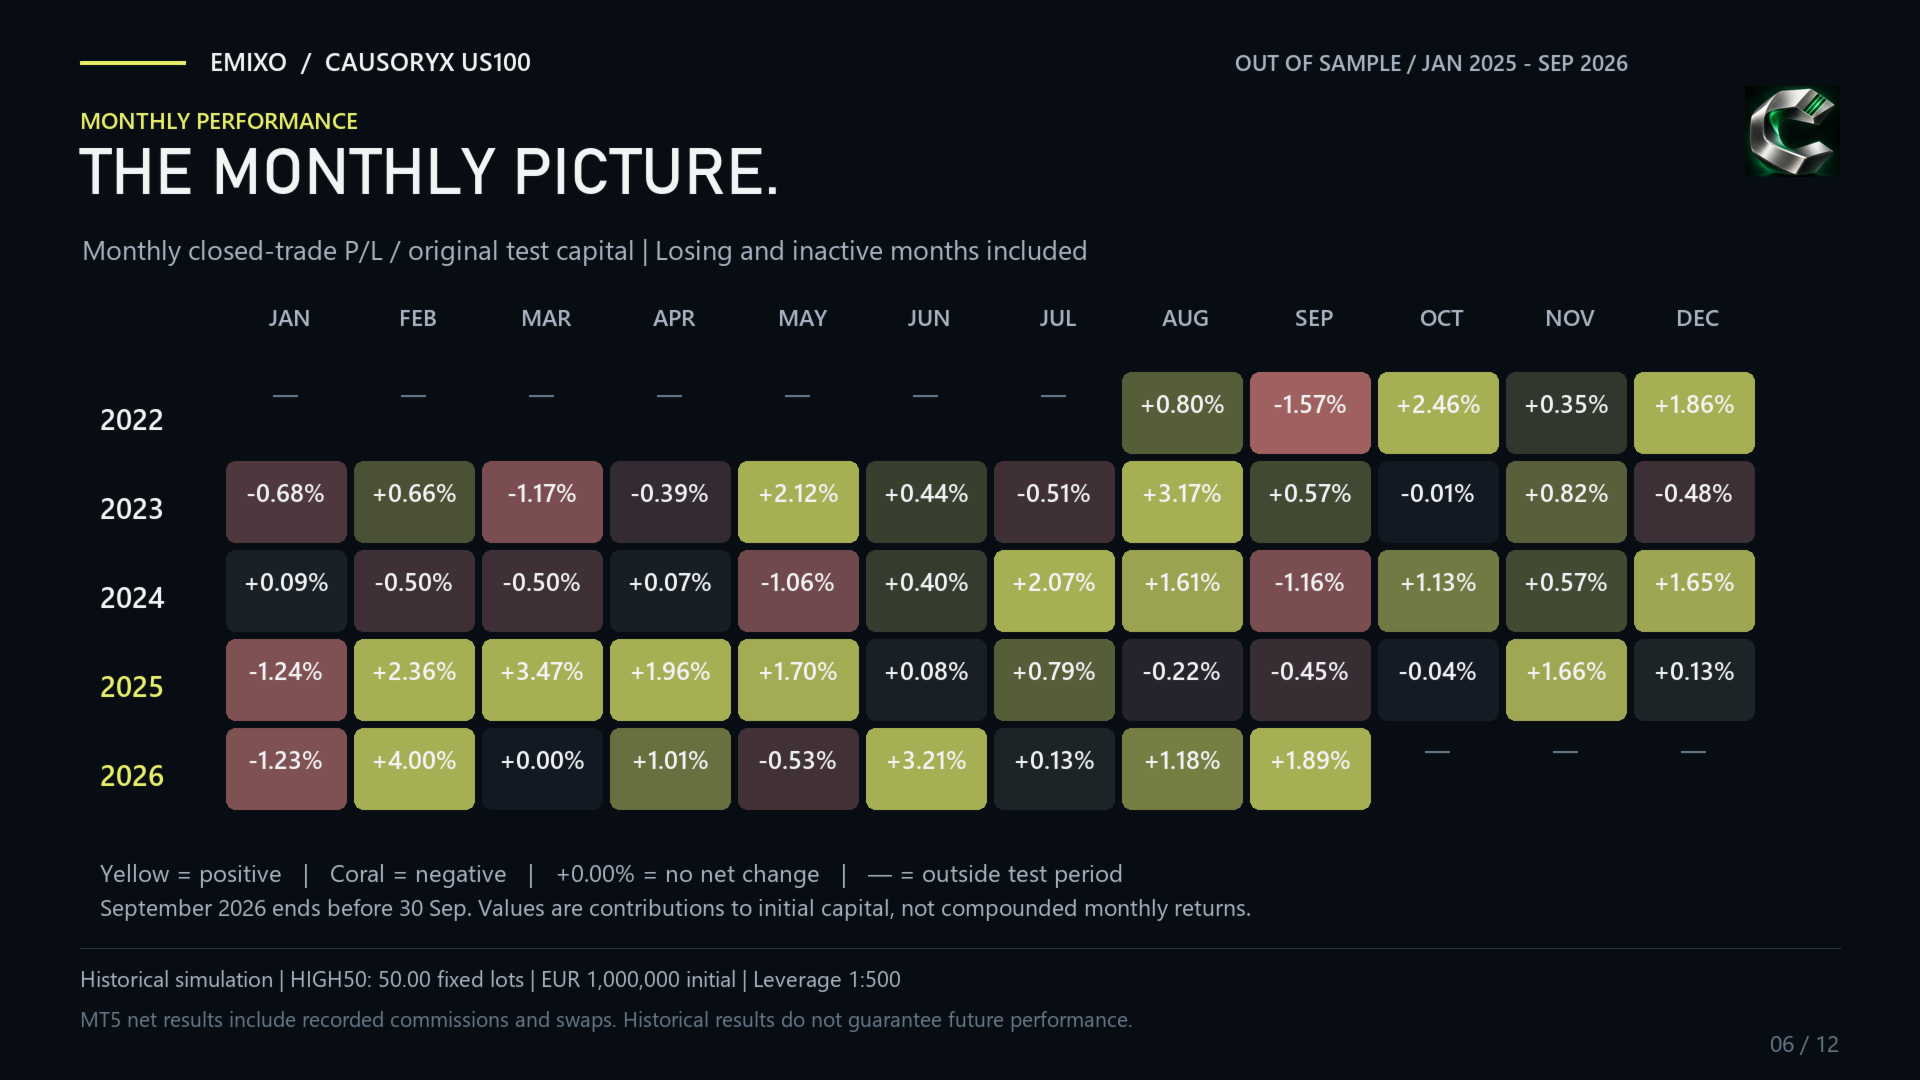
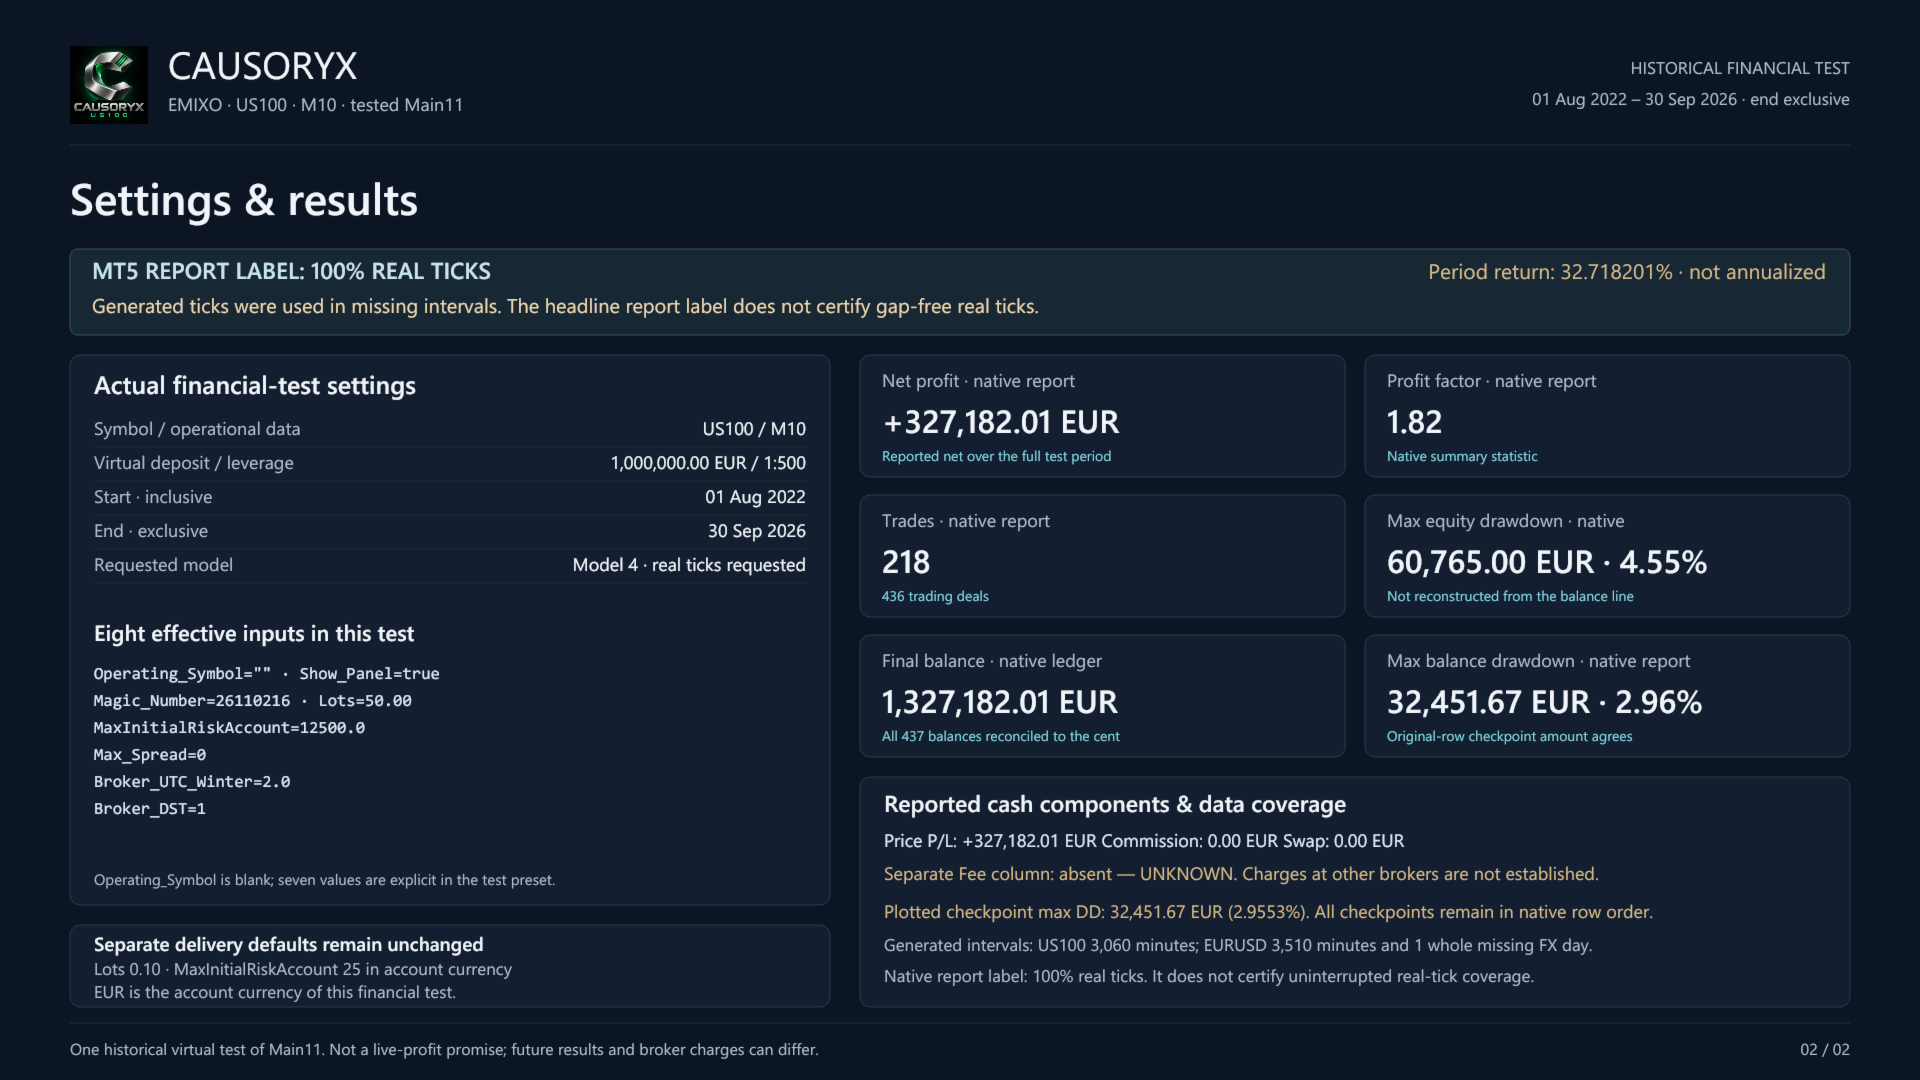
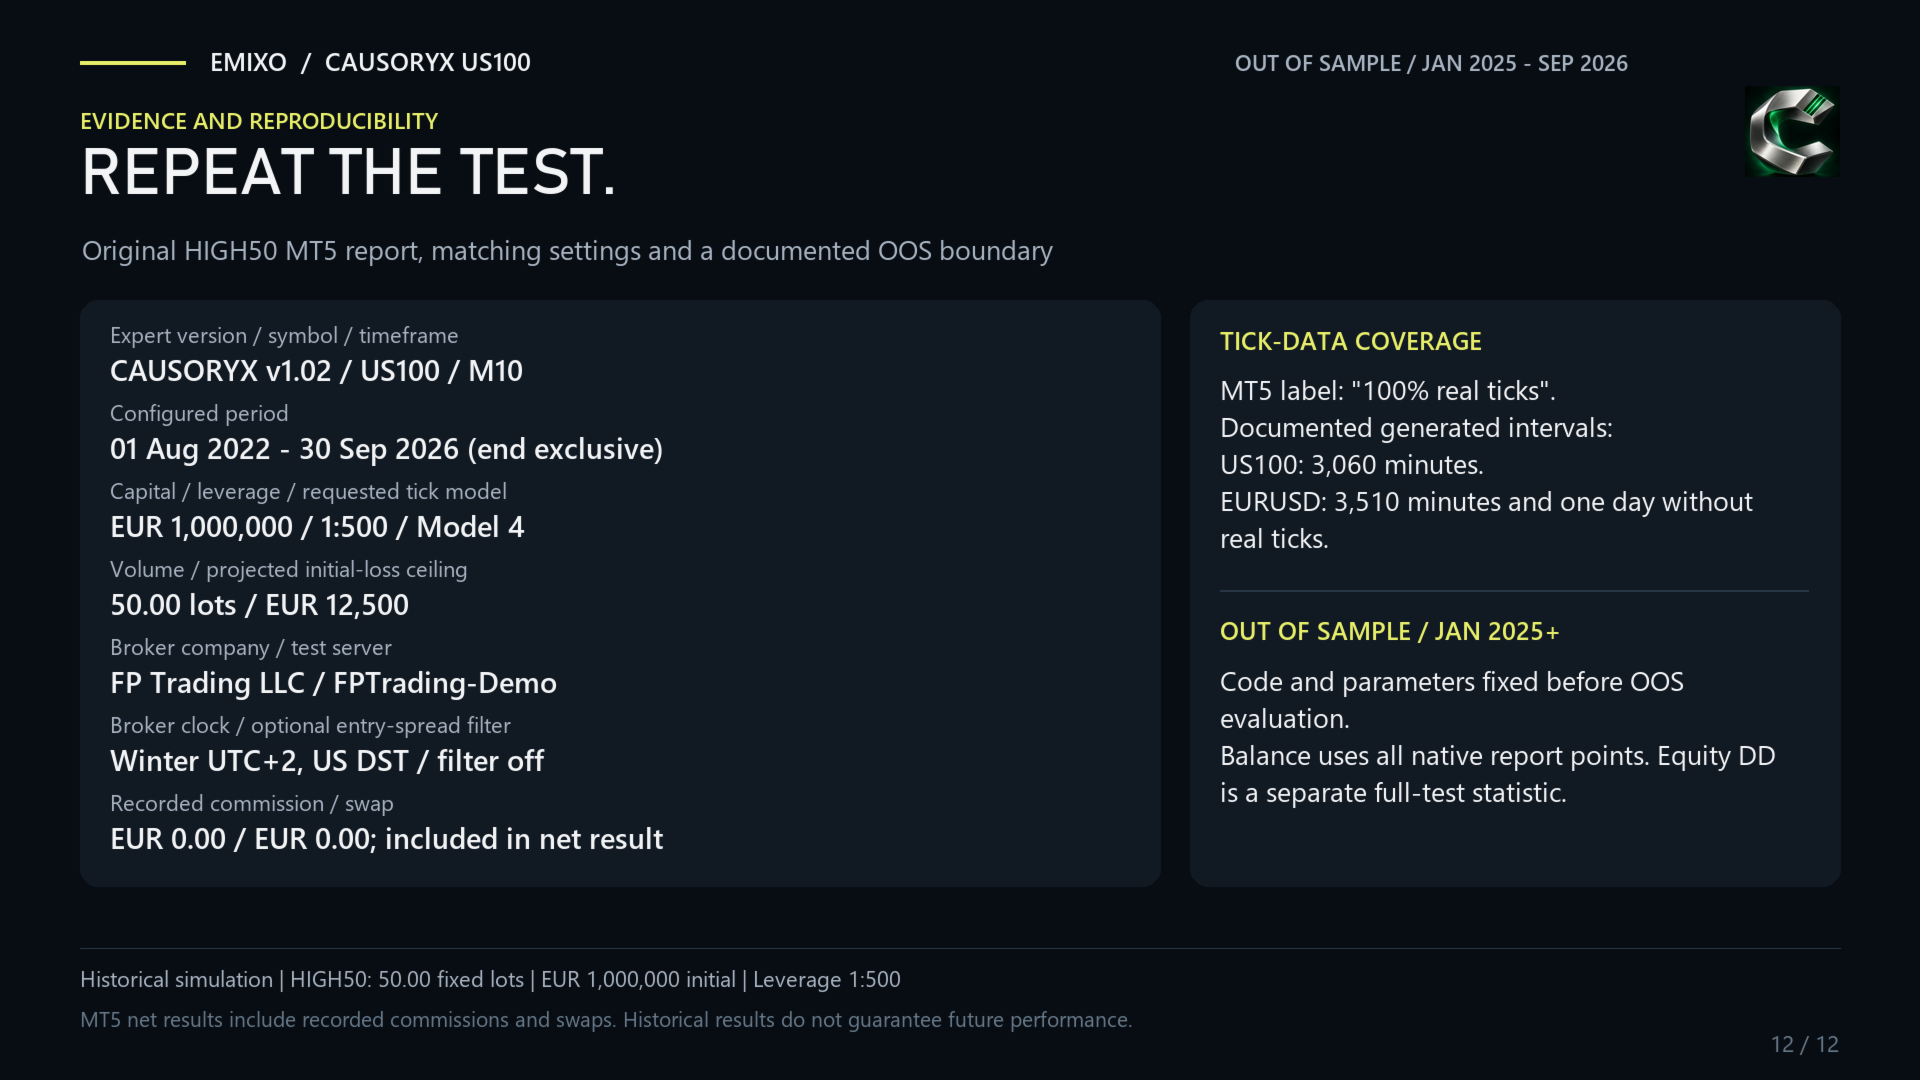
US100, 01 Aug 2022 – 30 Sep 2026 (end exclusive). Initial virtual capital EUR 1,000,000, leverage 1:500.
- Net result: +EUR 327,182.01.
- Full-period return: +32.72%, not annualized.
- Profit Factor / closed trades: 1.82 / 218.
- Maximum relative equity drawdown: 4.55%.
Test profile: 50 fixed lots and initial budget 12,500; defaults 0.10 lots and budget 25. Net figures include commission and swap recorded in the report. The historical profile is separate from the product's starting settings.
Getting started
Use the Market demo in the Strategy Tester to examine entries and exits with your broker's data. Before operational use, check the configuration on a demo account. For setup questions, contact the seller through MQL5 messages or product comments.
Trading involves a risk of loss. Backtests are historical simulations, not live results or forecasts. Spreads, costs and execution can change outcomes; stops and operating limits do not guarantee a maximum loss.