• Información
2 años
experiencia
4
productos
100
versiones demo
0
trabajos
1
señales
0
suscriptores
Profesional en Finanzas y Negocios Internacionales con especialización en Gestión Financiera. Desarrollador autodidacta en MQL5 y Python con enfoque en trading algorítmico, construcción de portafolios multi-activo y gestión cuantitativa de riesgo.

Mi trabajo se centra en el diseño, optimización y validación de Expert Advisors que operan de forma coordinada como portafolio. Aplico análisis de correlación, cobertura temporal y diversificación por clase de activo para construir sistemas que no dependan de un solo instrumento ni de una sola estrategia.
Actualmente gestiono portafolios algorítmicos que cubren forex, índices, metales, energía y acciones estadounidenses, operando en múltiples sesiones y marcos temporales de forma simultánea.

Comparto mi experiencia a través de artículos técnicos y herramientas de código abierto en esta comunidad. Creo que el salto de "construir EAs individuales" a "ingeniería de portafolios" es la transición que separa al trader retail del institucional, y esa es la línea que guía todo lo que publico aquí.
Cristian David Castillo Arrieta
Build your own portfolio and connect it to your demo (free) or live account.

www.abacuquant.com
Cristian David Castillo Arrieta
Ha publicado el código Execution Cost Sensitivity Analyzer
Un script escrito íntegramente en MQL5 que mide la solidez de la ventaja de una estrategia frente a los costes de ejecución. Lee un archivo CSV con los datos de fecha, beneficio y volumen de las operaciones cerradas y modela el coste de cada operación como una parte fija más una parte por lote. Muestra el coste de umbral de rentabilidad por operación, el margen de seguridad (el múltiplo de un coste realista supuesto al que el beneficio neto llega a cero), el beneficio neto y el factor de beneficio reajustados al coste supuesto, la proporción de operaciones ganadoras que el coste convierte en perdedoras, y una puntuación compuesta de A+ a F sobre la solidez frente a los costes, con recomendaciones. Si no hay ningún archivo, genera una muestra reproducible y la analiza, de modo que el resultado es visible desde la primera ejecución. Sin bibliotecas externas, sin Python, sin IA.
Cristian David Castillo Arrieta
Ha publicado el artículo Beyond Maximum Drawdown: Building a Drawdown DNA Analyzer in MQL5
Beyond Maximum Drawdown: Building a Drawdown DNA Analyzer in MQL5

Maximum drawdown is one number that hides what really matters: how often an equity curve declines, how long it stays below a previous peak, and how quickly it recovers. This article builds a native MQL5 tool that reconstructs the underwater curve, breaks it into individual drawdown episodes (depth, duration, recovery time), computes the Ulcer Index, Pain Index, and Recovery Factor, and combines them into a single resilience grade with practical recommendations. No external libraries, no Python, no AI.

Cristian David Castillo Arrieta Ha publicado el producto

Funded Trade Manager MT5 La mayoría de las cuentas financiadas no se pierden por una mala estrategia. Se pierden por un solo día en el que se fue demasiado lejos: una posición excesivamente grande, una operación de revancha, un límite de pérdidas diario superado. Prop Firm Guard es un panel de gráficos que aplica los mismos límites que aplica tu empresa de financiación, antes de que lo haga la propia empresa. Qué hace Realiza un seguimiento en tiempo real de tu límite de pérdidas diario y de tu

Cristian David Castillo Arrieta
Ha publicado el código Profit Concentration Analyzer
Un script nativo de MQL5 que mide el grado de concentración de los beneficios de una estrategia: si la ventaja es amplia o se basa en unas pocas operaciones afortunadas. Lee un archivo CSV con datos por operación (Fecha, Beneficio) y muestra el porcentaje de beneficio neto procedente de las operaciones más importantes, el coeficiente de Gini de las operaciones ganadoras, un perfil de concentración, una prueba de supervivencia que elimina las mejores operaciones y vuelve a calcular el beneficio neto y el factor de beneficio, y el mayor beneficio en un solo día frente a un límite de consistencia configurable, todo ello combinado en una puntuación de concentración y consistencia (de A+ a F) con recomendaciones. Si no se encuentra ningún archivo, genera un conjunto de datos de muestra, por lo que funciona nada más instalarlo. Sin bibliotecas externas, sin Python, sin IA. El programa auxiliar ExportTrades.mq5 genera el archivo a partir de tu historial de operaciones.
Cristian David Castillo Arrieta
Ha publicado el código Drawdown DNA Analyzer
Un script nativo de MQL5 que analiza la estructura de las caídas de una cuenta, y no solo la cifra aislada de la «caída máxima». Lee una curva de capital diaria (archivo CSV con Date y DailyPnL), reconstruye la curva «underwater» y la divide en episodios de caída individuales con su profundidad, duración y tiempo de recuperación. A continuación, calcula el Índice de Úlcera, el Índice de Dolor, el Factor de Recuperación y el tiempo pasado en «underwater», y los combina en una única puntuación de resiliencia (de A+ a F) con recomendaciones, que se muestran en la pestaña «Expertos». No requiere bibliotecas externas; si no se encuentra ningún archivo, genera una curva de muestra para que funcione desde el primer momento.
Cristian David Castillo Arrieta
Introduction: The Context-Blind Expert Advisor Problem A carefully optimized Expert Advisor completes six months of profitable forward testing. The equity curve is smooth, the drawdown is bounded, and the trade distribution looks healthy. On the first Friday of the seventh month, the EA opens a 0...
Cristian David Castillo Arrieta
This is the most power full EA
Cristian David Castillo Arrieta
Ha publicado el artículo Building a Correlation-Aware Multi-EA Portfolio Scorer in MQL5
Building a Correlation-Aware Multi-EA Portfolio Scorer in MQL5

Most algo traders optimize Expert Advisors individually but never measure how they behave together on a single account. Correlated strategies amplify drawdowns instead of reducing them, and coverage gaps leave portfolios blind during entire trading sessions. This article builds a complete portfolio scorer in MQL5 that reads daily P&L from backtest CSV files, computes a full Pearson correlation matrix, maps trading activity by hour and weekday, evaluates asset class diversity, and outputs a composite grade from A+ to F. All source code is included; no external libraries are required.

1
Cristian David Castillo Arrieta Ha publicado el producto

ABQ Portfolio Correlation Scorer: Inteligencia Artificial de Grado Institucional para la Gestión de Riesgo La mayoría de los traders no fracasan por una mala estrategia de entrada, sino por una falla invisible en la arquitectura de su portafolio . El error más común es la sobreexposición por correlación: abrir múltiples posiciones pensando que se está diversificando, cuando en realidad se está multiplicando el riesgo sobre un mismo factor. ABQ Portfolio Correlation Scorer es un Copiloto de

Cristian David Castillo Arrieta
ABQ Visual Risk Sizer - Official User Manual Author: Cristian Castillo | AbacuQuant Version: 1.60 Platform: MetaTrader 5 (MT5...
Cristian David Castillo Arrieta Ha publicado el producto

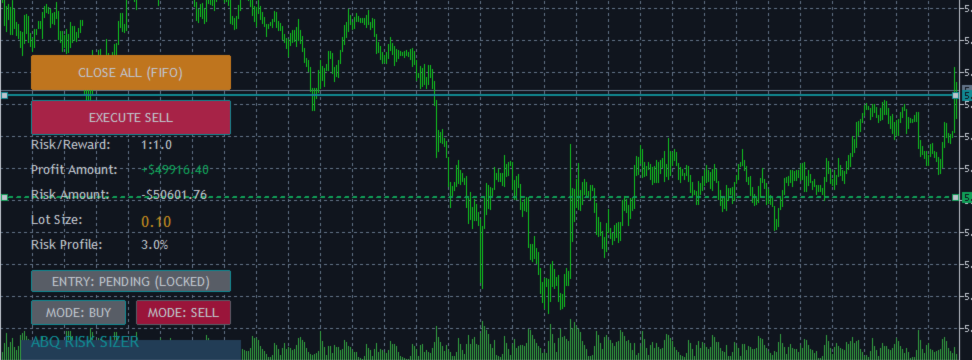
ABQ Visual Risk Sizer - Institutional Risk & Trade Execution Category: Utilities / Risk Management El calculo manual de lotes cuesta tiempo y dinero. En el trading moderno, especialmente al operar con cuentas de fondeo (Prop Firms), un error de calculo de lotaje o una demora de 5 segundos al introducir una orden puede significar violar la regla de Drawdown Diario o perder el precio de entrada perfecto. ABQ Visual Risk Sizer es una herramienta de grado institucional disenada para resolver

Cristian David Castillo Arrieta
Ha publicado el código Portfolio Scorer — Multi-EA Correlation and Coverage Analyzer
Portfolio Scorer is a standalone MQL5 script that evaluates the quality of a multi-EA portfolio across three critical dimensions that most algo traders overlook. The script reads daily profit and loss data from CSV files (one per Expert Advisor), computes a full Pearson correlation matrix between every strategy pair, maps trading activity by UTC hour and weekday, detects asset class diversity, and produces a weighted composite score with a letter grade from A+ to F. How it works: The tool runs in four sequential stages. First, the Data Loader reads and validates CSV files containing daily returns for each EA in the portfolio. Second, the Correlation Engine calculates the complete NxN Pearson correlation matrix and flags pairs that exceed a configurable threshold. Third, the Coverage Analyzer maps which hours and weekdays have active trading and identifies blind spots. Fourth, the Scoring Function combines all three dimensions into a single composite score using adjustable weights.
1 245
Cristian David Castillo Arrieta
It was late 2022. I had spent six months building what I believed was the perfect Expert Advisor. The backtest was gorgeous: Profit Factor 3.2, maximum drawdown under 5%, a Sharpe ratio that would make a hedge fund manager jealous . I had optimized every parameter. Every indicator period...
Cristian David Castillo Arrieta
AbacuQuant 3.7 — The Complete User Manual: From Installation to Live Portfolio A comprehensive, practical guide to configuring, optimizing, and deploying AbacuQuant — the institutional-grade algorithmic trading system for MetaTrader 5...
Cristian David Castillo Arrieta
AbacuQuant 4.10 — Complete User Manual & Setup Guide The definitive reference for installation, configuration, prop-firm compliance, local AI setup, portfolio analysis, and live deployment. LIVE SIGNAL: CLICK HERE Table of Contents Introduction — What's New in v4...
Cristian David Castillo Arrieta Ha publicado MetaTrader 5 señal
AbacuQuant
Precio: 30 USD, Incremento: 6.63%
AbacuQuant: Systematic Trading with Institutional Discipline Why most traders fail—and why AbacuQuant is different. The financial markets punish emotion. Fear triggers early exits. Greed extends losing positions. Fatigue leads to missed opportunities. Over 90% of retail traders lose money not because they lack intelligence, but because they lack discipline. AbacuQuant eliminates the human factor entirely. A Portfolio-Based Approach to Algorithmic Trading AbacuQuant is not a single strategy
Cristian David Castillo Arrieta
🔍 The One Question Every Trader Asks — And Why Most Never Find the Answer

“Are my settings actually working… or am I just lucky?”
Be honest. You’ve been there.
You find a strategy that looks promising. You tweak a moving average here, adjust a stop loss there, maybe change the timeframe. It works for a week. Then the market shifts — and everything falls apart.
So you start over. Again.
This isn’t a failure of discipline. It’s a failure of process. Manual optimization is a guessing game disguised as analysis. You’re testing a handful of combinations out of thousands — maybe millions — of possibilities. The odds of landing on the best parameters by hand? Almost zero.

What If Your EA Could Find the Answer for You?
This is exactly the problem AbacuQuant was built to solve.
AbacuQuant doesn’t just give you a strategy. It gives you a framework to discover the optimal version of that strategy — for any instrument, on any timeframe, under real market conditions.
Here’s how:
→ One EA. 10+ Built-In Strategies.
From Fibonacci confluences and imbalance detection to Bollinger reversals and candlestick pattern recognition — AbacuQuant packs institutional-grade strategies into a single Expert Advisor. You don’t need ten different EAs. You need one that adapts.
→ Full Optimization Power Across Any Market.
EURUSD on H1? Gold on M15? NASDAQ on H4? It doesn’t matter. AbacuQuant’s architecture is instrument-agnostic and timeframe-flexible. Run the MetaTrader 5 Strategy Tester, and let the optimization engine do what no human can: test thousands of parameter combinations systematically to surface the configurations that actually perform — not the ones that just look good on a single backtest.
→ AI-Assisted Analysis to Confirm What the Data Shows.
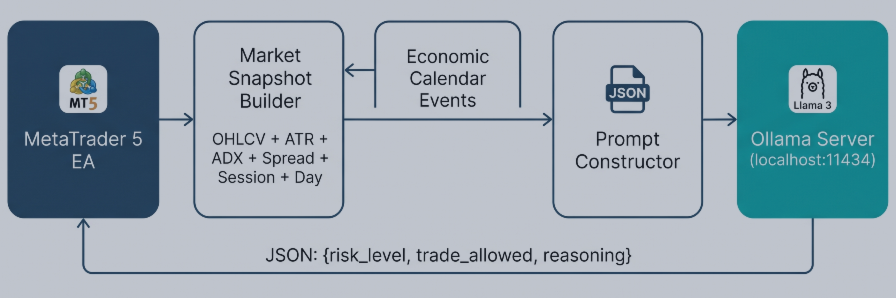
Here’s where it gets powerful. AbacuQuant integrates directly with AI models (OpenAI, Google Gemini, DeepSeek) to provide a second layer of confirmation. Before entering a trade, the AI analyzes current market context — trend structure, volatility regime, key levels — and validates whether the signal aligns with broader conditions. It’s like having a senior analyst reviewing every setup before execution.

The Real Edge Isn’t the Strategy. It’s the Process.
Most traders spend years searching for the “perfect” strategy. The truth? No single set of parameters works forever. Markets evolve. What separates profitable traders from the rest is the ability to re-optimize, re-validate, and re-deploy — quickly and confidently.
With AbacuQuant, that process looks like this:
1. Select your instrument and timeframe.
2. Run optimization using the MT5 Strategy Tester with your preferred criteria.
3. Analyze the results — filter by profit factor, drawdown, recovery factor.
4. Enable AI confirmation to add a layer of contextual intelligence.
5. Deploy with confidence, knowing your parameters are data-driven, not gut-driven.
Whether you’re building a single-instrument setup or constructing a diversified multi-asset portfolio, AbacuQuant scales with you.

Don’t Take Our Word for It. Test It Yourself.
AbacuQuant is available for free download in demo mode on the MQL5 Market. No commitment. No risk. Just results you can verify on your own charts, with your own instruments, on your own terms.

👉 Download the demo now and run your first optimization today.
Because the best time to stop guessing was yesterday. The second best time is right now.