• 정보
2 년도
경험
4
제품
102
데모 버전
0
작업
1
거래 신호
0
구독자
재무 및 국제 비즈니스 전문가로 재무 관리를 전공했습니다. MQL5와 Python 독학 개발자로서 알고리즘 트레이딩, 멀티에셋 포트폴리오 구축, 정량적 리스크 관리에 집중하고 있습니다.

저의 작업은 개별 전략이 아닌 조율된 포트폴리오로 작동하는 Expert Advisor의 설계, 최적화 및 검증에 중점을 두고 있습니다. 상관관계 분석, 시간대 커버리지 매핑, 자산군 분산화를 적용하여 단일 상품이나 단일 접근 방식에 의존하지 않는 시스템을 구축합니다.

현재 외환, 지수, 귀금속, 에너지, 미국 주식을 아우르는 알고리즘 포트폴리오를 관리하고 있으며, 여러 세션과 타임프레임에서 동시에 운용하고 있습니다.
이 커뮤니티에서 기술 기사와 오픈소스 도구를 통해 제 경험을 공유하고 있습니다. "개별 EA 구축"에서 "포트폴리오 엔지니어링"으로의 전환이야말로 개인 투자자의 사고와 기관 투자자의 사고를 구분짓는 경계선이라 확신하며, 이 원칙이 제가 이곳에서 발행하는 모든 것의 지침이 됩니다.Has usado 75% de tu límit
Cristian David Castillo Arrieta
Don’t trust screenshots. Break it in your own Strategy Tester.

Most EAs on the Market hide behind a single cherry-picked curve or mask bad entries with grids and martingale. AbacuQuant Portfolio was built by rejecting 22 out of 39 researched markets that failed real-tick validation, leaving only 11 statistically proven assets (Forex, Gold, and Global Indices) running 71 independent configurations from a single H1 chart.

I invite you to audit the engine for free right now:

Download the free demo and open the MT5 Strategy Tester.

Select "Every tick based on real ticks" from Jan 2020 to today on your own broker.

Attach it to EURUSD H1 and enable the validated presets (EURUSD, USDJPY, AUDUSD, EURJPY, XAUUSD, WS30, NDX, N225, AUS200, STOXX50, UK100).

Check the trade list yourself: verify the fixed Stop Loss on every single deal, the ATR-based position sizing, and how the global risk ceiling protects the account across all sessions.

Whether you trade personal capital or Prop Firm challenges, test the math before you commit a cent.

👉 Download the Free Demo & Read the Full Methodology:
https://www.mql5.com/en/market/product/191885

Questions about broker symbol suffixes or GMT offset? Drop a comment on the product page and I’ll help you configure your test.

#MQL5 #MetaTrader5 #AlgoTrading #QuantTrading #PortfolioManagement #NoMartingale #AbacuQuant
Cristian David Castillo Arrieta
🚀 How many hours and resources do you spend designing, testing, and optimizing separate trading strategies for every single market?

In algorithmic trading, the real bottleneck isn’t finding a good idea—it’s scaling it with robust, unified risk management without falling into analysis paralysis.

While developing AbacuQuant Portfolio for MetaTrader 5, our core objective was clear: eliminate unnecessary complexity and automate diversification with mathematical rigor. 

What will you discover and how much time will you save by testing it?

A single global risk engine: Forget manual lot calculations or managing disconnected exposures across multiple charts. Everything is centralized to protect your trading capital.

Zero destructive practices: No martingale, no grid, and no averaging down. Just clean, professional execution driven by strict rules. 

Multi-currency & multi-asset from a single H1 chart: Trade multiple markets simultaneously with flawless synchronization. 

💡 Quick tips for testing the demo effectively:

1. Start with the default settings: They are structured for you to evaluate the native behavior of the system right out of the box without tweaking complex input parameters.

2. Test on one of the 11 validated instruments: We recommend starting with major forex pairs (like EURUSD or USDJPY) or the built-in stock indices to witness the engine's precision in action.
 
Don't just read about quantitative optimization—test it yourself in the Strategy Tester and experience a massive reduction in strategy validation time.

👉 Download the free demo here and take your trading to the next level:

https://www.mql5.com/es/market/product/191885?source=Site+Profile+Seller#!tab=overview 
#MQL5 #MetaTrader5 #AlgorithmicTrading #QuantitativeTrading #RiskManagement #AbacuQuant
Cristian David Castillo Arrieta
https://www.mql5.com/en/market/product/191885 Understanding System Expectancy: Live Performance, Drawdowns, and Long-Term Edge The animation above displays a focused test run using ABQ Portfolio , trading strictly on EURUSD with a fixed 2% risk per trade...
Cristian David Castillo Arrieta
This test was conducted with ABQ Portfolio using only EURUSD at 2% risk per trade. To replicate this equity curve, simply set the instrument you want to test to True, or leave it on Default if you want to include all available pairs. Download the free demo and verify the results yourself: https://www.mql5.com/en/market/product/191885

On a live account, the behavior is identical. However, consecutive losing streaks can sometimes create the impression that the system is failing. It is crucial to evaluate this system over the long term: over time, total gains outweigh total losses, as shown in the chart.
en cuenta real esta funcionando igual pero hay momentos donde muchas perdidas seguidas dan la sensacion que el sistema pierde es importante ver este sistema de resultados a largo plazo a la final la cantidad de ganancias superan a la cantidad de perdidas como se ve en la imagen, cada operacion tiene su stop loss, no hay martingala, ni grid, ni ningun sistema tramposo de recuperacion, ademas del riesgo por operacion que es configurable en los parametros hay un stop global en caso que toda la cuenta llegue a ese valor, en mi caso lo tengo en un 30%
Cristian David Castillo Arrieta
게재된 코드 Marginal Drawdown Contribution Analyzer
A script for accounts that run several Expert Advisors or configurations. It aggregates the net result of each configuration (magic number, or magic number and symbol) per calendar day and measures how much each one contributes to the portfolio drawdown: drawdown added by leave-one-out, share of the worst drawdown, and Euler variance share. It prints verdicts, recommendations, and a heuristic A+ to F score. It runs out of the box on a built-in demonstration portfolio and is written in pure MQL5.
Cristian David Castillo Arrieta
Still watching the charts all day, switching between markets, and making every trading decision yourself?

Meet **AbacuQuant Portfolio** — an Expert Advisor for MetaTrader 5 designed to manage 11 researched markets from a single H1 chart, with account-level risk controls.

✅ 11 researched markets
✅ One H1 chart
✅ No martingale. No grid. No recovery logic.

**Don't take our word for it. Test the free demo yourself.**

👉 Explore AbacuQuant Portfolio on MQL5: https://www.mql5.com/en/market/product/191885

*Historical testing does not guarantee future results. Trading involves risk of loss.*

#MetaTrader5 #AlgorithmicTrading #ForexTrading #TradingEA #AbacuQuant
Cristian David Castillo Arrieta
게재된 포스트 Why I rejected 22 of the 39 markets I tested for an MT5 portfolio EA
Most Expert Advisor pages show you the markets that worked. This post is about the ones that didn't. For Abacuquant Portfolio I researched 39 markets. Twenty-two were rejected. Eleven made it into the product, and six more are still waiting for validation...
Cristian David Castillo Arrieta
게재된 포스트 A 90% Win Rate can still loss Money:
On many Expert Advisor pages, the first number you see is the win rate: 85%, 90%, 95%. It is the easiest number to sell, because being right most of the time feels like safety. It is also the number that hides the most risk...
Cristian David Castillo Arrieta
I researched 39 markets for AbacuQuant Portfolio. I rejected 22 of them.

Crude oil, the S&P 500, the DAX, ten US stocks. Some looked great on paper, then failed the real-tick test or the statistical screening. AUDJPY missed one threshold by 0.004 and was rejected anyway. The rules don't bend to let a market in.

That's the point. Many EAs are sold on the best backtest that could be found. This one is built from what survived a process designed to say no.

What made it in:
• 11 validated markets: EURUSD, USDJPY, AUDUSD, EURJPY, gold and six indices (Dow Jones, Nasdaq 100, Nikkei 225, Australia 200, Euro Stoxx 50, FTSE 100)
• 71 independent configurations running from one H1 chart
• Account-level risk control: global limits on total open risk, margin and equity drawdown across every market
• Stop loss and take profit attached to every order. No martingale, no grid, no averaging, no recovery logic

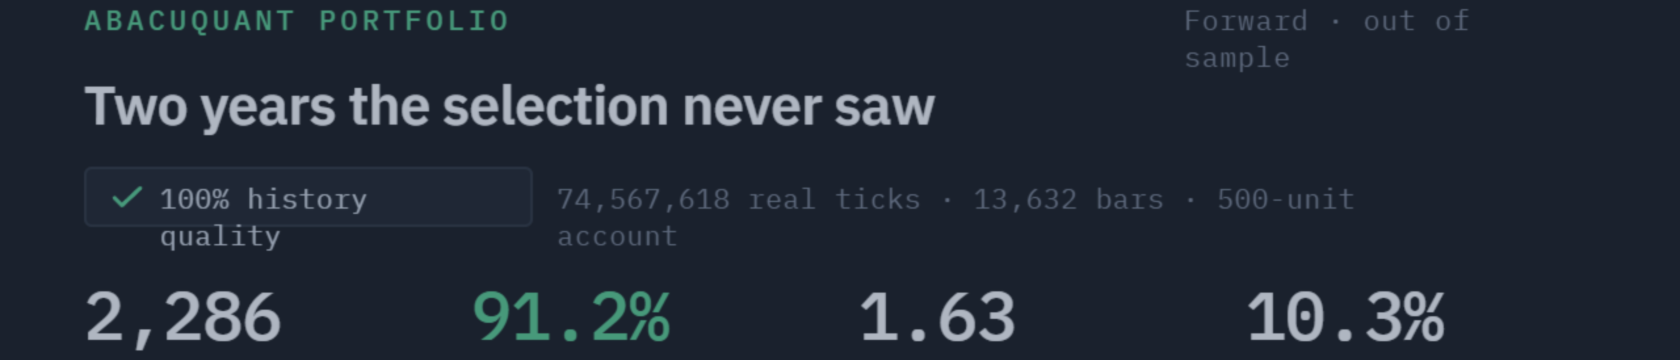
The numbers (Strategy Tester, real ticks, 0.5% risk per trade, Jan 2020 – Jul 2026):
• 11,333 trades, 80.3% win rate
• Deepest equity decline: 6.4%
• Most recent period (May 2024 – Jul 2026): profit factor 1.38, 24 of 27 months positive, all 11 markets in profit, none above 14% of the total

The trade-off, stated plainly: the average loss is about 2.8x the average win. You will see losing trades. If you want an equity curve with no visible losses, this is not your EA.

Why test it: the demo is free. Run it with "Every tick based on real ticks", on your own broker, with the balance you actually plan to trade. The EA tells you at startup what balance each configuration needs. Look closely at the losing trades.

Why get the full version: it's a research framework, not just a set of presets. Manual mode gives you the same engine, and a custom optimization criterion ranks results by the win rate's margin over its own break-even level instead of net profit. New markets are added only if they pass the same tests, and you get direct support from me in English and Spanish. I have been running this engine on my own real-money account since August 2026.

Free demo, full methodology and pricing (rental from 49 USD/month):
https://www.mql5.com/en/market/product/191885

Backtests describe the past, not the future. Trading involves risk of loss.
Cristian David Castillo Arrieta
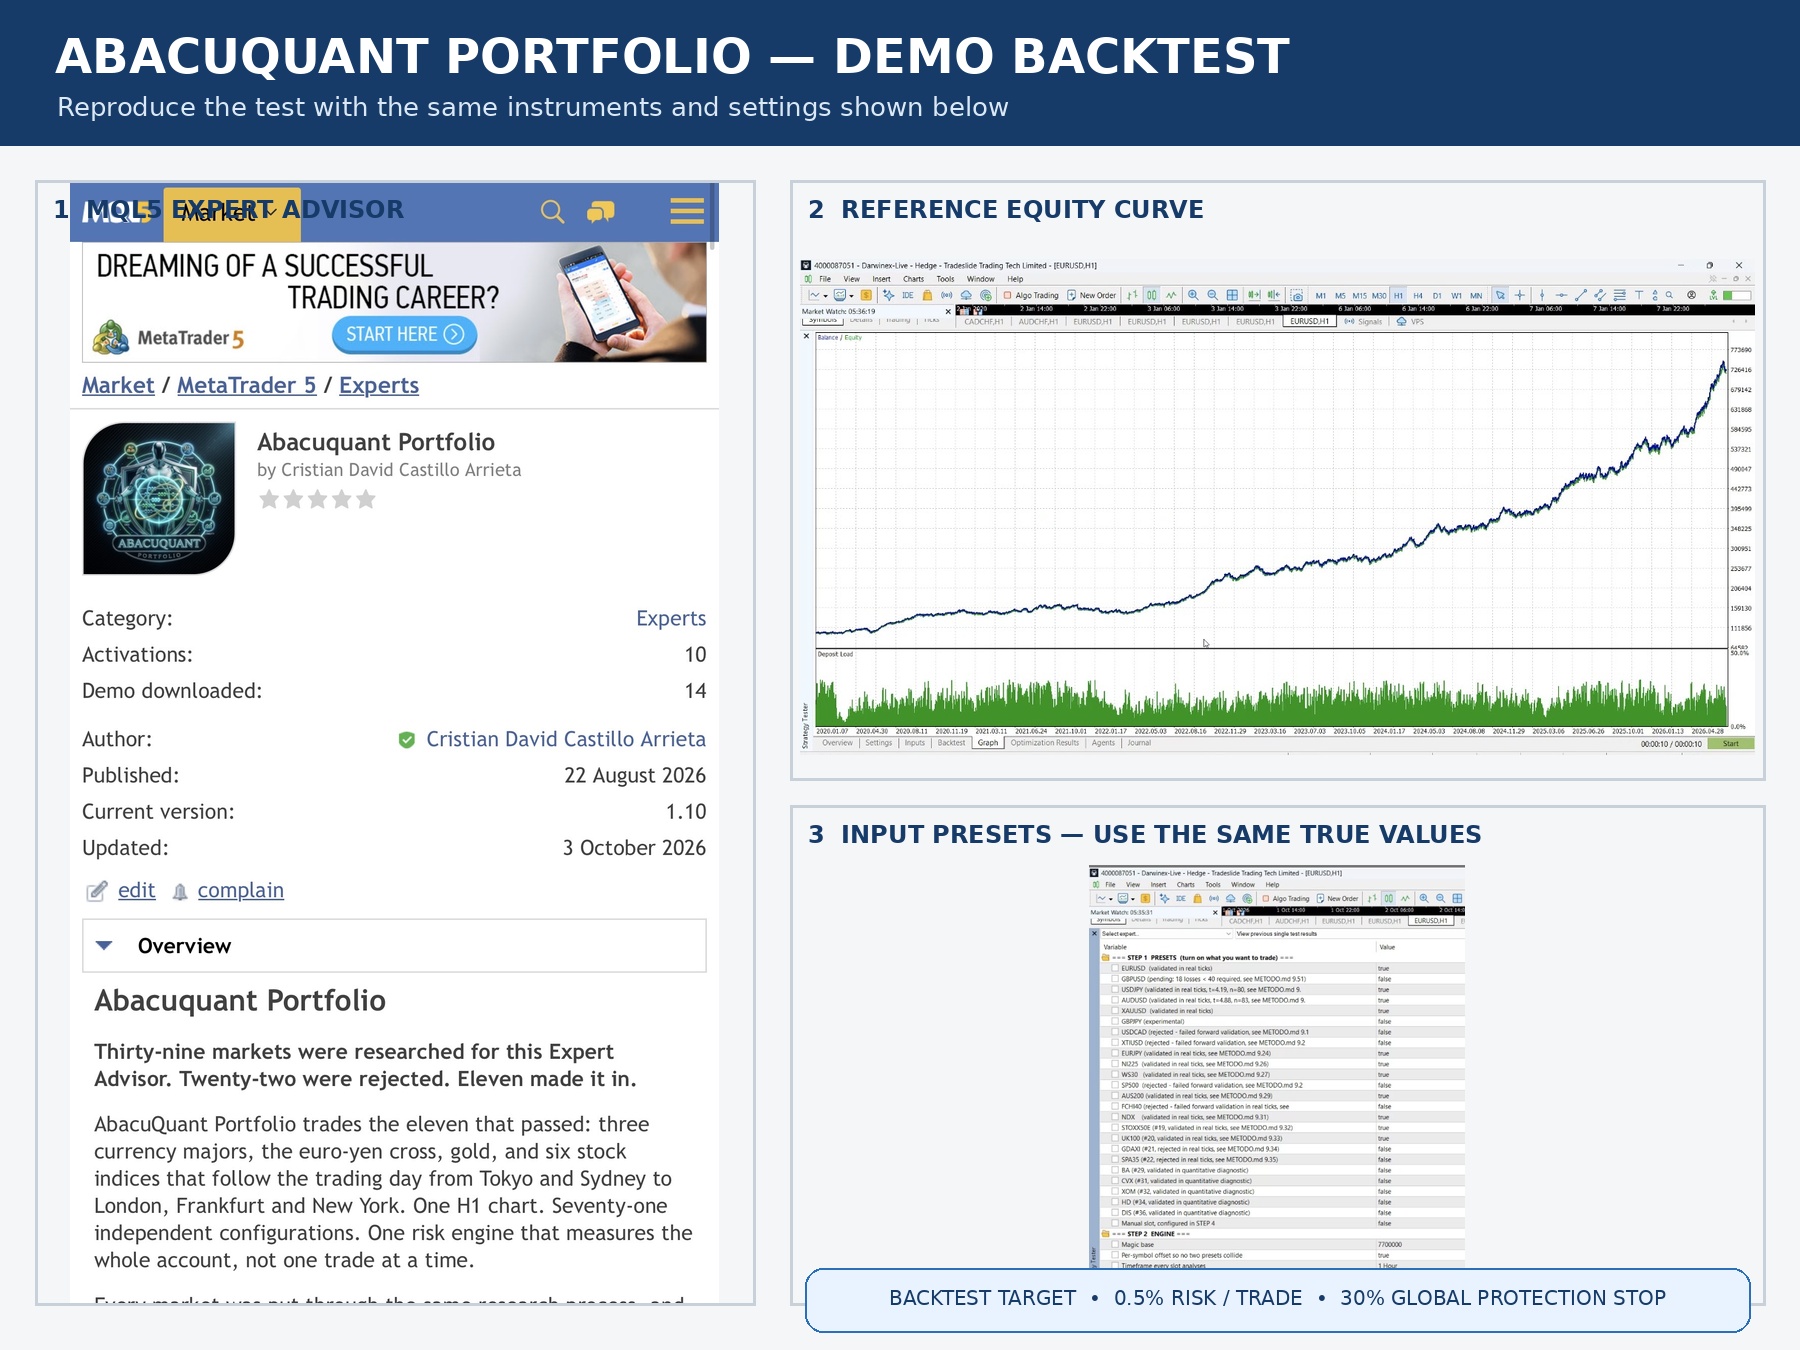
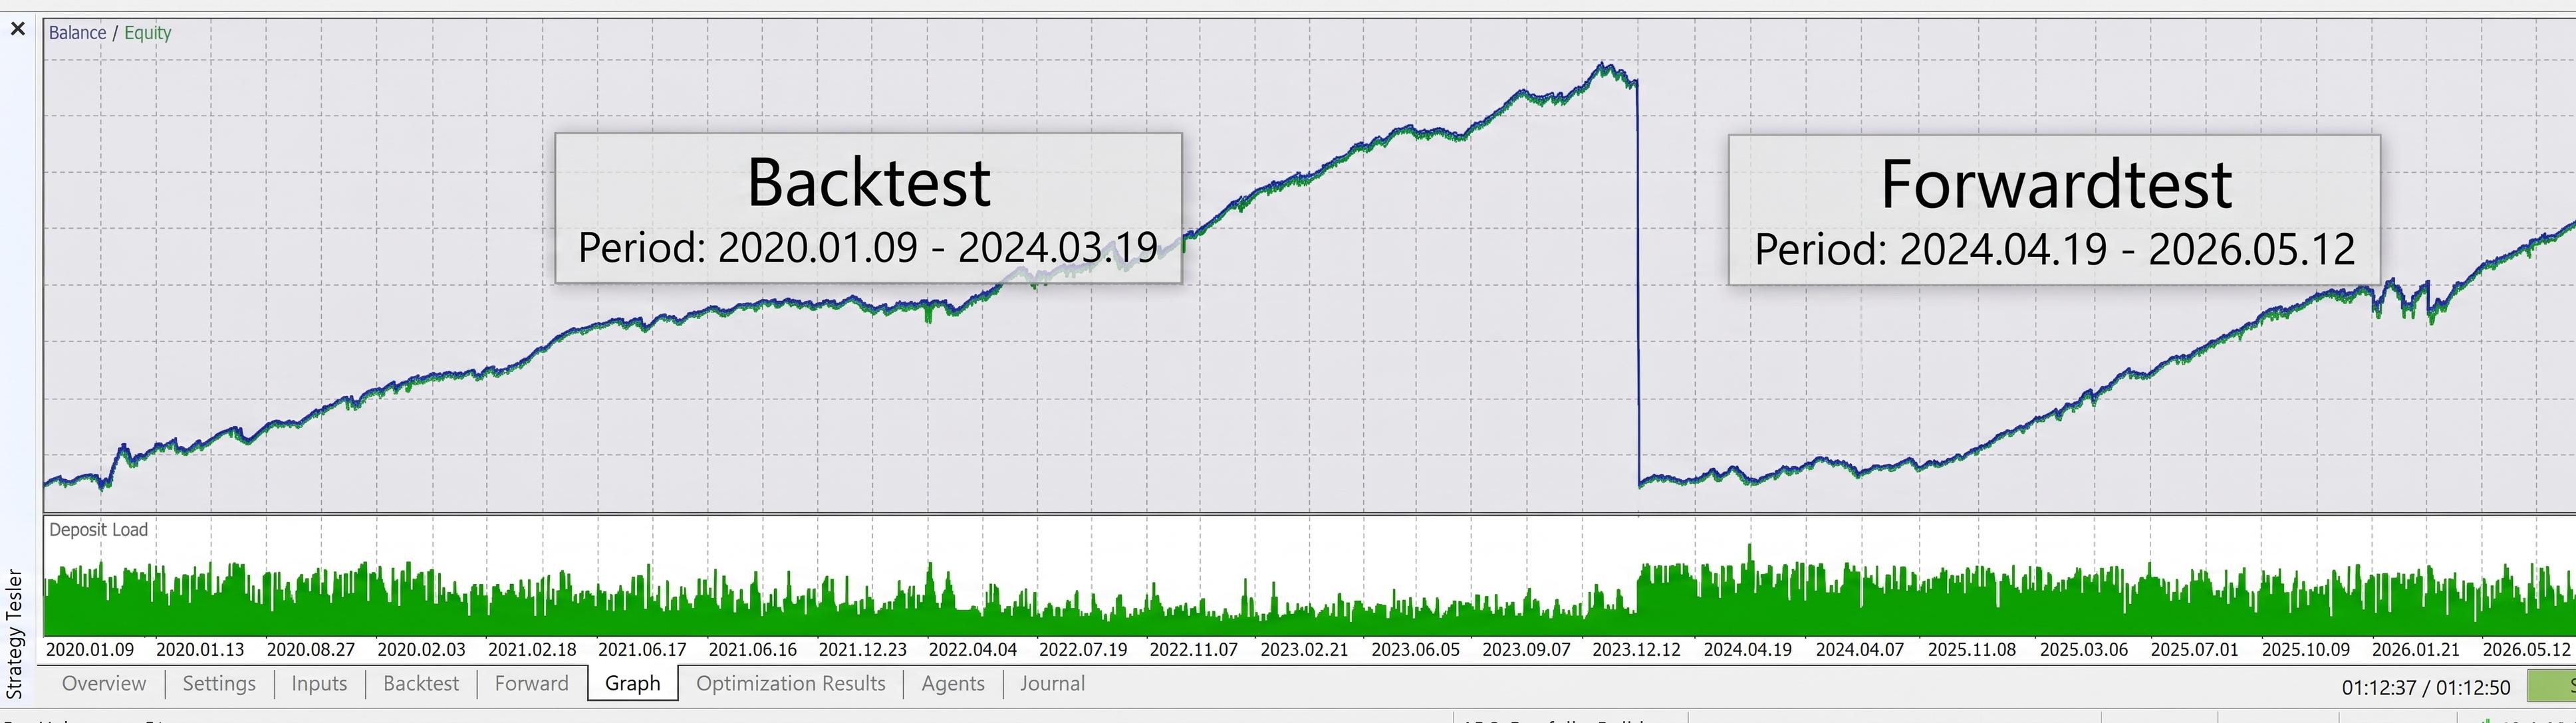
Can you reproduce this equity curve?

I’m sharing the backtest setup I used with AbacuQuant Portfolio so anyone can download the demo and try to reproduce the results independently.

You can test the instruments one by one if you want to analyze each market separately.

However, if you want to reproduce the portfolio configuration shown in the backtest, set the following instruments to TRUE:

* EURUSD
* USDJPY
* AUDUSD
* XAUUSD
* EURJPY
* N225
* WS30
* NDX
* STOXX50
* UK100

All other instrument presets should remain FALSE.

Risk settings used

Risk per trade: 0.5%

General protection stop: 30%

The idea is simple: don’t just look at the equity curve — download the demo and test it yourself.

Use the same instruments and settings shown above and see what results you get on your own MT5 environment.

Different brokers, spreads, commissions and execution conditions can affect the results, so your backtest may not be identical to mine.

I would actually encourage you to challenge the results.

Test the instruments individually. Test the portfolio. Change the parameters. Stress-test it.

The goal of AbacuQuant Portfolio is not to ask you to blindly trust a backtest.

It’s to give you something you can test for yourself.

👉 Download the demo and start your own backtest.

AbacuQuant Portfolio — available on MQL5.
Cristian David Castillo Arrieta
Anyone who has spent a few months with automated trading has seen the same pattern: a backtest with a smooth, steep equity curve, followed by a live account that behaves nothing like it. In most cases, the cause is one of three things: Loss recovery...
Cristian David Castillo Arrieta
게재된 코드 Edge Drift Detector
Tests whether live closing deals still match the backtest of an Expert Advisor. A bootstrap-calibrated CUSUM detector raises an alarm and estimates when the drift began, a two-window check separates a short dip from a lasting decline, and an expectancy decomposition shows whether the win rate or the trade sizes changed. The script generates demonstration data on the first run and is written in pure MQL5.
Cristian David Castillo Arrieta
게재된 기고글 Building a Neural Loss-Pattern Auditor in MQL5
Building a Neural Loss-Pattern Auditor in MQL5

Aggregate metrics like win rate or profit factor miss sequence-dependent behavior, such as sizing up right after a loss. This MQL5 script trains a small native neural network on closed-deal history to estimate loss probability from behavioral and market-context features. It reports accuracy uplift over a baseline, probability calibration, and permutation feature importance, then combines them into a configurable A-F grade with concise, plain-language recommendations.

Cristian David Castillo Arrieta
게재된 기고글 Did Your Scale Outs Actually Help? A Scale Out Value Analyzer in MQL5
Did Your Scale Outs Actually Help? A Scale Out Value Analyzer in MQL5

The article presents an MQL5 tool that tests whether scaling out improved results rather than only appearing disciplined. It reconstructs positions from closing-deal history and reprices the full volume at the first, last, and best exit rates actually achieved, producing a Value-Add Ratio, a Scale-Out Win Rate, and an Efficiency measure. A single-trade dependence check and a configurable A+ to F grade turn these into clear, decision-ready feedback.

Cristian David Castillo Arrieta
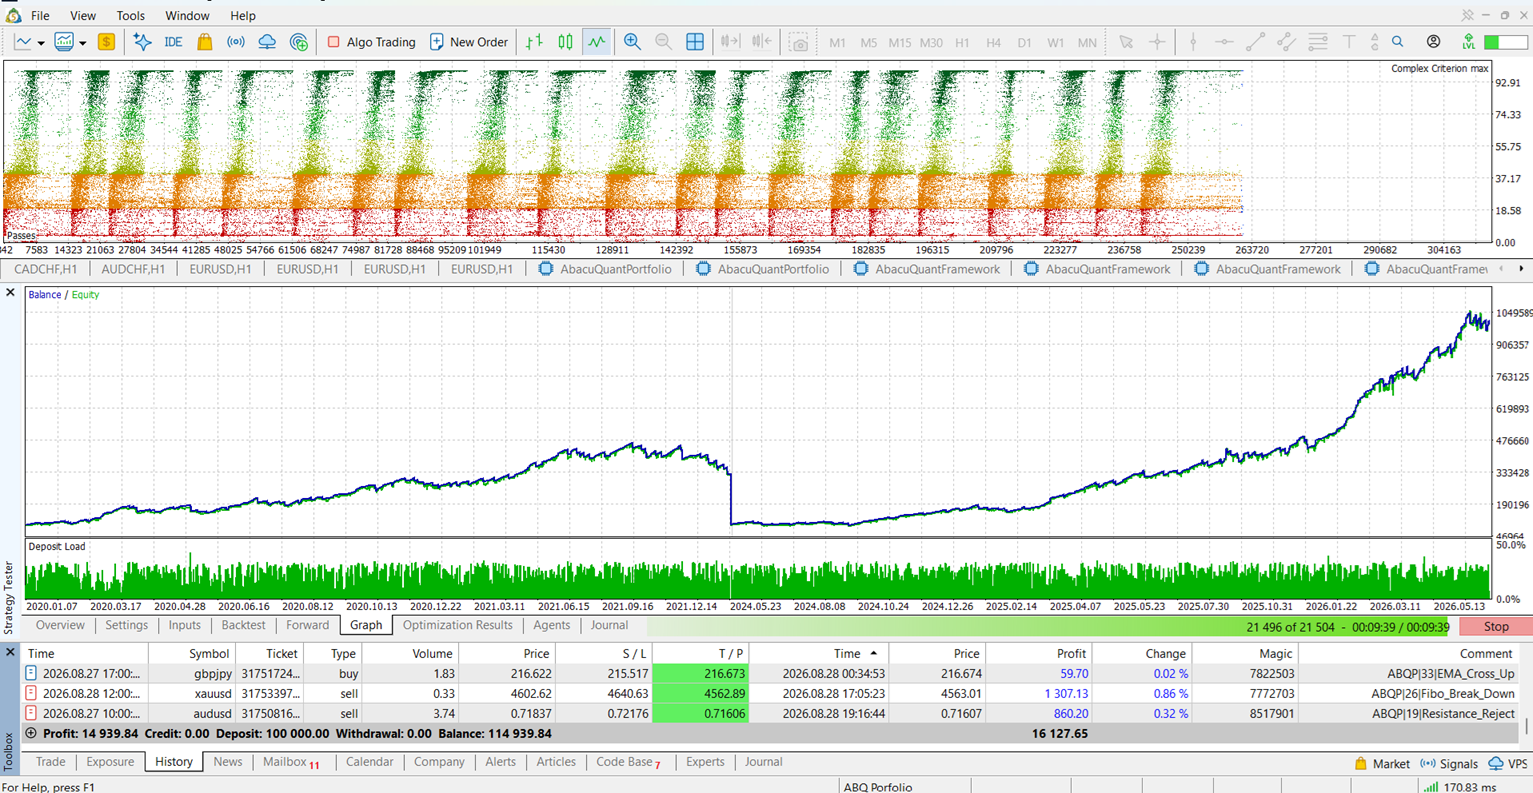
These remarkable optimization results were generated using the AbacuQuant Portfolio EA, available here:
What makes this interesting is that this is not a single strategy being optimized over and over. AbacuQuant Portfolio is designed as a portfolio engine, capable of running multiple independent configurations across different instruments and market conditions from a single MT5 chart.
The process starts by testing different combinations of strategies, trading conditions, parameters, stop/target structures and risk settings. Instead of simply looking for the configuration with the highest profit, AbacuQuant uses a custom optimization criterion designed to evaluate whether the historical win rate provides a meaningful margin above the break-even level implied by the stop and target structure.
The resulting configurations are then combined into a portfolio, allowing different strategies and instruments to operate during different market sessions while a shared risk engine controls total exposure at the account level.
The objective is not to find one “perfect” setup. It is to build a collection of independent configurations that complement each other and create a more robust portfolio.
This image shows one of those optimization and portfolio-development results. The robot used to generate it is the AbacuQuant Portfolio EA.
🔗 https://www.mql5.com/en/market/product/191885
Cristian David Castillo Arrieta
게재된 코드 Neural Loss-Pattern Auditor
Neural Loss-Pattern Auditor는 네이티브 MQL5로 처음부터 직접 작성된 소규모 피드포워드 신경망을 과거 체결된 거래 내역을 기반으로 학습시켜, 행동 및 시장 맥락 특성이 어떤 거래가 손실을 입을 가능성이 더 높은지 예측할 수 있는지 테스트합니다. 이 도구는 단순한 기준 모델, 확률 보정 테이블, 순열 특징 중요도 순위, 그리고 권장 사항이 포함된 구성 가능한 A-F 복합 등급에 비해 정확도가 향상되었음을 보여줍니다. 첫 실행 시 내장된 합성 데모 데이터를 사용하므로 별도의 설정 없이도 결과를 즉시 확인할 수 있습니다. 대신 실제 계좌 내역을 분석하려면 입력값 중 하나를 InpUseDemoData=false로 설정하십시오. 순수 MQL5: 외부 라이브러리, 파이썬, 어떠한 종류의 AI 서비스도 사용하지 않습니다.
Cristian David Castillo Arrieta
Introduction AbacuQuant Portfolio is a multi-configuration Expert Advisor for MetaTrader 5. Instead of running one strategy with one set of parameters on one instrument, it runs up to 48 independent configurations at the same time, across EURUSD, GBPUSD, USDJPY and AUDUSD, from a single H1 chart...
Cristian David Castillo Arrieta
After months of research, I've published AbacuQuant Portfolio — a multi-configuration Expert Advisor for MetaTrader 5, and I wanted to share it here first.

Why it's different

Most EAs run one strategy with one set of parameters on one instrument. This one runs up to 48 independent configurations at once, across EURUSD, GBPUSD, USDJPY and AUDUSD, from a single chart. Each configuration owns its own trading hours, its own combination of ten built-in strategies, and its own ATR-based stop and target. A configuration built for the London session simply doesn't trade outside it — and risk is measured across the whole account, not per configuration, so running four instruments together doesn't quietly multiply your exposure.

And it's built the honest way: no martingale, no grid, no averaging into a losing position, no hidden loss-recovery logic. Every stop is attached the moment the trade opens. If you've been burned by an EA with a beautiful equity curve that fell apart the first time the market disagreed with it, this was built specifically against that failure mode.

How it decides a trade

Each active configuration waits for its window, reads only completed H1 bars (never the forming candle), requires several of its enabled strategies to agree, and sizes the position from the stop distance rather than a fixed lot — so a wider stop always means a smaller position, and the money at risk stays constant. Every configuration passed the same acceptance procedure on real-tick data before it shipped: statistical significance over its own break-even line, a minimum number of losing trades to actually measure it, and stops that were genuinely reached rather than just theorized.

Try it before you take my word for it

The demo runs in full inside the Strategy Tester — same presets, same logic, no time limit. Turn on the validated instruments, select "Every tick based on real ticks," and look at the trade list yourself: the stops, the position sizing, the risk ceilings holding across instruments. I'd rather you find out in the tester, for free, than after committing real money.

Link to the product page: https://www.mql5.com/en/market/product/191885
Cristian David Castillo Arrieta 출시돈 제품

Live Verified Signal: AbacuQuant on Darwinex-Live 개발자 실계좌: 2026년 8월 24일부터 AbacuQuant Portfolio를 운용 중입니다. 본 포트폴리오는 실제 시장 체결력을 검증하기 위해 2026년 10월 3일까지 거래당 2.0% 리스크 (기본값의 4배)로 공격적인 실전 스트레스 테스트를 거쳤으며, 이후 기본 기관 설정인 0.5% 리스크 로 전환하여 운용되고 있습니다. 이 시그널의 이전 월 기록은 과거 다중 EA 아키텍처 시절의 기록입니다. 모든 통계는 MQL5에서 독립적으로 검증되었으며 모든 거래 기록을 포함합니다. AbacuQuant Portfolio 는 MetaTrader 5를 위한 기관급 다중 통화 및 다중 자산 엑스퍼트 어드바이저(EA) 입니다. 양적 포트폴리오 다각화, 프랍 펌(Prop Firm) 드로다운 제어, 자동화된 알고리즘 트레이딩을 위해 설계되었으며, 단 하나의 H1 차트에서 최대 11개의 검증된 시장 을