
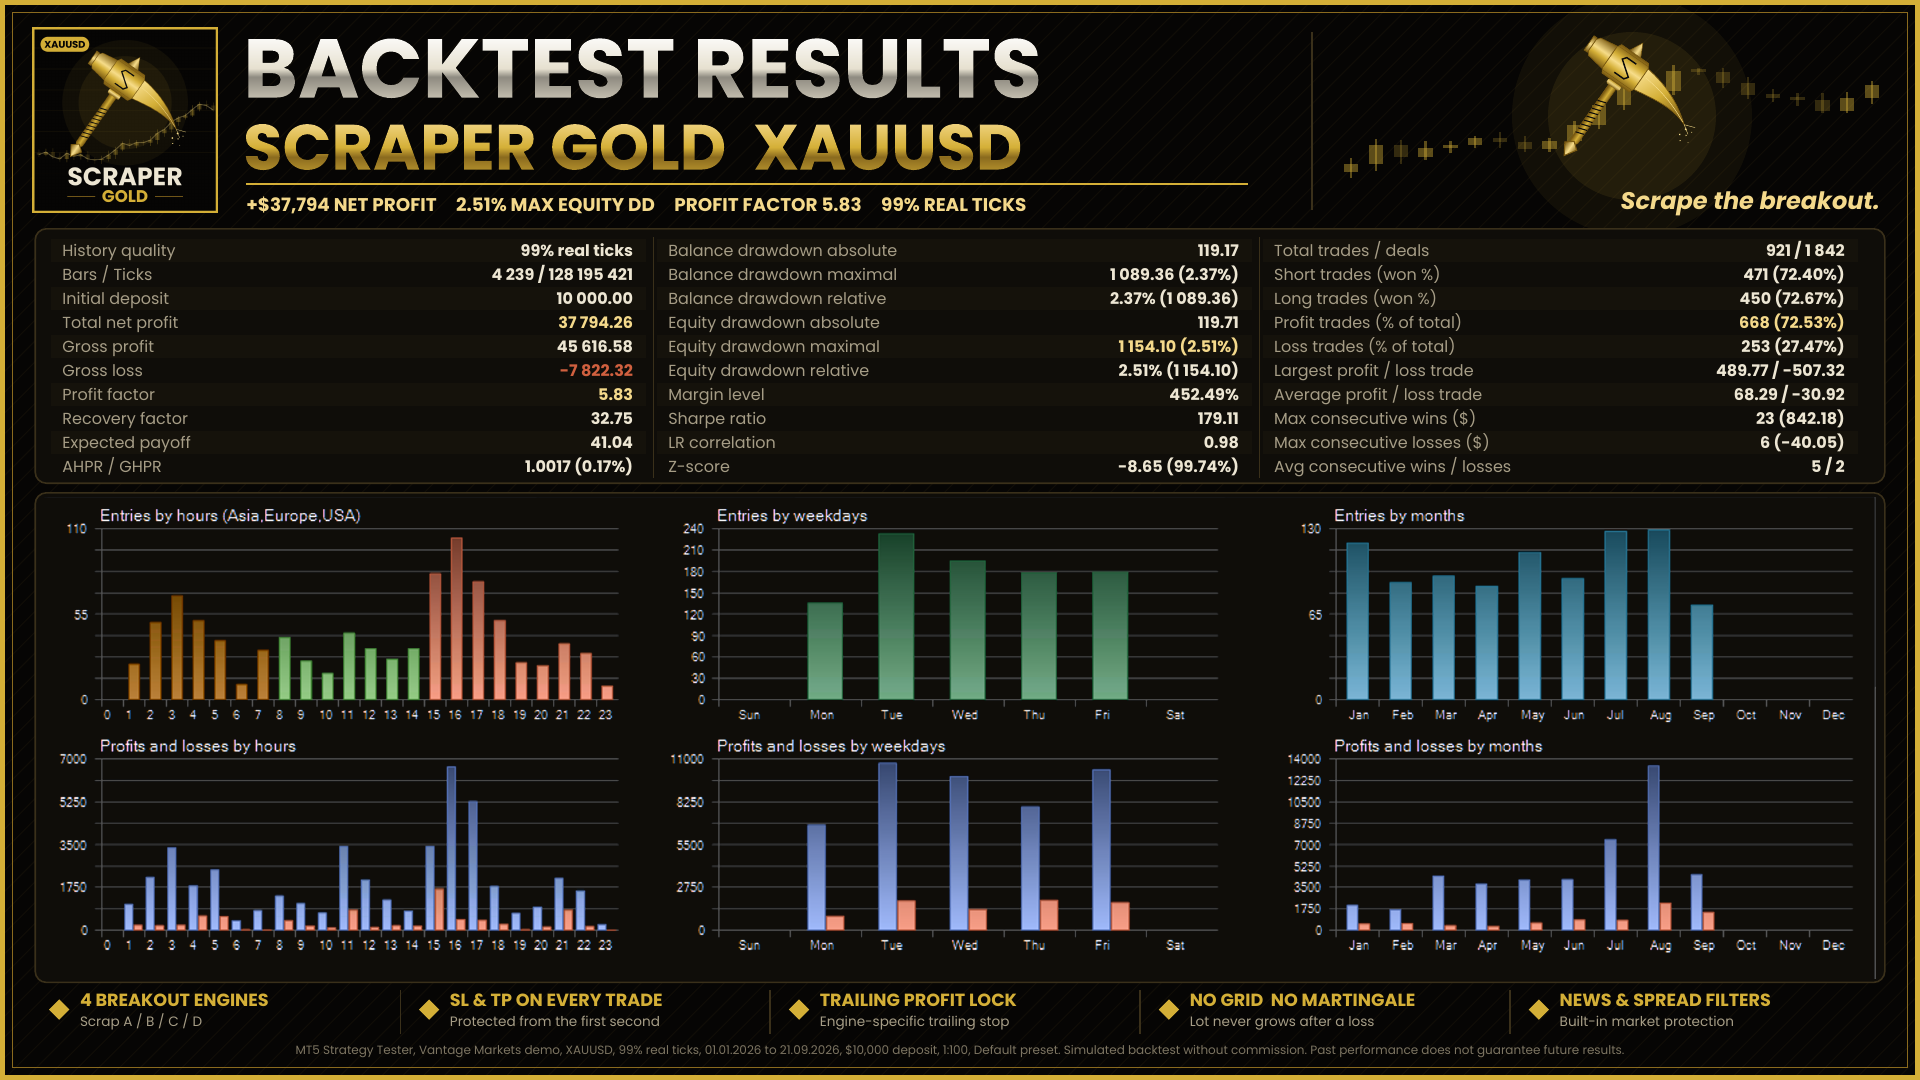
ScraperGold was tested in the MetaTrader 5 Strategy Tester on XAUUSD with real tick data. Here are the full results, including the numbers that are less flattering.
Test conditions
• Period: 1 January – 21 September 2026
• Data: Vantage Markets demo server, 99% history quality, every tick based on real ticks
• Deposit: $10,000 · Leverage 1:100
• Settings: Default preset (0.01 lot per $1,000 balance per engine), all 4 engines active
• Commission: not applied
Results
• Net profit: $37,794.26 (+377.9%)
• Final balance: $47,794
• Profit factor: 5.83
• Recovery factor: 32.75
• Maximum equity drawdown: $1,154.10 (2.51%)
• Total trades: 921 (668 wins, 72.53%)
• Long trades: 450 (72.67% won) · Short trades: 471 (72.40% won)
• Average win / average loss: $68.29 / −$30.92
• Longest losing streak: 6 trades (−$40.05)
Tested on a second broker's data
A trader independently tested ScraperGold on Hantec Markets data (standard XAUUSD, same period, real ticks) with a $100,000 deposit, leverage 1:50 and the lower-risk preset (0.01 lot per $2,000). Result: +$99,781 (+99.8%), maximum equity drawdown 1.65%, profit factor 4.40, 925 trades. Similar behaviour on different broker data is a good sign that the results are not tied to one data feed.
What this backtest does NOT show
• Commission: not included. Many ECN/raw accounts charge commission per lot.
• Slippage and spread spikes: live fills are never as clean as a backtest.
• Execution speed: the average trade lasts under a minute, so a fast VPS and a low-spread broker matter.
• Other periods: both tests cover 2026 only.
Live results will be lower than this. That's why I run a public live account and post results every day, wins and losses. Judge ScraperGold by the live numbers, not only by the backtest.
Live account: https://www.mql5.com/en/signals/2392705
Product page (free demo for the Strategy Tester): https://www.mql5.com/en/market/product/197663