Gold Night Drift
- Эксперты
-
Donizeti Aparecido Alves Ferreira Junior
 Software developer and founder of D7 Bots, building algorithmic trading tools for MetaTrader 5.
- Версия: 2.2
- Активации: 5
A timed overnight XAUUSD hold — not a scalper.
GoldNightDrift is an MT5 Expert Advisor built around one specific clock-based idea: enter long in the New York afternoon and carry the position toward the next New York morning. It uses internal XAUUSD M30 data, ATR-based protection and risk-sized volume.
Who it is for
For traders who prefer a simple overnight timing rule with many historical observations, rather than indicator stacking or intraday scalping. The audited default is long-only and trades Monday through Thursday.
How it works
- At 13:30 New York, evaluate the first new XAUUSD M30 bar.
- Enter long only on Monday through Thursday when execution guards pass.
- Protect with an 8.0 ATR stop and 1.0R target.
- Exit at the first valid target tick at or after 08:30 New York next day.
Historical Strategy Tester evidence
The historical reference is MetaTrader 5 Strategy Tester simulation on MetaQuotes-Demo, model 1, virtual USD 10,000 and 1.00% risk. Only the frozen scientific reference is used for the figures below.
| Window | Period | Net result | Trades | Profit factor | Max balance DD |
|---|---|---|---|---|---|
| In-sample | 2020-01-01 to 2024-12-31 | USD +2,653.26 | 1012 | 1.25 | 7.03% |
| Out-of-sample | 2025-01-01 to 2026-10-03 | USD +856.76 | 238 | 1.28 | 5.54% |
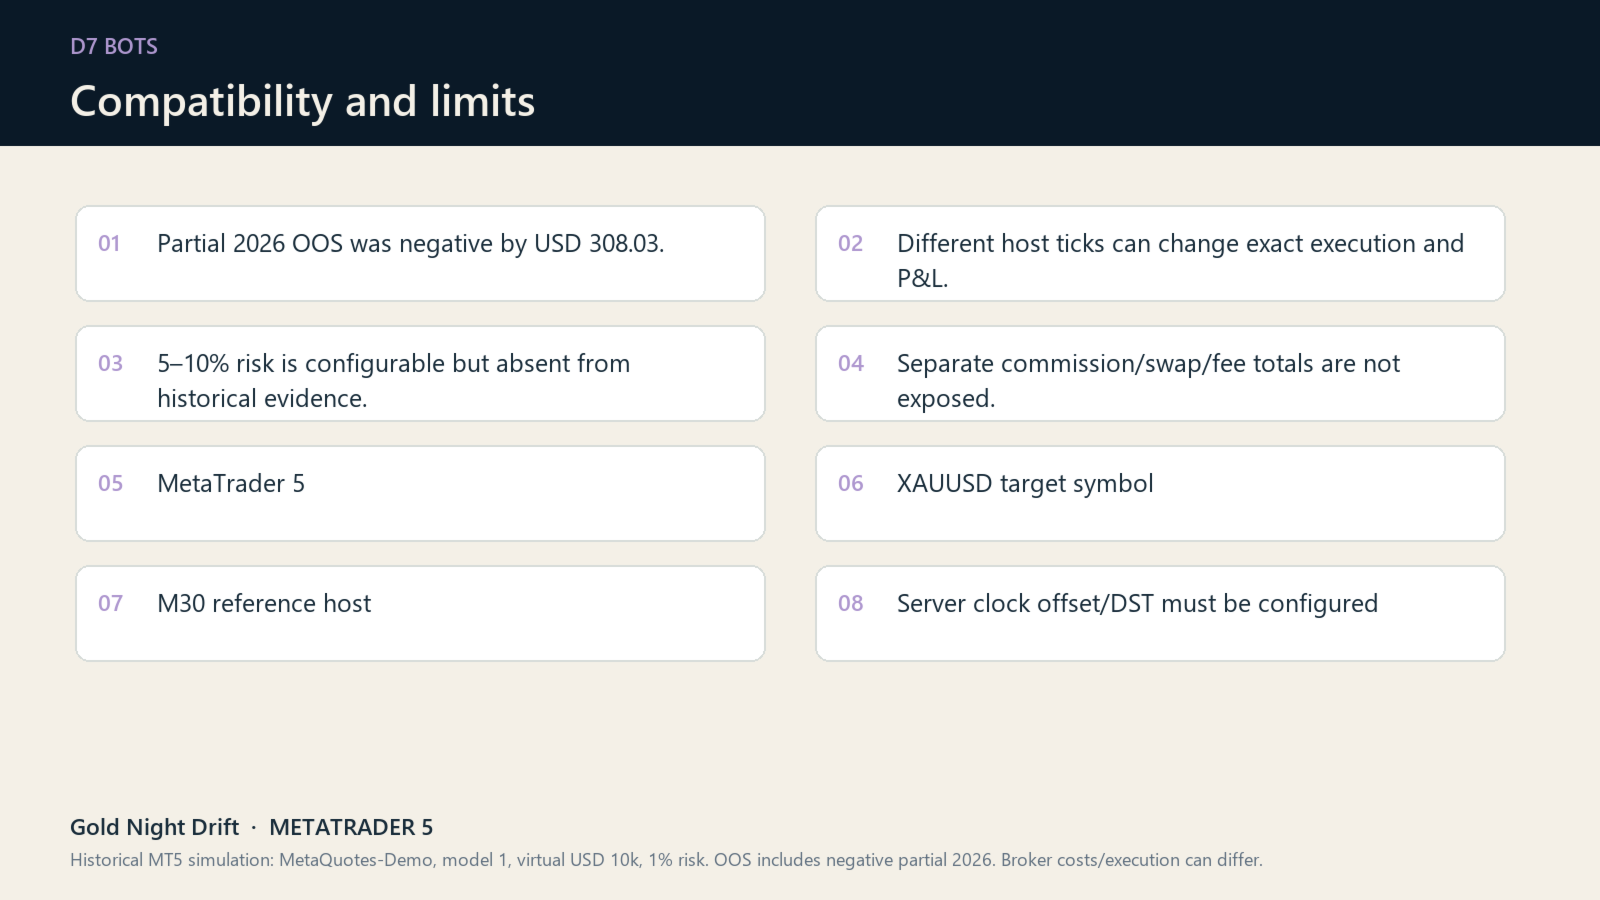
IS included a negative 2021 at USD -317.97. OOS was USD +1,164.79 in 2025 and USD -308.03 in partial 2026 through October 3. The negative partial 2026 result is part of the evidence.
The history used 1.00% risk. The interface accepts values through 10.00%, including 5–10%, but those risk levels were not measured in the displayed history and can magnify drawdown, losses and margin use.
Costs and execution limits
The reconciled frozen metrics do not expose separate commission, swap and fee totals. Net results are reported as retained. XAUUSD spread, swap, contract size, tick value, session hours, margin and minimum volume can differ by broker.
The reference curves belong to the XAUUSD M30 scientific host. A different host can trigger checks at different instants, so identical execution or P&L is not promised. Later diagnostic replays with timing/swap differences are excluded from these marketing figures.
Essential setup
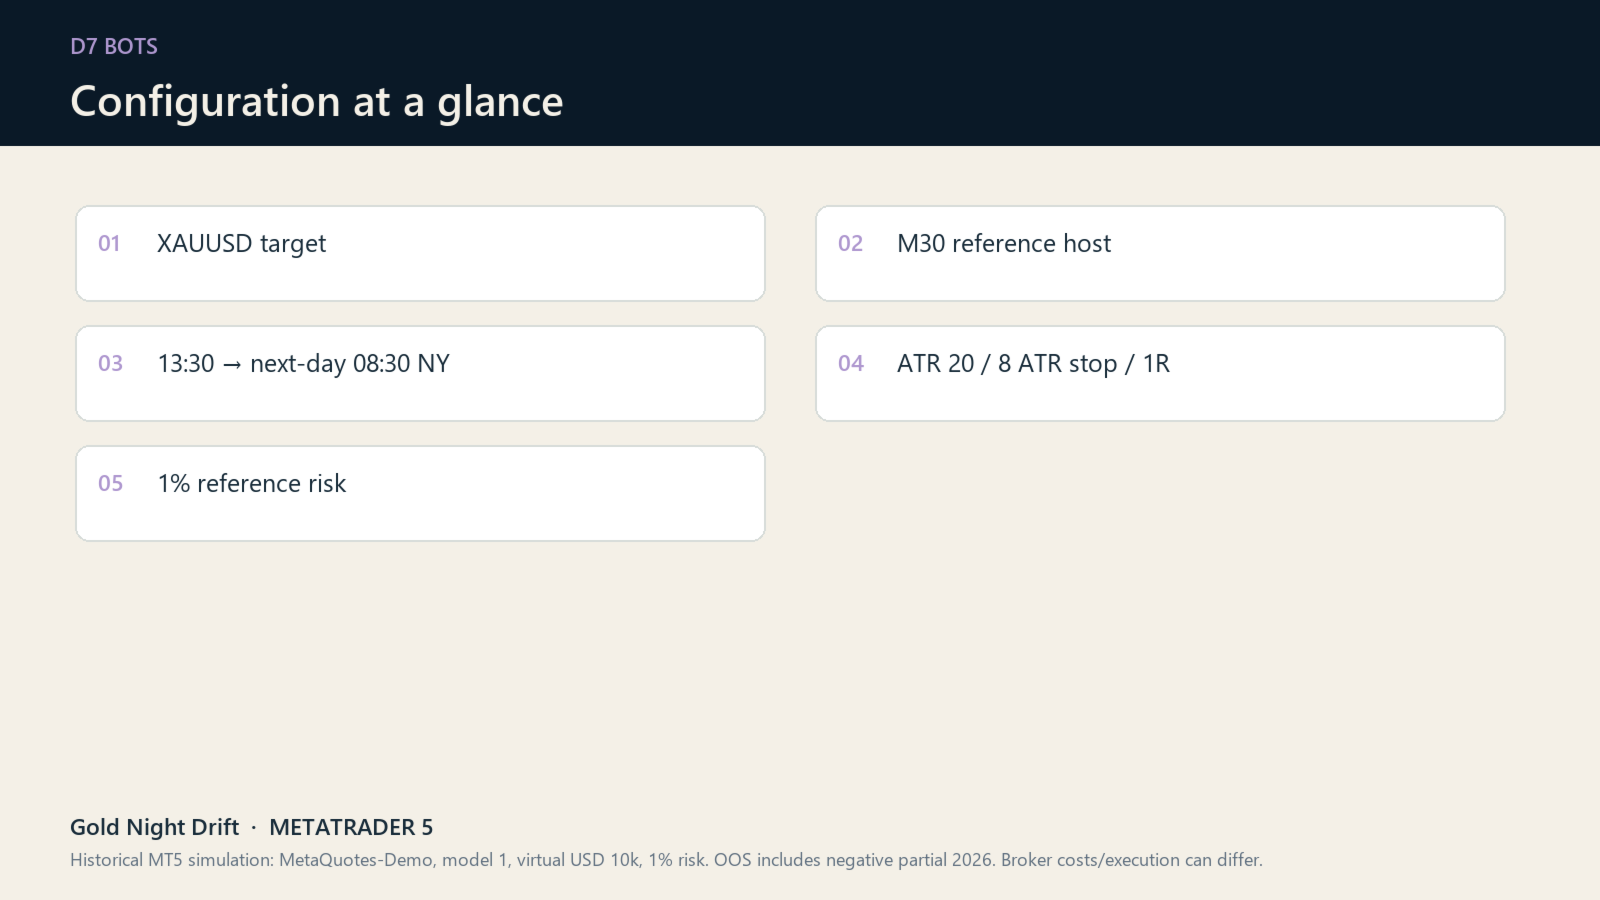
- Target: XAUUSD; reference host: M30.
- Entry: 13:30 New York, Monday–Thursday.
- Exit: first valid tick at/after 08:30 New York next day.
- ATR(20), 8.0 ATR stop, 1.0R target, 0.10 ATR spread guard.
- Server winter offset +2 with European DST in the audited reference.
FAQ
Is this a scalper?
No. The core idea is an overnight hold from New York afternoon toward the next morning.
Does it trade short?
No. The audited default is long-only.
What happened in 2026?
The partial OOS period through October 3, 2026 was negative by USD 308.03, while the full OOS aggregate remained positive.
Is 5–10% risk part of the backtest?
No. The interface accepts those values, but the displayed history used 1.00% risk.
Will another host chart reproduce the same P&L?
Not necessarily. The strategy still reads XAUUSD M30, but callback timing can change exact execution.
Before renting
Use the Market demo and Strategy Tester with your broker first. Check the exact symbol, spread, contract specification, sessions and order sizing before starting the one-month rental.
Historical simulation is not a guarantee of future results.