Gold Night Drift
- Experts
-
Donizeti Aparecido Alves Ferreira Junior
 Software developer and founder of D7 Bots, building algorithmic trading tools for MetaTrader 5.
- 버전: 2.2
- 활성화: 5
GoldNightDrift is an MT5 Expert Advisor whose audited configuration trades XAUUSD on an internal M30 decision timeframe. It is a LONG-only overnight timing strategy in the audited default. It does not use a price trend, oscillator, breakout or external signal: it enters during the New York afternoon and carries the position toward the next New York morning, aiming to capture an overnight inventory/liquidity drift in gold.
Version 2.02 has its own configurable trading symbol, InpTradeSymbol , with default XAUUSD. The host chart supplies terminal callbacks only; the strategy's series, ATR, quotes, symbol specifications, position checks, sizing and orders use the configured target symbol on M30 internally. Broker prefixes or suffixes can therefore be supplied in the target-symbol input without replacing XAUUSD with the host market.
Trading logic
- Target instrument: XAUUSD by default, exact broker symbol configurable through InpTradeSymbol .
- Economic timeframe: M30 internally, independent of host-chart timeframe.
- Direction: BUY only in the audited default.
- Entry: first new target M30 bar opening at 13:30 New York, Monday through Thursday.
- Friday entries are excluded to avoid mixing the overnight effect with weekend exposure.
- Primary economic exit: first valid target tick at or after 08:30 New York on the next civil day.
- ATR: 20 periods, read from the last completed target M30 bar.
- Default emergency stop: 8.0 × ATR(20) below entry.
- Default protective target: 1.0R above entry using the executable stop distance. The time exit remains the economic horizon.
- Spread guard: current target spread must be no more than 0.10 × completed ATR(20).
- Default trailing, breakeven and generic elapsed-time exit are disabled.
- The default direction mirror is disabled.
- Position size is calculated from current equity and executable stop distance with OrderCalcProfit , rounded down to the target symbol's volume step, and reduced if needed for margin.
- InpRiskPercent remains 1.00% by default. The interface accepts finite positive values through 10.00%, including 5–10%. All historical evidence below used 1.00%; higher risk is not represented by those results and can materially increase losses and drawdown.
There is no external holiday calendar. The EA requires synchronized target data, an open target trading session and a target quote belonging to the current target M30 bar. A quote timestamped after current server/tester time is rejected. No host-symbol or alternate-market fallback is used.
Historical Strategy Tester evidence
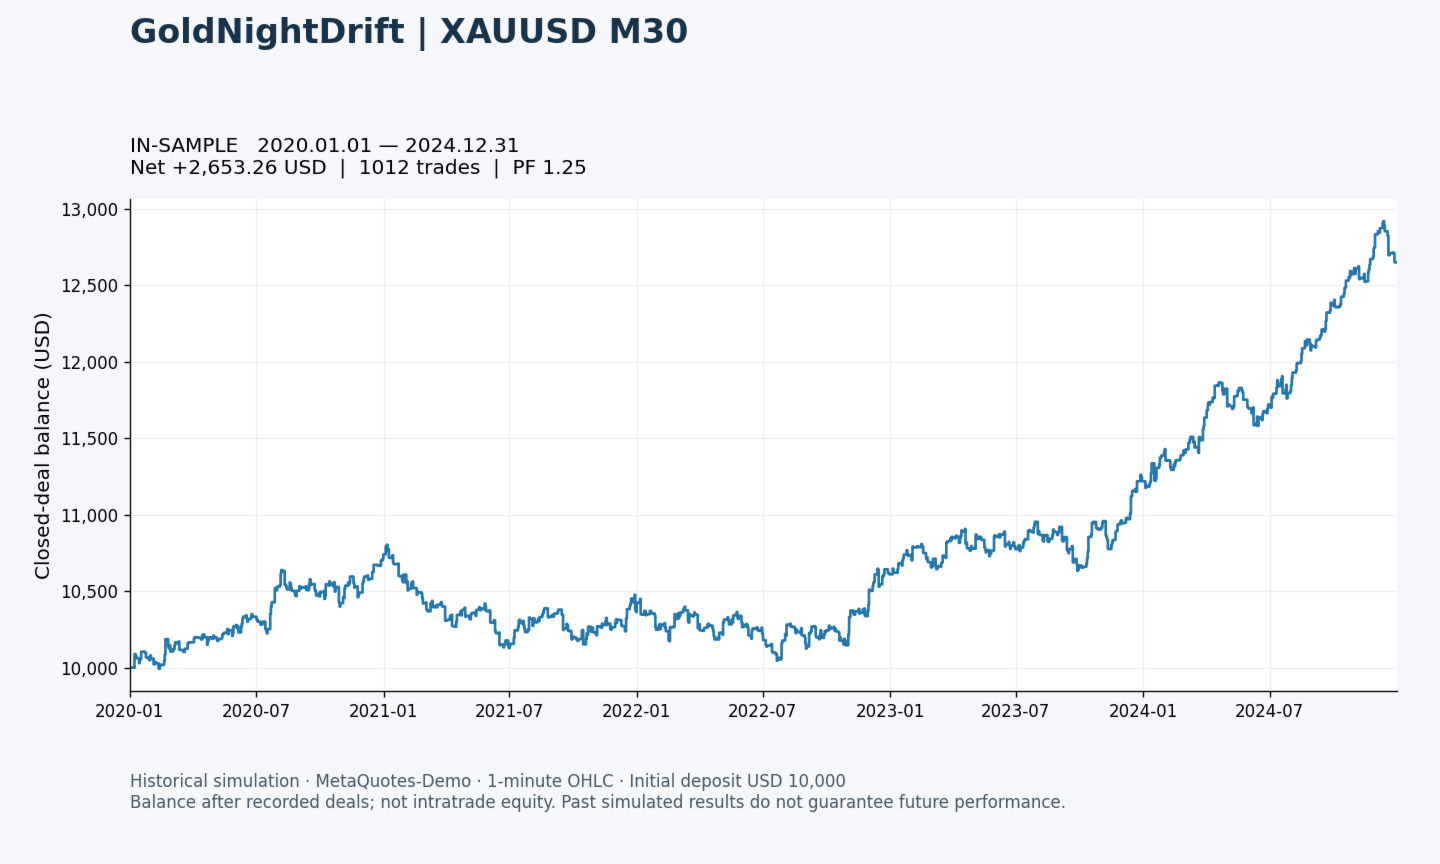
These figures are MetaTrader 5 Strategy Tester backtests, not live trading results. The audited commercial runs used MetaQuotes-Demo, model 1, virtual initial deposit USD 10,000, and the same frozen scientific configuration.
In-sample: 2020-01-01 to 2024-12-31
- Net profit: USD +2,653.26
- Trades: 1,012
- Profit factor: 1.25
- Maximum balance drawdown: 7.03%
- Observed frequency: 16.627 trades per 30 days
Annual net inside the IS window was not uniformly positive:
- 2020: USD +741.11
- 2021: USD -317.97
- 2022: USD +187.14
- 2023: USD +609.03
- 2024: USD +1,433.95
Out-of-sample: 2025-01-01 to 2026-10-03
- Net profit: USD +856.76
- Trades: 238
- Profit factor: 1.28
- Maximum balance drawdown: 5.54%
- Observed frequency: 11.156 trades per 30 days
The OOS aggregate was positive, but the later years differed:
- 2025: USD +1,164.79
- 2026 through October 3: USD -308.03
Profit factor, drawdown, WFA, Monte Carlo, stress and other historical research diagnostics remain report-only evidence; they are not additional promises or guarantees.
Time, broker and execution limits
The strategy converts server time to UTC and then New York time, including U.S. and European daylight-saving rules. The audited default uses server winter offset UTC+2 with European DST enabled. A broker with a different server-clock convention needs verification before use.
The EA checks the configured XAUUSD trading sessions and waits when that market is closed. Target data must be synchronized; target quotes must be current enough for the active M30 bar and must not come from the future relative to server/tester time.
The evidence is MetaQuotes-Demo / model 1. It is not Vantage evidence, real-tick validation or live profit. The reconciled metrics do not expose separate commission/swap/fee totals. XAUUSD contract size, tick value, spread, stops level, minimum volume, margin, sessions and symbol naming vary by broker and can materially change execution.
GoldNightDrift uses no DLL, WebRequest, Telegram, external signal service or external runtime data feed. Version 2.02 adds no artificial trades, no fallback market and no validator-specific trading branch.
Host-chart timing can change exact execution. In the recorded IS technical comparison, the XAUUSD M30 reference host produced 1,012 trades and USD +2,653.26, while an EURUSD host produced 1,011 trades and USD +2,525.84. These different totals are not host parity. The historical curves and statistics on this page belong to the scientific XAUUSD M30 host; use XAUUSD M30 as the host chart when reproducing the reference test.
Version 2.02 has been compiled and technically tested. Risk settings from 5% to 10% are accepted by the interface but are not represented by the 1.00% historical evidence.
Historical simulation does not guarantee future results.