• 정보
2 년도
경험
4
제품
102
데모 버전
0
작업
1
거래 신호
0
구독자
재무 및 국제 비즈니스 전문가로 재무 관리를 전공했습니다. MQL5와 Python 독학 개발자로서 알고리즘 트레이딩, 멀티에셋 포트폴리오 구축, 정량적 리스크 관리에 집중하고 있습니다.

저의 작업은 개별 전략이 아닌 조율된 포트폴리오로 작동하는 Expert Advisor의 설계, 최적화 및 검증에 중점을 두고 있습니다. 상관관계 분석, 시간대 커버리지 매핑, 자산군 분산화를 적용하여 단일 상품이나 단일 접근 방식에 의존하지 않는 시스템을 구축합니다.

현재 외환, 지수, 귀금속, 에너지, 미국 주식을 아우르는 알고리즘 포트폴리오를 관리하고 있으며, 여러 세션과 타임프레임에서 동시에 운용하고 있습니다.
이 커뮤니티에서 기술 기사와 오픈소스 도구를 통해 제 경험을 공유하고 있습니다. "개별 EA 구축"에서 "포트폴리오 엔지니어링"으로의 전환이야말로 개인 투자자의 사고와 기관 투자자의 사고를 구분짓는 경계선이라 확신하며, 이 원칙이 제가 이곳에서 발행하는 모든 것의 지침이 됩니다.Has usado 75% de tu límit
Cristian David Castillo Arrieta
게재된 기고글 Building a Hidden Risk of Ruin Auditor in MQL5
Building a Hidden Risk of Ruin Auditor in MQL5

Aggregate metrics alone do not reveal how a trade sequence manages risk. This MQL5 tool analyzes closed positions to flag four structural patterns: post-loss volume escalation, overlapping same-direction entries, asymmetric payoffs, and a classical risk-of-ruin figure. The results are merged into a configurable A-F grade with concise recommendations to guide further review.

Cristian David Castillo Arrieta
게재된 코드 Scale Out Value Analyzer
A native MQL5 tool that reconstructs closed positions from deal-level history, flags the ones closed through more than one exit, and reprices each one at its own first, last, and best exit rates to measure whether scaling out actually added value. Reports a Value-Add Ratio, a Scale Out Win Rate, an Efficiency figure, and a single-trade dependence check, combined into an A+ to F score with recommendations. Runs out of the box against a built-in demonstration data set; a companion script exports the real input file from your own account history. Pure MQL5, no external libraries.
Cristian David Castillo Arrieta
게재된 코드 Hidden Risk of Ruin Auditor
청산된 포지션의 거래 내역(CSV 파일 또는 동반 스크립트인 RuinExport.mq5가 현재 계좌의 거래 내역에서 자동으로 생성한 파일)을 읽어들이고, 다음 네 가지 독립적인 위험 지표를 보고합니다: 손실 발생 후 거래량 증가, 평균 가격이 더 나빠지는 중복된 동일 방향 포지션, 수익과 손실 간의 수익 비대칭성, 그리고 거래당 지정된 위험 수준에 따른 고전적인 파산 위험 추정치입니다. 이 네 가지 점수는 하나의 A~F 등급으로 통합되며, 평이한 언어로 된 권장 사항이 함께 제공됩니다. CSV 파일이 발견되지 않으면 스크립트가 재현 가능한 데모 거래 내역을 자동으로 생성하므로, 첫 실행 시에도 보고서를 확인할 수 있습니다.
Cristian David Castillo Arrieta
게재된 기고글 Execution Cost and Slippage Sensitivity Analyzer
Execution Cost and Slippage Sensitivity Analyzer

Backtests often understate spread, commission, and slippage. This MQL5 analyzer loads closing deals and simulates rising execution costs to measure robustness. It computes the breakeven cost per deal, the cushion over an assumed cost, the net profit and profit factor at that cost, and how many winners turn into losers, then summarizes the result with an A+ to F grade and targeted guidance.

Cristian David Castillo Arrieta
게재된 기고글 Creating a Profit Concentration Analyzer in MQL5
Creating a Profit Concentration Analyzer in MQL5

Net profit and win rate tell you how much a strategy made, not how the result is distributed. This article builds a native MQL5 script that reads your closed trades and measures profit concentration: the top-N trade share, the Gini coefficient of the winners, an outlier-dependence stress test that removes the best few winners, and the largest day against a prop-firm consistency limit. It combines these into one A+ to F score with recommendations, running inside MetaTrader 5.

Cristian David Castillo Arrieta
게재된 코드 Portfolio Correlation and Margin Risk Calculator
임의의 상품 세트와 해당 상품들을 모두 동시에 보유하기 위해 계좌에 필요한 총 마진 간의 과거 피어슨 상관계수를, 순자산 대비 백분율로 계산합니다. 외부 라이브러리, Python, AI 없이 MetaTrader 5에서 네이티브로 실행됩니다. 심볼 목록과 랏 크기를 입력값으로 설정하면 ‘전문가’ 탭과 차트에 전체 행렬이 표시되며, 타이머에 따라 자동으로 갱신됩니다.
Cristian David Castillo Arrieta
Why the same trailing stop breaks the moment Gold changes character

I was in a forum thread today about trailing stops on XAUUSD, and it made me put into words something I've been building my whole approach around for a while: almost every trailing method traders compare — EMA cross, Chandelier, ATR multiples, swing-structure trails — gets judged on a single backtest run over one continuous chunk of history. The "best" multiplier or ladder step that wins that test isn't actually the best method. It's the method that happened to fit whatever mix of trend and chop was sitting in that sample.

The fix I use is simple to describe and annoying to implement properly: split the history into volatility regimes first (I use ATR percentile over a rolling window, expansion vs. compression), then optimize and validate each piece of logic separately per regime instead of once over the whole dataset. A structural trail wins clearly in expansion. In compression it just gets chopped up by noise, and something tighter does better there. Neither method is "the winner" — the regime decides which one applies.

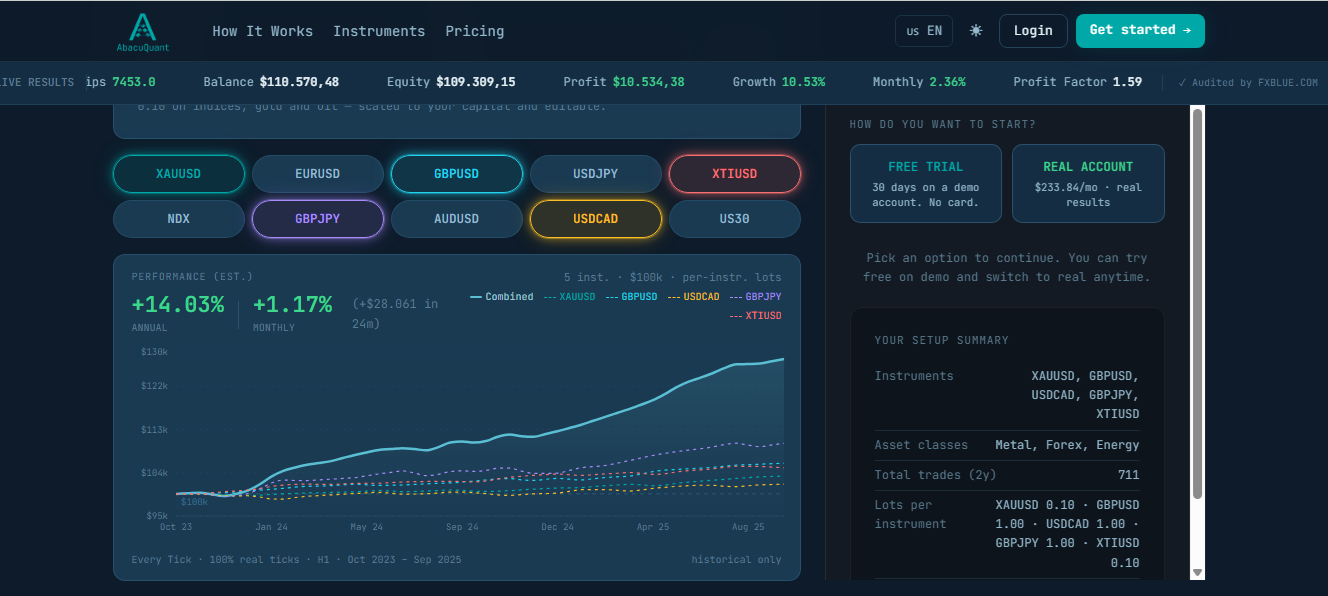
That's the same principle I ended up building AbacuQuant around, just scaled up from one exit rule to an entire portfolio. Instead of one strategy tuned to look good on one backtest, the logic behind each strategy is walk-forward tested and optimized (genetic optimization, not a single curve-fit) across different market regimes and asset classes, forex, metals, indices, energy, ETFs, individual stocks — and then combined into a portfolio specifically to keep cross-asset correlation low (the current version sits under 0.4 correlation across most pairs in the book). The idea isn't "find the one strategy that beats the market." It's "find enough structurally different, regime-validated pieces that the portfolio doesn't fall apart when one regime ends," which is exactly the failure mode people are describing in that XAUUSD thread, just at the position level instead of the portfolio level.

It also runs entirely inside your own MetaTrader account nothing custodial, your funds never move to a third party and the newer version adds the drawdown/consistency rules prop firms check for, since that's become how a lot of people are actually trading it live.

If any of this is useful for how you're thinking about your own trailing logic or portfolio construction, happy to go deeper in the comments. And if you want to see what the regime-validated approach looks like applied across a full portfolio rather than one exit rule, it's at abacuquant.com.

Cristian David Castillo Arrieta
Build your own portfolio and connect it to your demo (free) or live account.

www.abacuquant.com
Cristian David Castillo Arrieta
게재된 코드 Execution Cost Sensitivity Analyzer
전략의 우위가 실행 비용에 대해 얼마나 견고한지를 측정하는 순수 MQL5 스크립트입니다. 이 스크립트는 청산된 거래에 대한 날짜(Date), 수익(Profit), 거래량(Volume)이 포함된 CSV 파일을 읽어들이고, 각 거래의 비용을 고정 부분과 랏당 비용 부분으로 모델링합니다. 이 스크립트는 거래당 손익분기점 비용, 쿠션(순이익이 0이 되는 가정된 현실적 비용의 배수), 가정된 비용으로 재계산된 순이익 및 수익 계수, 비용이 손실로 전환되는 수익 거래의 비율, 그리고 권장 사항이 포함된 A+부터 F까지의 종합 비용 견고성 점수를 출력합니다. 파일이 없는 경우 재현 가능한 샘플을 생성하여 분석하므로, 첫 실행 시 바로 결과를 확인할 수 있습니다. 외부 라이브러리, 파이썬, AI를 전혀 사용하지 않습니다.
Cristian David Castillo Arrieta
게재된 기고글 Beyond Maximum Drawdown: Building a Drawdown DNA Analyzer in MQL5
Beyond Maximum Drawdown: Building a Drawdown DNA Analyzer in MQL5

Maximum drawdown is one number that hides what really matters: how often an equity curve declines, how long it stays below a previous peak, and how quickly it recovers. This article builds a native MQL5 tool that reconstructs the underwater curve, breaks it into individual drawdown episodes (depth, duration, recovery time), computes the Ulcer Index, Pain Index, and Recovery Factor, and combines them into a single resilience grade with practical recommendations. No external libraries, no Python, no AI.

Cristian David Castillo Arrieta
게재된 코드 Profit Concentration Analyzer
전략의 수익이 얼마나 집중되어 있는지, 즉 수익 우위가 폭넓게 분포되어 있는지 아니면 소수의 운 좋은 거래에 의존하고 있는지를 측정하는 네이티브 MQL5 스크립트입니다. 이 스크립트는 거래별 CSV 파일(날짜, 수익)을 읽어와 최대 규모 거래에서 발생한 순이익의 비중, 승리 거래의 지니 계수, 집중도 프로필, 최상위 몇 건의 거래를 제외하고 순이익 및 수익 계수를 재계산하는 생존 테스트, 그리고 설정 가능한 일관성 한도 대비 최대 일일 수익 등을 분석하여, 이를 집중도 및 일관성 점수(A+ ~ F)로 통합하고 권장 사항을 제공합니다. 파일이 발견되지 않으면 샘플 세트를 생성하므로 설치 후 바로 실행할 수 있습니다. 외부 라이브러리, 파이썬, AI가 필요하지 않습니다. 보조 프로그램인 ExportTrades.mq5는 사용자의 거래 내역에서 파일을 생성합니다.
Cristian David Castillo Arrieta
게재된 코드 Drawdown DNA Analyzer
단순히 “최대 드로다운” 수치뿐만 아니라 계좌의 드로다운 구조를 분석하는 네이티브 MQL5 스크립트입니다. 이 스크립트는 일일 자산 곡선(Date,DailyPnL CSV)을 읽어와 손실 구간 곡선을 재구성한 후, 이를 개별 드로다운 에피소드로 나누어 각 에피소드의 깊이, 지속 기간 및 회복 시간을 산출합니다. 그런 다음 ‘울서 지수(Ulcer Index)’, ‘페인 지수(Pain Index)’, ‘회복 계수(Recovery Factor)’ 및 마이너스 상태 지속 시간을 보고하고, 이를 하나의 회복력 점수(A+ ~ F)로 통합하여 권장 사항과 함께 ‘전문가(Experts)’ 탭에 표시합니다. 외부 라이브러리가 필요하지 않으며, 파일이 발견되지 않을 경우 샘플 곡선을 생성하므로 설치 후 바로 실행할 수 있습니다.
Cristian David Castillo Arrieta
Introduction: The Context-Blind Expert Advisor Problem A carefully optimized Expert Advisor completes six months of profitable forward testing. The equity curve is smooth, the drawdown is bounded, and the trade distribution looks healthy. On the first Friday of the seventh month, the EA opens a 0...
Cristian David Castillo Arrieta
This is the most power full EA
Cristian David Castillo Arrieta
게재된 기고글 Building a Correlation-Aware Multi-EA Portfolio Scorer in MQL5
Building a Correlation-Aware Multi-EA Portfolio Scorer in MQL5

Most algo traders optimize Expert Advisors individually but never measure how they behave together on a single account. Correlated strategies amplify drawdowns instead of reducing them, and coverage gaps leave portfolios blind during entire trading sessions. This article builds a complete portfolio scorer in MQL5 that reads daily P&L from backtest CSV files, computes a full Pearson correlation matrix, maps trading activity by hour and weekday, evaluates asset class diversity, and outputs a composite grade from A+ to F. All source code is included; no external libraries are required.

1
Cristian David Castillo Arrieta 출시돈 제품

ABQ Portfolio Correlation Scorer: Inteligencia Artificial de Grado Institucional para la Gestión de Riesgo La mayoría de los traders no fracasan por una mala estrategia de entrada, sino por una falla invisible en la arquitectura de su portafolio . El error más común es la sobreexposición por correlación: abrir múltiples posiciones pensando que se está diversificando, cuando en realidad se está multiplicando el riesgo sobre un mismo factor. ABQ Portfolio Correlation Scorer es un Copiloto de

Cristian David Castillo Arrieta
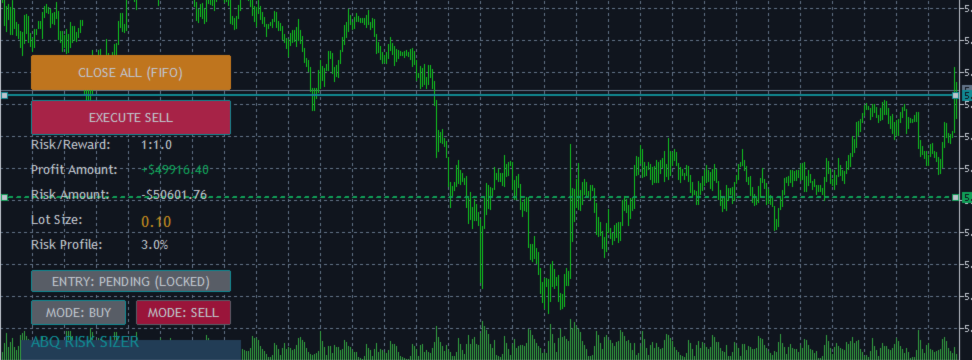
ABQ Visual Risk Sizer - Official User Manual Author: Cristian Castillo | AbacuQuant Version: 1.60 Platform: MetaTrader 5 (MT5...
Cristian David Castillo Arrieta 출시돈 제품

ABQ Visual Risk Sizer - Institutional Risk & Trade Execution 카테고리: 유틸리티 / 리스크 관리 수동 로트 계산은 시간과 비용을 낭비하게 합니다. 현대 트레이딩, 특히 프랍 펌(Prop Firms) 계좌를 운영할 때 로트 계산 오류나 단 5초의 주문 지연은 일일 드로다운(Daily Drawdown) 규정 위반으로 이어지거나 최적의 진입 가격을 놓치는 원인이 됩니다. ABQ Visual Risk Sizer 는 이 문제를 완벽하게 해결하기 위해 설계된 기관급 도구입니다. 복잡한 리스크 수학 계산을 MetaTrader 5 차트 위에서 직접적이고 빠르며 100% 정확한 시각적 경험으로 변화시킵니다. 이제 외부 계산기나 엑셀 시트는 잊으십시오. 차트 위의 라인을 드래그하고 클릭 한 번으로 거래를 실행하기만 하면 됩니다. 왜 ABQ Visual Risk Sizer가 필요한가요? 프랍 펌을 위한 완벽한 보호: 모든 거래에서 사용자가 설정한