Why I rejected 22 of the 39 markets I tested for an MT5 portfolio EA

Most Expert Advisor pages show you the markets that worked. This post is about the ones that didn't.
For Abacuquant Portfolio I researched 39 markets. Twenty-two were rejected. Eleven made it into the product, and six more are still waiting for validation. The rejections are the most useful part of the work, because they show what the acceptance procedure actually does. A process that turns down most of what it tests is not built to produce an attractive backtest. It is built to keep out what does not hold up.
Here is the procedure, step by step, with the markets it stopped.
1. Does the ranking predict anything?
For each market, a genetic optimization searched roughly 100,000 to 340,000 parameter sets on H1. January 2020 to May 2024 was used for selection, and May 2024 to August 2026 as a second period.
Before building anything, I asked one question: if I rank configurations by their results in the first period, does that ranking predict their results in the second? If it does not (ratio below 1, or rank correlation below +0.10), the market is rejected, however good its best results look.
Ten individual US stocks were rejected here, including Apple, Microsoft, Visa and Coca-Cola. In several of them the ranking pointed the wrong way: the configurations that looked best early did worse later. If the past ranking has no predictive value, picking the "best" configuration is picking noise.
2. A filter on the geometry of the trade
A very distant stop with a very close target can produce a smooth equity curve simply because the stop was rarely reached inside the test window. So configurations whose break-even win rate is above 80% were excluded (85% for gold and AUDUSD). This removes many of the prettiest curves, on purpose.
3. The real-tick test, with three conditions
Each surviving preset was tested alone with "Every tick based on real ticks". To be accepted, it had to meet three conditions:
- At least 95% of losing trades close at their stop, so the stop was really tested.
- The win rate sits above the break-even level implied by its own stop and target, by a margin unlikely to be chance (t of 2 or more).
- The result rests on at least 40 observed losses. A record built on a handful of losses is not measured, it is guessed.
This is where the most instructive rejections happened:
- S&P 500 passed the statistical screening, then failed on real ticks: its win rate barely cleared its own break-even level (t = 0.53).
- Crude oil showed the strongest agreement between the two periods of any market in the research (rank correlation +0.60), and still failed the real-tick test. A good-looking history was not enough.
- DAX, CAC 40 and IBEX 35 failed too (t = 0.34, -0.85 and 0.16).
- AUDJPY missed the correlation threshold by 0.004. It was rejected anyway. The threshold is not adjusted to let a market in.
- GBPUSD passed its real-tick test with a wide margin, but on 18 losses, below the 40 required. It stays off until a rebuilt preset meets the standard.
4. The combined test
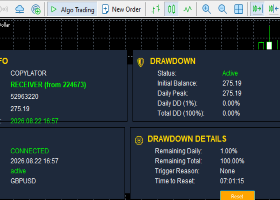
The eleven accepted presets were then run together on one account, at the default risk of 0.5% per trade, from May 2024 to July 2026 with real ticks: 3,849 trades, 79% closed in profit, profit factor 1.38, 24 of 27 months positive, deepest decline from an equity peak 6.3%, worst month -4.6%.
The trade-off is part of the design: the average loss was about 2.8 times the average win. Many small wins, fewer and larger losses. An earlier run at 2% per trade, four times the default, fell 22% from its equity peak.
What these numbers are not
They are Strategy Tester results on historical data, at one broker, with one clock setting. The second period was also used as a consistency requirement when choosing configurations, so its figures describe consistency rather than a blind test. The stronger checks are that one process was applied to 39 markets and rejected 22 of them, and that the same engine has been running on my own real-money account since August 2026.
Three questions you can ask of any backtest
Even if you never use my EA, these questions will save you money:
- Does ranking by past results predict later results, or is the "best" configuration just the luckiest one?
- Is the win rate above its own break-even level by a margin that is unlikely to be chance?
- How many losses is the result built on?
If a seller cannot answer them, the backtest is a picture, not evidence.
Disclosure: I am the author of Abacuquant Portfolio, the MetaTrader 5 Expert Advisor where this procedure is applied. You can test the free demo in your own Strategy Tester ("Every tick based on real ticks", with the deposit you actually intend to trade) before renting or buying: https://www.mql5.com/en/market/product/191885
Trading involves risk of loss. Backtest results are not live results.