MT5 Trade Copier: ECN vs. Standard Accounts for Copy Trading

Product link:
https://www.mql5.com/en/ market/product/191385
When configuring an MT5 Trade Copier, traders often focus on the Sender, Receiver settings, lot management, symbol mapping, and synchronization. However, another important factor is the type of trading account used by the Receiver.
ECN, Raw Spread, and Standard accounts can provide access to the same MetaTrader 5 platform while applying different pricing and commission structures. The account type can therefore influence the effective cost of every copied trade.
This is especially important when the Receiver is copying a strategy with frequent entries, small profit targets, or short holding periods. Even when every trade is copied correctly, differences in spread, commission, execution, contract specifications, and other broker conditions can cause the Receiver's results to differ from the Sender's.
1. Why the Receiver Account Matters in Copy Trading
A trade copier primarily replicates trading instructions. It does not make the Sender and Receiver brokers identical.
When a Sender opens a position, the Receiver may experience different:
- Bid and Ask prices.
- Spread.
- Commission.
- Slippage.
- Execution speed.
- Contract specifications.
- Margin requirements.
- Trading conditions.
Consequently, two accounts can receive the same trading signal but produce different net results.
A useful way to think about copy trading is:
Sender Strategy ↓ COPYLATOR Replication ↓ Receiver Broker Conditions ↓ Actual Receiver Result
The copier controls the replication process, while the Receiver broker controls the actual execution environment.
2. What Is a Standard Account?
A Standard account commonly incorporates the broker's markup into the quoted spread rather than charging a separate trading commission on every transaction.
For example, the displayed EUR/USD spread may include both the underlying market spread and the broker's pricing structure.
However, there is no universal Standard-account specification. Spreads, commissions, minimum deposits, execution models, and contract specifications vary between brokers.
Therefore, traders should evaluate the actual conditions offered by the specific Receiver broker instead of relying only on the account name.
3. What Is an ECN or Raw-Spread Account?
ECN-style or Raw Spread accounts commonly separate the market spread from the broker's commission.
The Receiver may therefore see a very small raw spread while paying a separate commission for the transaction.
For example:
Raw Spread:
0.2 pips

Commission:
Charged separately

Total trading cost:
Spread + Commission
The exact commission structure varies significantly between brokers. Some brokers charge per lot per side, others use different pricing models.
Therefore, the headline spread alone should never be used to determine the total cost.
4. Spread Is Only One Part of Trading Cost
One of the most common mistakes is comparing only the displayed spread.
A Standard account might have a wider spread but no separate commission, while an ECN-style account might have a very tight spread plus commission.
The relevant comparison is the total effective cost.
Effective Trading Cost = Spread Cost + Commission + Potential Execution Costs
Depending on the strategy, swap or financing costs may also become relevant when positions are held for longer periods.
5. Why the Difference Matters More for Scalping
Short-term strategies can be highly sensitive to transaction costs.
Suppose a strategy targets a relatively small price movement. A difference of even one pip in effective transaction cost can represent a significant percentage of the expected gross profit.
For example:
Gross target:       10 pips
Trading cost:        2 pips
Remaining before
other costs:         8 pips
This does not mean that a particular account type is automatically suitable or unsuitable. It means that the relationship between trading costs and the strategy's average target becomes important.
6. Swing and Position Strategies
Longer-duration strategies may be less sensitive to a small difference in entry spread when their average targets and holding periods are significantly larger.
However, that does not mean transaction costs are irrelevant.
For longer-held positions, traders may need to consider:
- Entry spread.
- Exit spread.
- Commission.
- Swap or financing.
- Slippage.
The correct account type therefore depends on the complete cost structure and the strategy's trading characteristics.
7. ECN Does Not Automatically Mean Better Execution
ECN-style accounts are often associated with raw spreads and fast execution, but the account label alone does not guarantee a particular execution quality.
Actual execution can depend on:
- Broker infrastructure.
- Liquidity providers.
- Server location.
- Network latency.
- Market liquidity.
- Order type.
- Market volatility.
A well-configured Standard account can have efficient execution, while an ECN-style account can still experience slippage during fast markets.
For copy trading, actual observed Receiver execution is more useful than assumptions based solely on the account name.
8. The Sender's Account Type Does Not Transfer to the Receiver
If the Sender uses an ECN-style account, the Receiver does not automatically receive the same spread or commission conditions.
Likewise, if the Sender uses a Standard account, the Receiver does not inherit the Sender's exact pricing structure.
The Receiver executes through its own broker and account.
For example:
Sender: ECN / Raw Spread Low spread + commission Receiver: Standard Wider spread + no separate commission
The trade can still be copied successfully, but the economic result may differ.
9. Receiver-Side Spread Is the Relevant Spread
When configuring a spread filter in COPYLATOR, the Receiver's actual trading conditions are particularly important.
Suppose the Sender normally trades with a very low spread. That does not guarantee that the Receiver will have the same spread at the moment the trade arrives.
The Receiver could experience:
- A wider spread.
- A temporary spread spike.
- Different liquidity.
- Different quote timing.
A Receiver-side spread filter can therefore be useful when the trading plan requires copying to be blocked above a predefined spread threshold.
10. Spread Can Change During News
Even accounts advertised with very low spreads can experience wider spreads during major economic announcements, market openings, rollover periods, or periods of reduced liquidity.
Therefore:
Typical spread ≠ Guaranteed spread
When evaluating an account for copy trading, traders should observe actual spreads during the hours in which the strategy operates.
11. Commission Must Be Included in the Comparison
For an ECN or Raw Spread account, the commission should be converted into a comparable trading cost.
For example, if a broker charges a commission per standard lot per side, the trader should calculate the cost for both opening and closing the position.
Round-Turn Commission = Opening Commission + Closing Commission
The exact calculation depends on the broker's commission model and account currency.
For a fair comparison, compare the total cost of completing the trade rather than comparing the spread alone.
12. Trading Frequency Changes the Cost Impact
The number of trades can materially affect the cumulative cost of commissions and spreads.
| Strategy Type | Cost Sensitivity |
|---|---|
| High-frequency / Scalping | Often highly sensitive to spread and commission |
| Intraday | Moderate to high depending on trade frequency and target size |
| Swing | Entry/exit costs still matter, but may represent a smaller percentage of the target |
| Position Trading | Financing and holding costs can become more important |
This is why account selection should be based on the actual characteristics of the strategy being copied.
13. Contract Specifications Can Differ
Another issue that is sometimes overlooked is the contract specification of the Receiver symbol.
The same symbol name does not necessarily guarantee identical contract specifications across brokers.
Differences can include:
- Contract size.
- Minimum volume.
- Volume step.
- Maximum volume.
- Tick size.
- Tick value.
- Margin calculation.
This matters because copying the same numerical lot size does not necessarily mean copying the same economic exposure.
14. Lot Management Becomes Important
COPYLATOR provides multiple lot-management methods, including:
- Fixed lot.
- Lot multiplier.
- Balance-ratio scaling.
- Maximum lot cap.
These tools can help adapt the copied volume to the Receiver account.
However, lot scaling should always be evaluated together with the Receiver's contract specifications and risk characteristics.
15. Balance Ratio Does Not Equal Identical Risk
Suppose a Sender has a $10,000 balance and the Receiver has $1,000. A balance-ratio method can scale the volume according to the balance relationship.
That can make the position size more proportional, but it does not guarantee identical monetary risk.
Risk can still differ because of:
- Leverage.
- Contract size.
- Stop Loss distance.
- Symbol specifications.
- Currency conversion.
- Broker margin rules.
Therefore, balance ratio should be treated as a volume-scaling mechanism rather than a guarantee of identical risk.
16. Maximum Lot Cap as an Additional Control
A maximum lot cap can prevent the Receiver volume from exceeding a predefined limit.
For example:
Calculated Receiver Volume: 0.80
Maximum Lot Cap:            0.30

Final Allowed Volume:       0.30
This can be useful when copying strategies across accounts with different balances or when several Senders are connected to the same Receiver.
Again, a lot cap controls volume; it does not directly calculate the monetary risk of the position.
17. ECN vs. Standard and Copy Trading Frequency
A practical comparison should begin with the Sender strategy.
Ask the following questions:
- How many trades does the strategy open?
- What is the average profit target?
- How long are positions normally held?
- How sensitive is the strategy to entry and exit costs?
- Does it frequently modify Stop Loss and Take Profit?
- Does it trade around news?
The answers provide a more useful basis for account selection than the account label alone.
18. Account Type and Scalping
Scalping strategies typically operate with smaller targets and more frequent transactions.
Consequently, the combined effect of spread, commission, slippage, and execution latency can become significant.
An ECN or Raw Spread structure may be attractive if its total effective cost is lower for the specific strategy and Receiver conditions.
However, this should be verified with actual trading data rather than assumed from the advertised minimum spread.
19. Account Type and Swing Trading
Swing strategies typically hold positions longer and may use larger price targets.
The relative importance of entry spread may therefore be different from a high-frequency strategy.
However, commission and financing costs still need to be included in the overall calculation.
A Standard account may be perfectly workable if its total cost structure is appropriate for the strategy and Receiver conditions.
20. Copy Trading with Small Accounts
Cent and micro accounts can introduce additional restrictions.
Some brokers may not offer ECN-style conditions for smaller accounts, while others may provide different contract specifications or minimum-volume rules.
When copying to a small account, verify:
- Minimum lot.
- Volume step.
- Contract size.
- Commission.
- Spread.
- Margin requirements.
- Symbol availability.
The account type should be evaluated based on what is actually available for the Receiver rather than what the Sender uses.
21. Cross-Account Restrictions
Some brokers may apply restrictions to particular account types or internal copy-trading systems.
These policies are broker-specific and can change over time.
Therefore, traders should verify directly with the broker whether the intended Sender/Receiver arrangement is permitted.
Do not assume that two MT5 accounts can always be treated as economically identical simply because both use MetaTrader 5.
22. Symbol Mapping Still Matters
ECN and Standard accounts may use different symbol names or suffixes within the same broker environment.
For example:
Sender: EURUSD Receiver: EURUSD.raw
or:
Sender:   XAUUSD
Receiver: XAUUSDm
COPYLATOR's automatic symbol mapping can help identify corresponding symbols, while manual mappings can be used when automatic detection cannot find the appropriate relationship.
Correct mapping should be verified before live copying.
23. ECN, Standard, and Stop Levels
Account types can also have different trading specifications.
Before copying Stop Loss, Take Profit, or pending orders, check the Receiver symbol's:
- Stop Level.
- Freeze Level.
- Minimum distance requirements.
- Trading session.
A trade that is valid on the Sender may require different handling on the Receiver.
Real-time SL/TP synchronization can replicate supported changes, but broker-side restrictions still apply.
24. Execution Quality and VPS
Execution quality in copy trading depends on more than the account type.
Network latency between the MT5 terminal, broker server, and execution infrastructure can influence the time between the Sender trade and Receiver execution.
A VPS is strongly recommended for continuous automated copy trading, particularly when low latency and uninterrupted operation are important to the strategy.
However, a VPS is not technically mandatory if a dedicated computer can remain powered on, connected, and running the MT5 terminals reliably.
25. A Practical Cost Comparison
Instead of asking which account has the lower advertised spread, compare the complete cost structure.
| Cost Factor | Standard Account | ECN / Raw Spread Account |
|---|---|---|
| Quoted Spread | Often includes broker markup | Often closer to raw market spread |
| Separate Commission | May be absent or structured differently | Commonly charged |
| Spread During News | Can widen | Can also widen |
| Execution | Depends on broker | Depends on broker and liquidity |
| Total Cost | Spread and other applicable costs | Spread + commission + other applicable costs |
The actual numbers must be obtained from the specific broker and account being evaluated.
26. Testing the Receiver Account Before Going Live
A demo test can reveal differences that are not obvious from the account specification page.
Run the same copy-trading configuration and monitor:
- Average Receiver spread.
- Commission paid.
- Entry price differences.
- Exit price differences.
- Slippage.
- Trade frequency.
- Rejected orders.
- Margin usage.
- SL/TP synchronization.
After a meaningful sample, compare the Receiver's actual trading costs with the Sender's results.
27. A Better Way to Compare ECN and Standard Accounts
Instead of asking:
"Is ECN better than Standard?"
ask:
"What is the total cost and execution quality
of this Receiver account for this specific strategy?"
This question is more useful because the answer can change between brokers, instruments, trading sessions, and strategies.
28. Common Mistakes
| Mistake | Potential Consequence |
|---|---|
| Comparing only advertised spread | Commission and execution costs may be ignored |
| Assuming ECN guarantees faster execution | Actual infrastructure may differ |
| Using Sender costs as Receiver costs | Receiver performance may differ |
| Ignoring contract specifications | Position exposure may differ |
| Ignoring slippage | Actual entry/exit can differ from expectations |
| Ignoring swap | Long-held positions may accumulate financing costs |
| Skipping demo testing | Broker-specific issues may appear after going live |
29. Practical Checklist for Choosing a Receiver Account
- Identify the strategy's average trade frequency.
- Identify the typical profit target and Stop Loss.
- Check the Receiver's average spread during the strategy's trading hours.
- Calculate the ECN/Raw Spread commission.
- Compare total trading costs rather than spread alone.
- Check contract specifications.
- Check minimum and maximum volume.
- Check volume step.
- Verify symbol availability and mapping.
- Check leverage and margin requirements.
- Check Stop Level and Freeze Level.
- Verify any broker-specific restrictions on account types.
- Test the complete configuration on demo.
- Monitor actual execution and transaction costs.
30. Conclusion
ECN and Standard accounts can both be used as Receivers in MT5 copy trading, but they can produce different economic results because their pricing and execution structures may differ.
The important comparison is not simply the advertised spread. Traders should consider spread, commission, slippage, execution, contract specifications, margin requirements, financing costs, and the characteristics of the strategy being copied.
For a high-frequency strategy, transaction costs can represent a significant part of the expected gross return. For a lower-frequency strategy with larger targets, the relative impact of entry and exit costs may be different, while financing costs can become more relevant for longer holding periods.
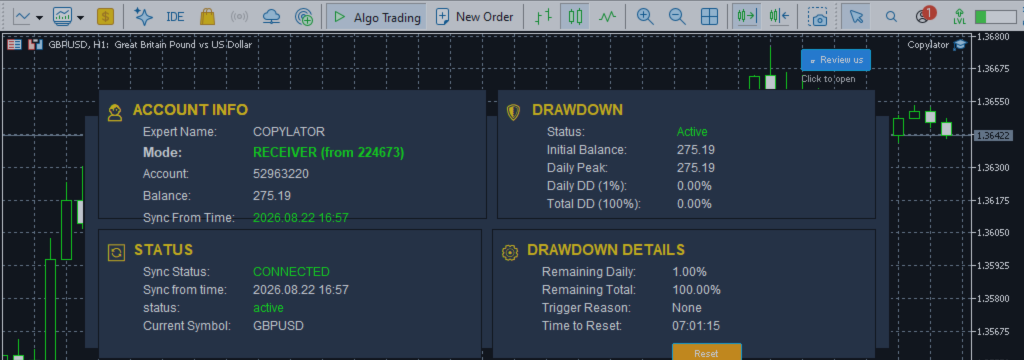
COPYLATOR can replicate the Sender's trading activity, synchronize supported SL/TP changes, manage lot sizes, apply spread and direction filters, map symbols, and provide drawdown protection. However, the Receiver remains subject to its own broker's pricing and execution environment.
The most practical approach is therefore to evaluate the actual Receiver conditions and test the complete setup before committing significant capital.
Choose the account based on: Strategy + Total Trading Cost + Execution Conditions + Contract Specifications + Risk Management
When these factors are evaluated together, the Receiver account becomes an integral part of the copy-trading system rather than simply a place where copied trades are executed.
Product link:
https://www.mql5.com/en/ market/product/191385