 MetaTrader 5
 Uzmanlar
 Göstergeler
 Komut dosyaları
 Kütüphaneler
 Depo
Alım-satım robotlarını ücretsiz olarak nasıl indirebileceğinizi izleyin
Bizi Telegram üzerinde bulun!
Fan sayfamıza katılın
Fan sayfamıza katılın
Kodu beğendiniz mi? MetaTrader 5 terminalinde deneyin

Simple volatility - MetaTrader 5 için gösterge

- Görüntülemeler:
- 9152
- Derecelendirme:
- Yayınlandı:
- Güncellendi:
-
 Alım-satım fırsatlarını kaçırıyorsunuz:
- Ücretsiz alım-satım uygulamaları
- İşlem kopyalama için 8.000'den fazla sinyal
- Finansal piyasaları keşfetmek için ekonomik haberler
Kayıt Giriş yapWeb sitesi politikasını ve kullanım şartlarını kabul edersiniz
Hesabınız yoksa, lütfen kaydolun -
 Bu koda dayalı bir robota veya göstergeye mi ihtiyacınız var? Freelance üzerinden sipariş edin
Freelance'e git
In a lot of cases we need some way to measure the volatility
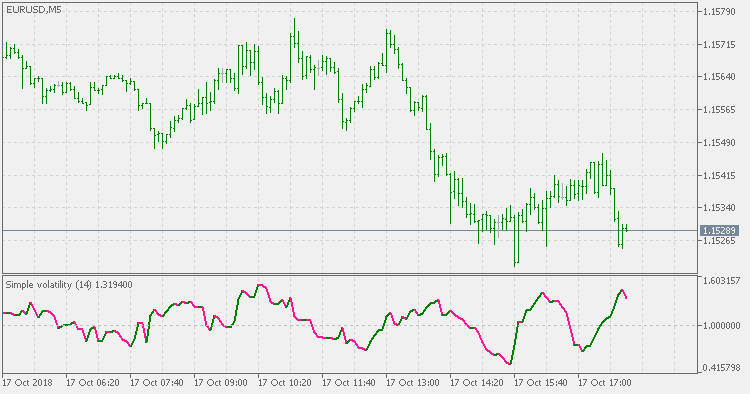
Among the other ways, here is one simple way : it is a ratio of (sum of price differences) to average of (sum of price differences). As simple as it gets, it seems to be detecting the market volatility in acceptable way. As a point of reference :
- values above 1 are periods of increased volatility
- values bellow 1 are periods of decreased volatility
As it can be seen it detects the volatility change OK even in a "thin" market (when the average difference is small and when even a small change is and should be treated as significant volatility change)
Volatility adjusted RSI
Volatility adjusted RSI
Volatility adjusted WPR
Volatility adjusted WPR (Williams Percent Range)