• Informations
2 années
expérience
4
produits
100
versions de démo
0
offres d’emploi
1
signaux
0
les abonnés
Professionnel en Finance et Commerce International avec une spécialisation en Gestion Financière. Développeur autodidacte en MQL5 et Python, spécialisé dans le trading algorithmique, la construction de portefeuilles multi-actifs et la gestion quantitative des risques.

Mon travail se concentre sur la conception, l'optimisation et la validation d'Expert Advisors qui fonctionnent comme un portefeuille coordonné plutôt que comme des stratégies isolées. J'applique l'analyse de corrélation, la cartographie de la couverture temporelle et la diversification par classe d'actifs pour construire des systèmes qui ne dépendent ni d'un seul instrument ni d'une seule approche.

Je gère actuellement des portefeuilles algorithmiques couvrant le forex, les indices, les métaux précieux, l'énergie et les actions américaines, opérant simultanément sur plusieurs sessions et horizons temporels.

Je partage mon expérience à travers des articles techniques et des outils open source au sein de cette communauté. Je suis convaincu que le passage de la « construction d'EAs individuels » à « l'ingénierie de portefeuilles » est ce qui sépare la pensée du trader particulier de celle de l'institutionnel, et ce principe guide tout ce que je publie ici.
Cristian David Castillo Arrieta
Build your own portfolio and connect it to your demo (free) or live account.

www.abacuquant.com
Cristian David Castillo Arrieta
Code publié Execution Cost Sensitivity Analyzer
Un script entièrement en MQL5 qui évalue la résistance de l'avantage d'une stratégie face aux coûts d'exécution. Il lit un fichier CSV contenant les dates, les bénéfices et les volumes des transactions clôturées, et modélise le coût de chaque transaction comme étant composé d'une partie fixe et d'une partie par lot. Il affiche le coût d’équilibre par transaction, la marge de sécurité (le multiple d’un coût réaliste supposé à partir duquel le bénéfice net atteint zéro), le bénéfice net et le facteur de profit réévalués au coût supposé, la proportion de transactions gagnantes que le coût transforme en transactions perdantes, ainsi qu’une note composite de robustesse face aux coûts (de A+ à F) accompagnée de recommandations. En l’absence de fichier, il génère un échantillon reproductible et l’analyse, de sorte que le résultat soit visible dès la première exécution. Pas de bibliothèques externes, pas de Python, pas d’IA.
Cristian David Castillo Arrieta
Article publié Beyond Maximum Drawdown: Building a Drawdown DNA Analyzer in MQL5
Beyond Maximum Drawdown: Building a Drawdown DNA Analyzer in MQL5

Maximum drawdown is one number that hides what really matters: how often an equity curve declines, how long it stays below a previous peak, and how quickly it recovers. This article builds a native MQL5 tool that reconstructs the underwater curve, breaks it into individual drawdown episodes (depth, duration, recovery time), computes the Ulcer Index, Pain Index, and Recovery Factor, and combines them into a single resilience grade with practical recommendations. No external libraries, no Python, no AI.

Cristian David Castillo Arrieta Produits publiés

Funded Trade Manager MT5 Most funded accounts are not lost to a bad strategy. They are lost to a single day that went too far: one oversized position, one revenge trade, one violated daily loss limit. Prop Firm Guard is a chart panel that applies the same limits your funding company applies, before the company does. What it does Tracks your daily loss limit and maximum drawdown in real time, using the same day-reset logic prop firms use (configurable server reset hour). Blocks any new trade

Cristian David Castillo Arrieta
Code publié Profit Concentration Analyzer
Un script MQL5 natif qui mesure le degré de concentration des bénéfices d’une stratégie — c’est-à-dire s’il s’agit d’un avantage généralisé ou s’il repose sur quelques transactions chanceuses. Il lit un fichier CSV contenant les données par transaction (Date, Bénéfice) et indique la part du bénéfice net provenant des transactions les plus importantes, le coefficient de Gini des transactions gagnantes, un profil de concentration, un test de survie qui élimine les quelques meilleures transactions et recalcule le bénéfice net et le facteur de profit, ainsi que le plus gros gain journalier par rapport à une limite de régularité configurable, le tout combiné en un score de concentration et de régularité (de A+ à F) accompagné de recommandations. Si aucun fichier n’est trouvé, il génère un ensemble d’échantillons, ce qui permet de l’utiliser immédiatement. Pas de bibliothèques externes, pas de Python, pas d’IA. L’assistant ExportTrades.mq5 génère le fichier à partir de votre historique de transactions.
Cristian David Castillo Arrieta
Code publié Drawdown DNA Analyzer
Un script MQL5 natif qui analyse la structure des baisses de capital d'un compte, et pas seulement le chiffre unique de la « baisse maximale ». Il lit une courbe de capital quotidienne (fichier CSV « Date,DailyPnL »), reconstitue la courbe « sous l'eau » et la divise en épisodes de baisse individuels avec leur ampleur, leur durée et leur temps de récupération. Il calcule ensuite l’indice d’ulcère, l’indice de douleur, le facteur de récupération et la durée passée en situation de perte, puis combine ces éléments en un score de résilience unique (de A+ à F) accompagné de recommandations, affichées dans l’onglet « Experts ». Aucune bibliothèque externe n’est requise ; si aucun fichier n’est trouvé, il génère une courbe d’exemple, ce qui lui permet de fonctionner dès son installation.
Cristian David Castillo Arrieta
Introduction: The Context-Blind Expert Advisor Problem A carefully optimized Expert Advisor completes six months of profitable forward testing. The equity curve is smooth, the drawdown is bounded, and the trade distribution looks healthy. On the first Friday of the seventh month, the EA opens a 0...
Cristian David Castillo Arrieta
This is the most power full EA
Cristian David Castillo Arrieta
Article publié Building a Correlation-Aware Multi-EA Portfolio Scorer in MQL5
Building a Correlation-Aware Multi-EA Portfolio Scorer in MQL5

Most algo traders optimize Expert Advisors individually but never measure how they behave together on a single account. Correlated strategies amplify drawdowns instead of reducing them, and coverage gaps leave portfolios blind during entire trading sessions. This article builds a complete portfolio scorer in MQL5 that reads daily P&L from backtest CSV files, computes a full Pearson correlation matrix, maps trading activity by hour and weekday, evaluates asset class diversity, and outputs a composite grade from A+ to F. All source code is included; no external libraries are required.

1
Cristian David Castillo Arrieta Produits publiés

ABQ Portfolio Correlation Scorer: Inteligencia Artificial de Grado Institucional para la Gestión de Riesgo La mayoría de los traders no fracasan por una mala estrategia de entrada, sino por una falla invisible en la arquitectura de su portafolio . El error más común es la sobreexposición por correlación: abrir múltiples posiciones pensando que se está diversificando, cuando en realidad se está multiplicando el riesgo sobre un mismo factor. ABQ Portfolio Correlation Scorer es un Copiloto de

Cristian David Castillo Arrieta
ABQ Visual Risk Sizer - Official User Manual Author: Cristian Castillo | AbacuQuant Version: 1.60 Platform: MetaTrader 5 (MT5...
Cristian David Castillo Arrieta Produits publiés

ABQ Visual Risk Sizer - Risque Institutionnel et Exécution de Transaction Catégorie : Utilitaires / Gestion du Risque Le calcul manuel des lots coûte du temps et de l'argent. Dans le trading moderne, particulièrement lors de la gestion de comptes financés (Prop Firms), une erreur de calcul de lotissage ou un délai de 5 secondes lors de la saisie d'un ordre peut signifier la violation de la règle de Drawdown quotidien ou la perte du prix d'entrée parfait. ABQ Visual Risk Sizer est un outil de

Cristian David Castillo Arrieta
Code publié Portfolio Scorer — Multi-EA Correlation and Coverage Analyzer
Portfolio Scorer is a standalone MQL5 script that evaluates the quality of a multi-EA portfolio across three critical dimensions that most algo traders overlook. The script reads daily profit and loss data from CSV files (one per Expert Advisor), computes a full Pearson correlation matrix between every strategy pair, maps trading activity by UTC hour and weekday, detects asset class diversity, and produces a weighted composite score with a letter grade from A+ to F. How it works: The tool runs in four sequential stages. First, the Data Loader reads and validates CSV files containing daily returns for each EA in the portfolio. Second, the Correlation Engine calculates the complete NxN Pearson correlation matrix and flags pairs that exceed a configurable threshold. Third, the Coverage Analyzer maps which hours and weekdays have active trading and identifies blind spots. Fourth, the Scoring Function combines all three dimensions into a single composite score using adjustable weights.
Cristian David Castillo Arrieta
It was late 2022. I had spent six months building what I believed was the perfect Expert Advisor. The backtest was gorgeous: Profit Factor 3.2, maximum drawdown under 5%, a Sharpe ratio that would make a hedge fund manager jealous . I had optimized every parameter. Every indicator period...
Cristian David Castillo Arrieta
AbacuQuant 3.7 — The Complete User Manual: From Installation to Live Portfolio A comprehensive, practical guide to configuring, optimizing, and deploying AbacuQuant — the institutional-grade algorithmic trading system for MetaTrader 5...
Cristian David Castillo Arrieta
AbacuQuant 4.10 — Complete User Manual & Setup Guide The definitive reference for installation, configuration, prop-firm compliance, local AI setup, portfolio analysis, and live deployment. LIVE SIGNAL: CLICK HERE Table of Contents Introduction — What's New in v4...
Cristian David Castillo Arrieta 5 Signal MetaTrader publié
AbacuQuant
Prix: 30 USD, Croissance: 6.63%
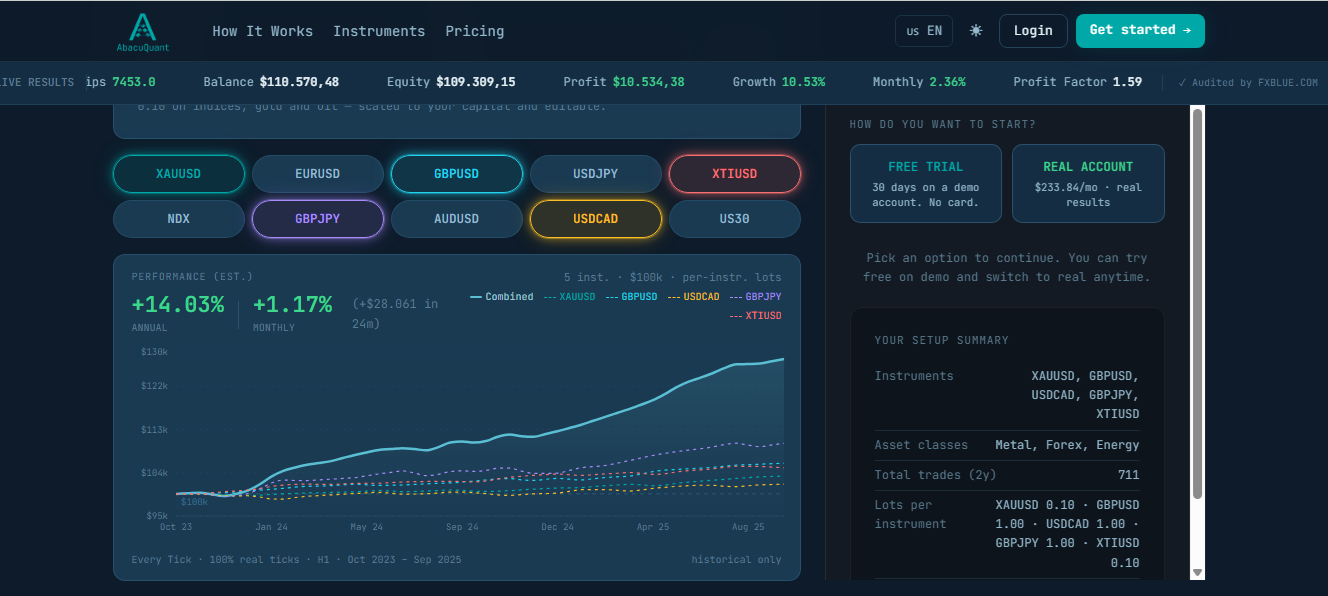
AbacuQuant: Systematic Trading with Institutional Discipline Why most traders fail—and why AbacuQuant is different. The financial markets punish emotion. Fear triggers early exits. Greed extends losing positions. Fatigue leads to missed opportunities. Over 90% of retail traders lose money not because they lack intelligence, but because they lack discipline. AbacuQuant eliminates the human factor entirely. A Portfolio-Based Approach to Algorithmic Trading AbacuQuant is not a single strategy
Cristian David Castillo Arrieta
🔍 The One Question Every Trader Asks — And Why Most Never Find the Answer

“Are my settings actually working… or am I just lucky?”
Be honest. You’ve been there.
You find a strategy that looks promising. You tweak a moving average here, adjust a stop loss there, maybe change the timeframe. It works for a week. Then the market shifts — and everything falls apart.
So you start over. Again.
This isn’t a failure of discipline. It’s a failure of process. Manual optimization is a guessing game disguised as analysis. You’re testing a handful of combinations out of thousands — maybe millions — of possibilities. The odds of landing on the best parameters by hand? Almost zero.

What If Your EA Could Find the Answer for You?
This is exactly the problem AbacuQuant was built to solve.
AbacuQuant doesn’t just give you a strategy. It gives you a framework to discover the optimal version of that strategy — for any instrument, on any timeframe, under real market conditions.
Here’s how:
→ One EA. 10+ Built-In Strategies.
From Fibonacci confluences and imbalance detection to Bollinger reversals and candlestick pattern recognition — AbacuQuant packs institutional-grade strategies into a single Expert Advisor. You don’t need ten different EAs. You need one that adapts.
→ Full Optimization Power Across Any Market.
EURUSD on H1? Gold on M15? NASDAQ on H4? It doesn’t matter. AbacuQuant’s architecture is instrument-agnostic and timeframe-flexible. Run the MetaTrader 5 Strategy Tester, and let the optimization engine do what no human can: test thousands of parameter combinations systematically to surface the configurations that actually perform — not the ones that just look good on a single backtest.
→ AI-Assisted Analysis to Confirm What the Data Shows.
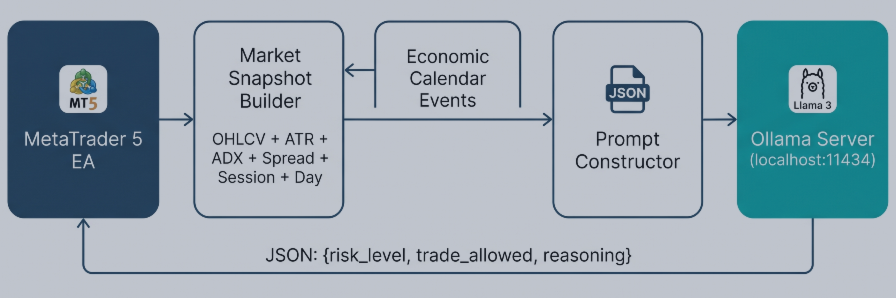
Here’s where it gets powerful. AbacuQuant integrates directly with AI models (OpenAI, Google Gemini, DeepSeek) to provide a second layer of confirmation. Before entering a trade, the AI analyzes current market context — trend structure, volatility regime, key levels — and validates whether the signal aligns with broader conditions. It’s like having a senior analyst reviewing every setup before execution.

The Real Edge Isn’t the Strategy. It’s the Process.
Most traders spend years searching for the “perfect” strategy. The truth? No single set of parameters works forever. Markets evolve. What separates profitable traders from the rest is the ability to re-optimize, re-validate, and re-deploy — quickly and confidently.
With AbacuQuant, that process looks like this:
1. Select your instrument and timeframe.
2. Run optimization using the MT5 Strategy Tester with your preferred criteria.
3. Analyze the results — filter by profit factor, drawdown, recovery factor.
4. Enable AI confirmation to add a layer of contextual intelligence.
5. Deploy with confidence, knowing your parameters are data-driven, not gut-driven.
Whether you’re building a single-instrument setup or constructing a diversified multi-asset portfolio, AbacuQuant scales with you.

Don’t Take Our Word for It. Test It Yourself.
AbacuQuant is available for free download in demo mode on the MQL5 Market. No commitment. No risk. Just results you can verify on your own charts, with your own instruments, on your own terms.

👉 Download the demo now and run your first optimization today.
Because the best time to stop guessing was yesterday. The second best time is right now.
123