 MetaTrader 5
 Experts
 Indicators
 Scripts
 Libraries
 Storage
Watch how to download trading robots for free
Find us on Twitter!
Join our fan page
Join our fan page
You liked the script? Try it in the MetaTrader 5 terminal

ASQ Spread Logger - indicator for MetaTrader 5
Muharrem Rogova

Founder of AlgoSphere Quant — building a complete ecosystem of rule-based MT5 trading tools.
Our philosophy: market structure first, strict risk management always, zero martingale.
We build for traders who trade with discipline — not with hope.
──────────────────────────
EXPERT ADVISORS
Our philosophy: market structure first, strict risk management always, zero martingale.
We build for traders who trade with discipline — not with hope.
──────────────────────────
EXPERT ADVISORS
- Views:
- 2295
- Rating:
- Published:
- Updated:
-
 You are missing trading opportunities:
- Free trading apps
- Over 8,000 signals for copying
- Economic news for exploring financial markets
Registration Log inYou agree to website policy and terms of use
If you do not have an account, please register -
 Need a robot or indicator based on this code? Order it on Freelance
Go to Freelance
ASQ Spread Logger — Track Every Pip of Spread
AlgoSphere Quant — Precision before profit.
ASQ Spread Logger is a lightweight indicator that monitors spread in real time and gives you the data to make better entry decisions. Whether you scalp during tight sessions or avoid news spikes, this tool shows you exactly what your broker is charging — and logs it for later analysis.
What it does
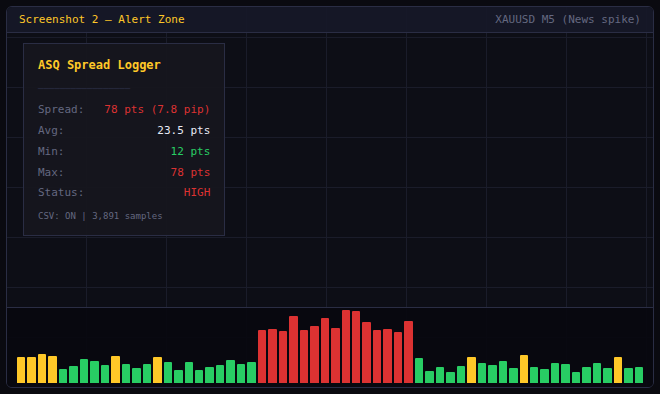
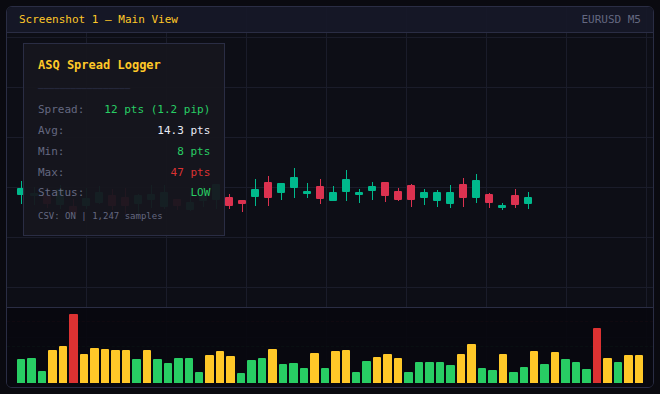
The indicator draws a color-coded histogram in a separate window: green when the spread is low, gold when it is moderate, and red when it exceeds your threshold. A clean on-chart panel displays the current spread in both points and pips, the rolling average, the minimum and maximum over your chosen window, and the current status level.
Every data point can be logged to a CSV file (DateTime, Symbol, Spread, Bid, Ask, Avg, Min, Max, Status) so you can analyze spread behavior across sessions, days, or brokers in Excel or Python. Three logging frequencies are available: every tick, every second, or once per new bar.
When the spread exceeds your high threshold, the indicator fires an alert with configurable cooldown. Push notifications and email alerts are also supported.
Features
- Color-coded spread histogram (green / gold / red) in a separate window
- On-chart statistics panel: current spread, average, min, max, status
- CSV export to MQL5/Files/ with full bid/ask and status data
- Three logging modes: every tick, every second, every new bar
- Configurable low/high thresholds in points
- Threshold reference lines on the histogram
- Alert popup + optional push notification + email
- Alert cooldown to prevent spam
- Panel corner, offset, font, and color customization
- Automatic pip conversion for 3/5-digit brokers
- Minimal CPU usage — single-file, no external dependencies
Use cases
- Scalping: enter only when the spread is below your threshold
- News trading: monitor spread expansion before and after high-impact events
- Broker comparison: log spread data across multiple brokers and compare in Excel
- Session analysis: identify which hours offer the tightest spreads
- Prop firm compliance: document that you traded during acceptable spread conditions
Parameters
Spread Thresholds: Low threshold, High threshold (points). CSV Logging: Enable/disable, frequency (tick/second/bar), custom filename. Statistics: Rolling window size. Alerts: Enable, push, email, cooldown in seconds. Display: Panel on/off, corner, offset, font size, colors for background, text, header, good/warn/bad levels, threshold lines, max bars.
Installation
- Download ASQ_SpreadLogger.mq5
- Place in MQL5/Indicators/
- Compile in MetaEditor (zero dependencies)
- Drag onto any chart
Compatibility
MetaTrader 5, all brokers, all instruments (Forex, Metals, Indices, Crypto), all timeframes.
Free and open-source under the AlgoSphere Quant brand.
 Portfolio Scorer — Multi-EA Correlation and Coverage Analyzer
Portfolio Scorer is a standalone MQL5 script that evaluates the quality of a multi-EA portfolio across three critical dimensions that most algo traders overlook. The script reads daily profit and loss data from CSV files (one per Expert Advisor), computes a full Pearson correlation matrix between every strategy pair, maps trading activity by UTC hour and weekday, detects asset class diversity, and produces a weighted composite score with a letter grade from A+ to F. How it works: The tool runs in four sequential stages. First, the Data Loader reads and validates CSV files containing daily returns for each EA in the portfolio. Second, the Correlation Engine calculates the complete NxN Pearson correlation matrix and flags pairs that exceed a configurable threshold. Third, the Coverage Analyzer maps which hours and weekdays have active trading and identifies blind spots. Fourth, the Scoring Function combines all three dimensions into a single composite score using adjustable weights.
Candle Body Ratio
An original indicator designed to analyze price action and provide buy/sell signals.
ASQ Trading Journal Export
One-click CSV export of trade history with P&L, duration & stats
Institutional Gaussian Signal Filter (Zero-Lag ALMA)
A quantitative Gaussian filter designed to replace lagging retail moving averages by applying advanced digital signal processing to eliminate market noise without sacrificing responsiveness.