Why Institutional FX Edge Lives at Multi-Currency Extremes

In foreign exchange markets, retail traders overwhelmingly gravitate toward momentum chasing—buying breakouts after an impulse has already exhausted its statistical fuel. Quantitative desks and liquidity providers operate on the opposite premise: while short-term price action exhibits serial correlation, relative currency valuation across a closed basket of major currencies is fundamentally mean-reverting. Understanding how to measure currency extremes mathematically—and knowing when a macro divergence has reached structural exhaustion—is the difference between catching a high-probability institutional reversal and stepping in front of a runaway train.
1. The Mathematics of Mean Reversion in Currency Baskets
In quantitative finance, mean-reverting dynamics are classically modeled through the Ornstein–Uhlenbeck (O–U) stochastic process :
dX(t) = θ · (μ − X(t)) · dt + σ · dW(t)
- X(t) represents the normalized relative strength index of a currency at time t;
- μ is the long-term equilibrium mean (zero net divergence);
- θ > 0 is the rate of mean reversion (the "elastic pull" back toward equilibrium);
- σ denotes instantaneous volatility, and W(t) is a standard Wiener process.
When an exogenous shock or liquidity sweep pushes X(t) multiple standard deviations away from μ , the drift term θ · (μ − X(t)) grows proportionally larger. In practical trading terms, expected return per unit of risk peaks precisely at statistical extremes , where marginal buyers are exhausted and institutional contrarian liquidity steps in to absorb order flow.
2. Why Single-Pair Oscillators Fail at Extremes
- Isolated USD weakness (where EUR is flat and shorting EUR/USD puts you against a broad dollar sell-off), versus
- True structural divergence (where EUR is simultaneously overbought across all 7 EUR crosses while USD is simultaneously oversold across all 7 USD pairs).
To quantify normalized momentum without lag distortion, modern quantitative engines apply double-smoothed exponential normalization —taking the ratio of double-smoothed directional price displacement to double-smoothed absolute displacement:
TSI_norm = 100 × [ EMA_r( EMA_s(ΔP) ) / EMA_r( EMA_s(|ΔP|) ) ]
By mapping this normalized oscillator onto discrete quantization regimes (step thresholds) , noise is stripped away, isolating only genuine macro regime shifts where currency strength reaches statistical saturation.
3. Volatility-Adjusted Risk: Surviving the "Last Mile" of an Extreme
Instead, stop placement must scale dynamically with the Average True Range (ATR) of the target pair and timeframe:
SL_Reversal = k × (1 / N) × ∑ max( H_i − L_i , |H_i − C_(i−1)| , |L_i − C_(i−1)| )
By anchoring risk distance to a calibrated volatility multiplier (k · ATR_N ), your position absorbs normal market breathing room while maintaining strict mathematical invalidation if a true structural breakout occurs.
4. Turning Quantitative Theory into Execution: Altopium Currency Extreme MTF
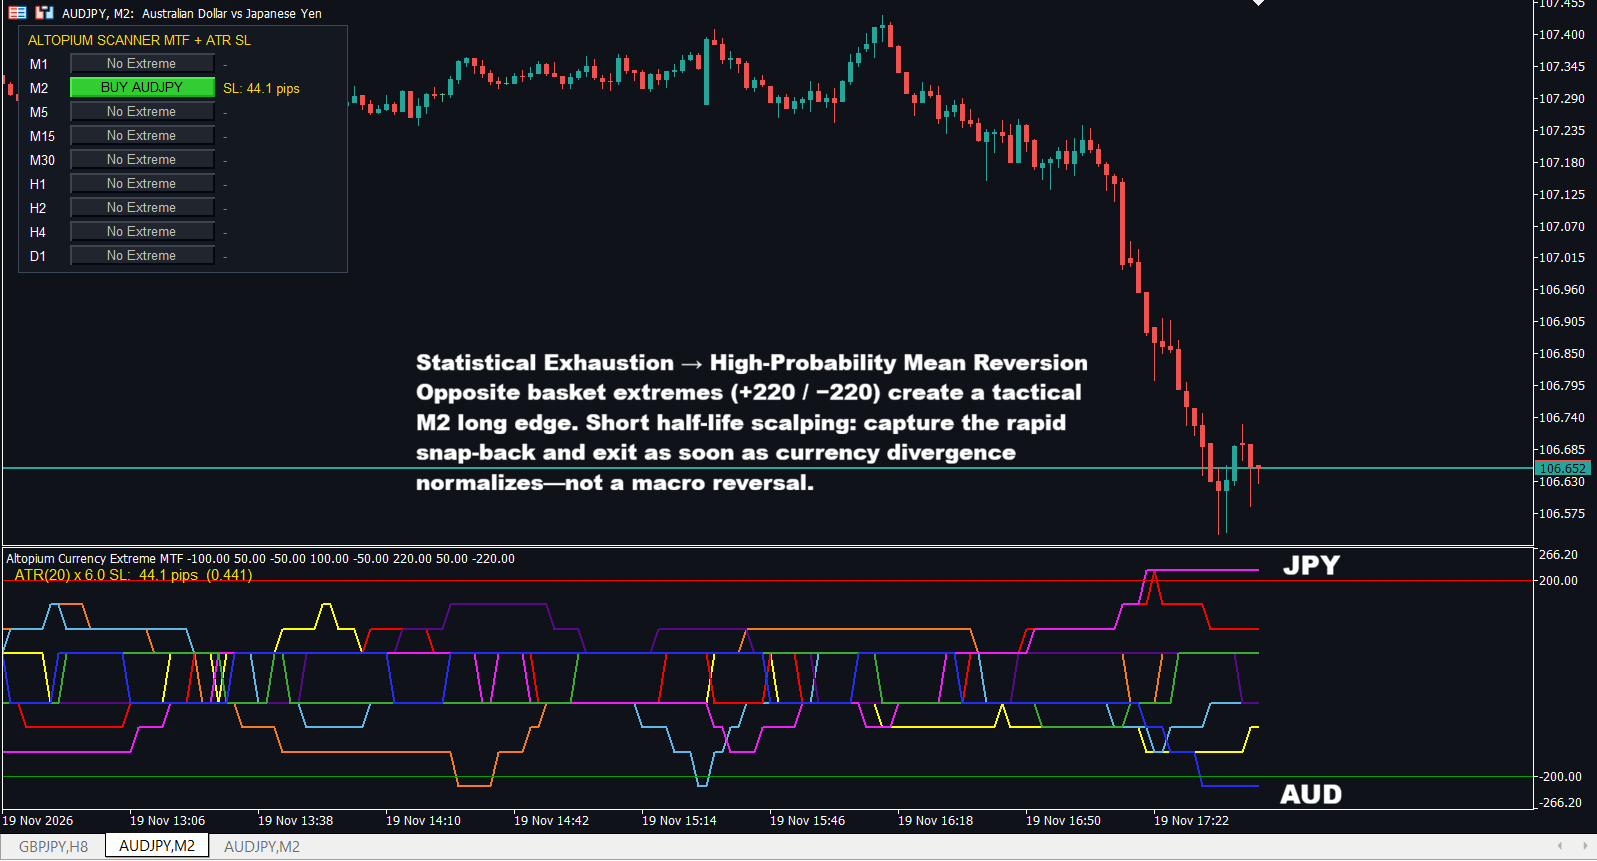
- Full 28-Pair Matrix Decomposition: Continuously evaluates all 8 major currencies across 9 Timeframes (M1, M2, M5, M15, M30, H1, H2, H4, D1) using synchronized historical feeds and incremental smoothing.
- Quantized Extreme Regime Visualization: Plots clean step-regime currency lines in a dedicated subwindow, making macro divergences between the strongest and weakest currencies immediately visible.
- Automated Contrarian Pairing & Ranking: Automatically matches the most overbought currency against the most oversold currency, selects the highest-conviction pair on the active broker feed, and highlights Extreme Strength / Extreme Weakness divergence alerts.
- Built-In ATR Reversal Stop-Loss Engine: Calculates exact volatility-scaled Stop Loss distances (in both pips and price points) for every active timeframe signal and displays live chart reference metrics.
- One-Click Chart Navigation & Alerts: Click any active timeframe button on the dashboard to immediately launch the corresponding pair and timeframe chart, backed by real-time sound and email notifications.
👉 Explore Altopium Currency Extreme MTF on the MQL5 Market today : https://www.mql5.com/it/market/product/208979