How We Validate a 9-Strategy USDJPY Portfolio Beyond a Single Backtest

A profitable backtest is useful. But a profitable backtest alone does not tell us whether a trading system deserves real capital.
A strategy can look impressive for reasons that have little to do with a durable edge. It may have benefited from a favorable market regime, a particular parameter choice, too few trades, optimistic execution assumptions, or simple historical luck.
That is why the development of the EdgeDriven Dollar Yen Portfolio was not centered on producing the best-looking equity curve.
The objective was to build a fixed multi-strategy USDJPY portfolio, then examine how that portfolio behaved across different historical periods, risk conditions and operating constraints.
The result is a fixed nine-strategy USDJPY portfolio for MetaTrader 5.
This article explains how we evaluate it — and, just as importantly, what the available evidence does not prove.
1. Why use a portfolio instead of one strategy?
Every strategy has market conditions where it tends to perform better and conditions where it struggles.
A trend-following strategy, for example, may perform well when price moves persistently in one direction but suffer during choppy markets. A mean-reversion strategy may behave almost the opposite way.
The EdgeDriven Dollar Yen Portfolio combines nine fixed H2 strategy modules that respond to different price, momentum and volatility conditions.
The goal is not to create nine separate promises of future profit.
All nine modules trade USDJPY, so they still share:
- the same underlying instrument,
- account margin,
- broker execution conditions,
- and the possibility of losing at the same time.
The purpose of the portfolio is simpler: avoid making the entire system dependent on one entry logic or one type of market behavior.
The portfolio membership and relative construction are fixed. Modules are not switched on and off according to recent performance.
2. Separate the development process from the final assessment
One of the easiest ways to overestimate a strategy is to keep changing it while repeatedly looking at the same historical data.
If every poor result leads to another filter, parameter change or rule adjustment, the strategy can gradually become better at explaining the past rather than better at surviving the future.
To reduce that problem, the portfolio research was divided into three historical stages.
Development — January 2014 to December 2022
This period was used for portfolio construction and candidate selection.
Validation — January 2023 to December 2024
Development and Validation information were used for portfolio-level narrowing and priority setting.
Final Historical Holdout Confirmation — January 2025 to June 2026
The selected portfolio structure had already been fixed before this period was evaluated at portfolio level.
No portfolio membership, weighting or ranking changes were made after the Final period was reviewed.
There is an important limitation here.
The Final period is not claimed to be completely untouched, never-seen data for every individual strategy. Some component strategies had already seen parts of later data during earlier research or formal qualification.
That is why we describe this stage as Final Historical Holdout Confirmation rather than presenting it as something stronger than the evidence supports.
Being precise about what a test can and cannot demonstrate is part of the validation process.
3. Current historical reference
The current production reference is Version 1.103.
Reference configuration:
- USDJPY
- H2
- USD 10,000 initial capital
- MT5 hedging account
- Leverage 1:100
- BaseRiskPercent = 0.9
- ProductRiskScale = 1.0
- Compounding = false
- RestrictedNewsGuard = true
- MetaQuotes-Demo real-tick test mode
| Period | Net Profit | MT5 PF | Equity DD at maximal money drawdown | Trades |
|---|---|---|---|---|
| 2014–2022 Development | USD 4,193.96 | 1.61 | 4.06% | 2,400 |
| 2023–2024 Validation | USD 663.73 | 1.48 | 1.66% | 555 |
| 2025–June 2026 Final Historical Holdout Confirmation | USD 524.74 | 1.56 | 1.62% | 431 |
| 2014–June 2026 Combined History | USD 5,382.43 | 1.58 | 4.06% | 3,386 |
The first three rows are separately initialized tests. The Combined row is one continuous test across the full historical period.
The DD percentages use the equity peak associated with the MT5 maximal money drawdown, not initial capital. For the Combined test, the native result is USD 446.27 (4.06%). These are historical observations, not future loss limits. The report includes zero commission; broker costs and execution can differ. Monthly cash includes posted profit, commission and swap, not open-position mark-to-market returns.
The Combined result is descriptive history, not another independent validation sample.
The continuous history also includes both winning and losing periods:
- 96 positive calendar months
- 54 negative calendar months
- Worst posted-cash month: January 2015, −USD 212.10
A profitable final result does not mean the path was smooth.
That path matters.

Native MT5 tester results, Dollar Yen Portfolio Version 1.103, historical simulation. Saved MT5 screenshot; figures and curves have not been redrawn. Open the image for the full-size view.
View the original MT5 screenshot at full size
4. Why trade count matters
A high Profit Factor can look impressive, but the number of trades behind it matters.
A PF based on 30 trades tells us something very different from a PF based on several thousand trades.
The combined reference contains 3,386 historical trades.
That does not make the result reliable by itself, and more trades do not automatically mean a better strategy. But a larger sample gives us more observations across different environments, including periods when the system performs poorly.
That makes it easier to examine:
- drawdowns,
- losing periods,
- changes in market conditions,
- execution behavior,
- and whether the result depends too heavily on a small number of trades.
The trade count is therefore not a quality score. It is part of the evidence behind the statistics.
5. Risk management is part of the strategy
Position sizing should not be treated as something separate from strategy validation.
The reference configuration uses:
BaseRiskPercent = 0.9
At ProductRiskScale = 1.0 , that reference percentage is divided across nine nominal module entry budgets before broker rounding.
In simple terms, the nominal sizing basis is approximately 0.1% per module entry before rounding.
That does not mean a trade can lose no more than 0.1%, or that the portfolio can lose no more than 0.9%.
Actual losses can differ because of:
- gaps,
- slippage,
- simultaneous positions,
- pending-order fills,
- broker execution,
- and minimum-lot constraints.
This is also why the EA does not increase the position size merely to force a trade.
If the calculated size is below the broker's minimum lot and using the minimum lot would exceed the allowed sizing budget, the trade can be skipped.
That behavior is intentional.
The objective is to preserve the sizing rule, not to maximize the number of trades taken.
6. Why the News Guard belongs in the historical evidence
Scheduled macroeconomic events can materially change spreads, short-term volatility and execution quality.
For that reason, the current production EA includes a Restricted USD News Guard.
In historical Strategy Tester runs, the EA uses the frozen restricted-news windows used during development.
In live operation, it uses the MetaTrader 5 Economic Calendar to identify the corresponding future USD events.
During an active restricted window — five minutes before through five minutes after the event — the EA:
- blocks new entries,
- requests cancellation of its owned pending orders,
- and requests closure of its owned open positions.
This does not create perfect protection.
The actual result still depends on terminal connectivity, incoming quotes, trading permissions, broker sessions and execution.
A News Guard cannot eliminate gap risk or guarantee an exit price.
Its purpose is narrower: reduce scheduled-event exposure under a defined set of rules.
Because those rules affect which trades are taken, they must also be part of the historical test used to represent the production EA.
7. The production EA should match the system that was tested
A backtest is much less useful if the production EA operates differently from the version that produced the published evidence.
During final product QA, the News Guard implementation was reviewed again to confirm that:
- historical testing used the intended frozen event windows,
- live operation could obtain future event information through the MT5 Economic Calendar,
- and failure to obtain healthy calendar data would block new entries rather than silently ignore the protection.
After the development-consistent News Guard was restored to the production EA, the historical reference was regenerated using the current production version.
This may sound like a technical detail, but it is important.
Historical evidence should describe the product that is actually being distributed, not a materially different research build.
8. What the historical results do not prove
Even a long real-tick historical test remains a simulation.
The results above do not establish:
- future Profit Factor,
- future monthly returns,
- a maximum future drawdown,
- identical performance at another broker,
- independence between the nine modules,
- protection from extreme gaps or slippage,
- or future profitability.
Historical results are also affected by assumptions and data quality, including:
- spreads,
- commission,
- swap,
- quote history,
- execution modeling,
- broker specifications,
- and changes in market structure.
The goal of validation is therefore not to remove uncertainty.
That is impossible.
The goal is to reduce avoidable uncertainty and make the remaining uncertainty visible.
9. Why I prefer evidence over one attractive equity curve
An equity curve is easy to understand.
That is exactly why it can be dangerous to rely on it too heavily.
A smooth upward curve summarizes the final result, but it does not show the full development process behind that result.
When I evaluate an automated strategy, I would rather ask questions such as:
- How many trades produced the result?
- What data was used to build the portfolio?
- What was fixed before the later assessment period?
- How did Validation compare with Development?
- Were there losing months?
- How was position size calculated?
- What happens when the broker minimum lot is too large?
- How are scheduled macro events handled?
- Does the production EA use the same controls as the historical test?
- What limitations remain?
Those questions are less exciting than a large return percentage.
But they are more useful when deciding whether a system deserves real capital.

Native MT5 Balance, Equity and Deposit Load graph, Dollar Yen Portfolio Version 1.103, historical simulation. Saved MT5 screenshot; figures and curves have not been redrawn. Open the image for the full-size view.
View the original MT5 screenshot at full size
10. Live monitoring is separate evidence
Historical evidence is only one stage.
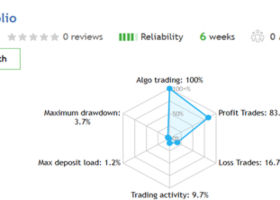
Update, 12 October 2026: the public MQL5 monitoring record began on 14 September 2026. It is a JPY-denominated real account at GaitameFinest-LIVE with leverage 1:25. The product description lists ProductRiskScale=4.0, BaseRiskPercent=0.9, Compounding=false and RestrictedNewsGuard=true for this setup. These differ from the historical reference above; neither cash profit nor percentage return and drawdown should be compared directly across the two configurations. The record remains short and does not establish future performance.
The purpose is not to prove that future returns must match the backtest.
Forward monitoring can instead help us observe things that historical testing cannot fully reproduce, including:
- live execution,
- actual strategy participation,
- broker conditions,
- real drawdown behavior,
- News Guard operation,
- and differences between historical modeling and live trading.
Any Forward record should be presented separately from the historical simulations, with its own account type, start date, product version and settings clearly disclosed.
Conclusion
The EdgeDriven Dollar Yen Portfolio was not selected because one backtest happened to look attractive.
The current evidence includes:
- nine fixed USDJPY strategy modules,
- 3,386 historical trades,
- separate Development, Validation and Final Historical Confirmation periods,
- Combined historical MT5 PF 1.58,
- modeled maximum equity drawdown of 4.06% at the reference configuration,
- a Restricted USD News Guard,
- and explicit operating and evidence limitations.
None of these things guarantees future profitability.
They simply provide more information with which to judge the system.
That is the principle behind EdgeDriven Algo:
Edge, Backed by Evidence.
The EdgeDriven Dollar Yen Portfolio is available on the MQL5 Market for readers who want to review the product details, operating requirements and historical reference evidence.
Historical simulations are not live or Forward results. Leveraged trading can cause substantial losses.