 MetaTrader 5
 Sistemi Esperti
 Indicatori
 Script
 Librerie
 Archiviazione
Guarda come scaricare robot di trading gratuitamente
Ci trovi su Facebook!
Unisciti alla nostra fan page
Unisciti alla nostra fan page
Ti è piaciuto lo script? Provalo nel Terminale MetaTrader 5

i-SpectrAnalysis_Momentum - indicatore per MetaTrader 5

- Visualizzazioni:
- 4391
- Valutazioni:
- Pubblicato:
- Aggiornato:
-
 Ti stai perdendo delle opportunità di trading:
- App di trading gratuite
- Oltre 8.000 segnali per il copy trading
- Notizie economiche per esplorare i mercati finanziari
Registrazione AccediAccetti la politica del sito e le condizioni d’uso
Se non hai un account, registrati -
 Hai bisogno di un robot o indicatore basato su questo codice? Ordinalo su Freelance
Vai a Freelance
Real author:
klot
This indicator is an example of smoothing the Momentum indicator timeseries by filtering high-order harmonics.
You can use this approach for smoothing the output of any indicator. The major advantage of this method is that it has practically zero latency.
Indicator input parameters:
input int   MomentumPeriod=14;
input ENUM_APPLIED_PRICE   MomentumPrice=PRICE_MEDIAN;
input uint N = 7;   // Series length
input uint SS = 20; // Smoothing coefficient
input int Shift=0;  // Horizontal indicator shift in bars
where:
- N — sets the series length (power of two);
- SS — smoothing coefficient in the resulting spectrum zeroes out frequencies exceeding the set value. SS cannot be greater than 2^N. If SS = 2^N, the Momentum series is repeated.
This indicator requires the following library: https://www.mql5.com/ru/code/7000.
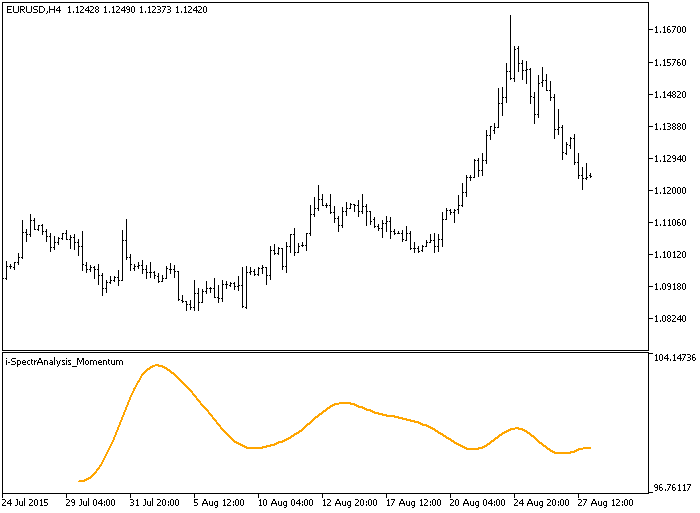
Fig.1. The i-SpectrAnalysis_Momentum indicator
Tradotto dal russo da MetaQuotes Ltd.
Codice originale https://www.mql5.com/ru/code/13737
 Exp_i-KlPrice
The Exp_i-KlPrice Expert Advisor is based on the i-KlPrice histogram breaking through the overbought and oversold levels.
Exp_i-BandsPrice
The Exp_i-BandsPrice Expert Advisor is based on the i-BandsPrice histogram breaking through the overbought and oversold levels.
i-SpectrAnalysis_TriX
This indicator is an example of smoothing the TriX indicator timeseries by filtering high-order harmonics.
i-SpectrAnalysis_MA
This indicator is an example of smoothing the Moving Average indicator timeseries by filtering high-order harmonics.